
AIXTRON (XTRA:AIXA) Lifts Guidance As AI Orders Surge, But Is The Stock Already Fully Valued?
AIXTRON (XTRA:AIXA) lifted its guidance after reporting strong orders for AI related laser equipment, a shift that pushed the stock sharply higher as traders reassessed risks around SiC overcapacity and Chinese competition.
Even with today’s jump to about €29.44, AIXTRON has given back some ground recently, with the 7 day share price return down 10.16% and the 30 day share price return down 15.40%. However, the year to date share price return of 50.28% and 1 year total shareholder return of 121.17% still highlight the strong momentum that this upgraded AI guidance has brought back into focus.
Scan AI hardware plays moving on similar guidance upgrades, with a curated set of 55 AI infrastructure stocks that echo the AIXTRON story in different corners of the chip supply chain.
AIXTRON now appears to be a stronger AI hardware supplier than many investors appreciated after the pullback. The key question is whether the current price already reflects that strength or still leaves meaningful upside potential.
Most Popular Narrative: 39% Undervalued
Analysts following AIXTRON see a fair value of €48.54, well above the last close at €29.44. This frames the whole AI optics story as a sizeable valuation gap rather than a marginal mispricing.
The mix shift toward higher margin optoelectronics equipment and a growing contribution from aftersales and service, which has reached around 30% to 40% of group sales in weaker quarters, creates a larger recurring revenue base that can smooth earnings through cycles and support more resilient gross margin and EBIT margin performance.
See why 41 investors see AIXTRON as 39% undervalued.
Result: Fair Value of €48.54 (UNDERVALUED)
Still, if SiC and GaN capacity stay underused for longer or if AI optics orders slow, the bullish AIXTRON narrative could unwind faster than expected.
Find out about the key risks to this AIXTRON narrative.
Another View: AIXTRON Looks Expensive On Earnings
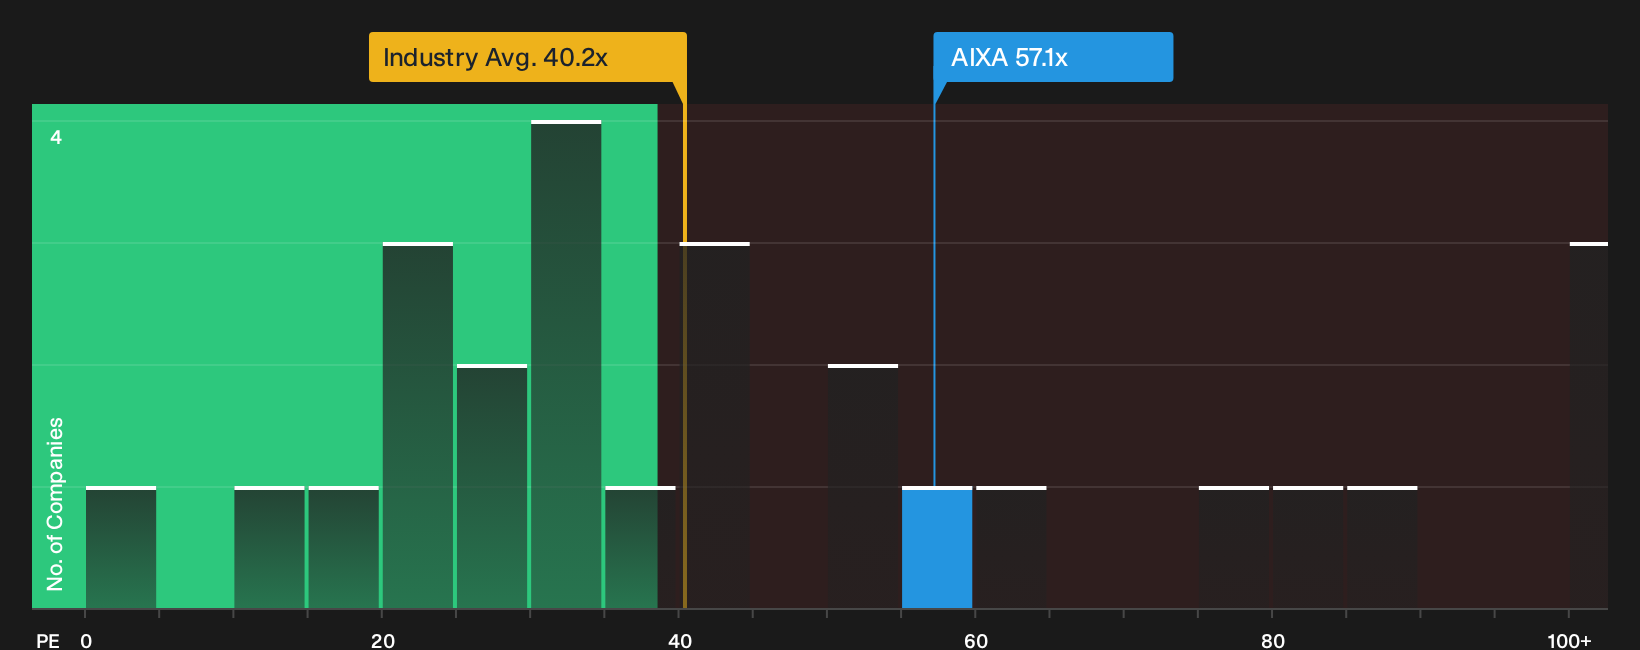
Analyst targets suggest upside for AIXTRON, yet the current P/E near 57x tells a different story. That level sits well above the European semiconductor group on 40.2x and above a fair ratio of 54.5x, which points to richer pricing and higher valuation risk if expectations cool.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on AIXTRON’s valuation and risk profile can be confusing. Consider moving quickly to review the underlying data yourself and weigh both the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond AIXTRON?
If you only stop at AIXTRON, you could miss out on other stocks that fit your style, risk tolerance, and income goals across the market.
- Target quality at a discount by scanning a curated 195 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial strength.
- Lock in income potential by checking a focused 224 dividend fortresses where yields start above 5% and aim to balance payouts with balance sheet resilience.
- Shield your portfolio from shocks by running through a 223 resilient stocks with low risk scores that screens for resilient businesses with lower risk scores and sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com