
Is Morgan Sindall Group (LSE:MGNS) Undervalued Following Its Record £12b Order Book?
Morgan Sindall Group (LSE:MGNS) is back in focus after reporting a record secured order book of £12b, up 39%, supported by partnership housing projects and long-term maintenance contracts that provide visibility on future work.
Morgan Sindall Group’s latest update comes after a softer share price patch, with the stock down 14.39% on a year to date share price return and a 1 year total shareholder return decline of 13.39%. Yet longer term investors have seen very strong gains, with total shareholder returns of 141.34% over three years and 116.98% over five years, suggesting that recent weakness contrasts with a powerful multi year compounding story.
Scan other construction and infrastructure plays with resilient pipelines by checking the hand picked 4 resilient stocks with low risk scores that echo Morgan Sindall Group’s focus on long term contracts and contracted revenue visibility.
After a sharp pullback yet a hefty gap to published valuation estimates, Morgan Sindall Group now trades in a wide grey zone between price and fair value. Where does that range really settle once the numbers are lined up?
Price-to-Earnings of 9.8x: Is it justified?
Morgan Sindall Group screens as inexpensive on headline metrics, with the shares at £39.68 and key valuation checks pointing to a discount compared with peers and in house fair value work.
The preferred yardstick here is the P/E ratio. That simply compares what investors are paying today for each £1 of earnings, which matters a lot for a mature, profit generating contractor where cash generation and accounting profits are already well established.
The stock trades on a P/E of 9.8x, which is described as good value against the European Construction industry average of 14.6x and a peer group average of 17.1x. The internal fair P/E estimate sits at 15.5x. The current multiple is materially lower than the level the market could move towards if sentiment and fundamentals stayed aligned with that fair value work.
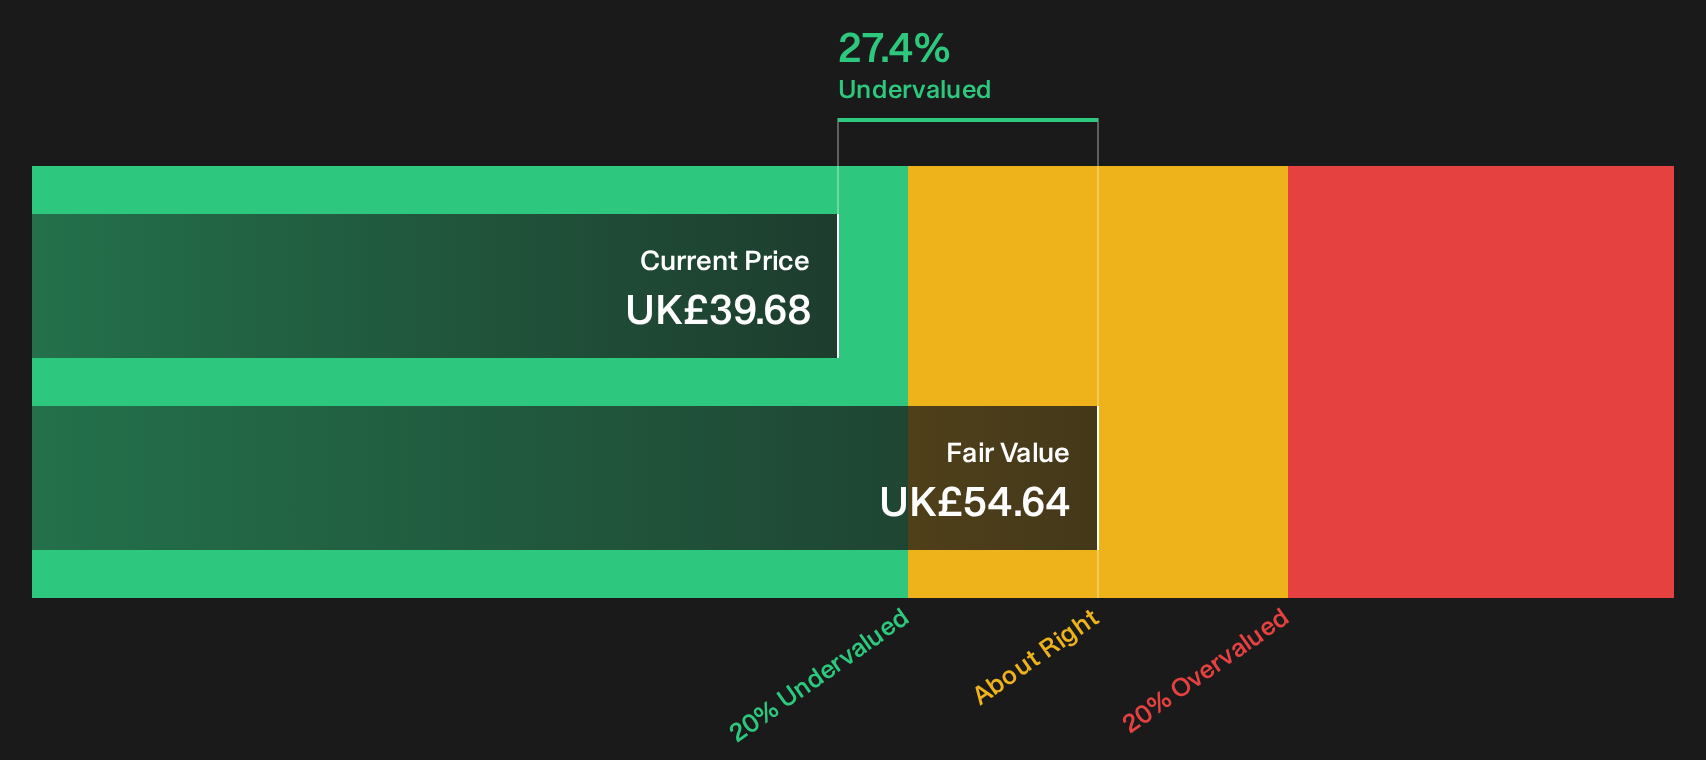
MGNS is also flagged as trading at 27.4% below the in house estimate of its fair value. At £39.68 it sits below an estimated future cash flow value of £54.64 and a price target of £56.21, although those figures rely on assumptions that investors should review in detail before relying on them.
Result: Preferred multiple of price-to-earnings of 9.8x (UNDERVALUED)
Explore the SWS fair ratio for Morgan Sindall Group.
Still, the Morgan Sindall Group story can be knocked off course if UK construction demand weakens, or if major long term public contracts are delayed or repriced.
Find out about the key risks to this Morgan Sindall Group narrative.
Another View On Morgan Sindall Group’s Value
The P/E work presents Morgan Sindall Group as cheap, and the in house SWS DCF model also points to undervaluation, with the shares at £39.68 compared with an estimated future cash flow value of £54.64. If both lenses indicate potential upside, what could investors be missing in the cash flow assumptions?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Morgan Sindall Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 10 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of risks and rewards around Morgan Sindall Group feels finely balanced, move quickly and review the detail for yourself so your stance is grounded in the numbers. Round out that view by weighing its 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Morgan Sindall Group?
If Morgan Sindall Group has sharpened your focus on quality, do not stop here. Broaden your opportunity set with targeted stock ideas shaped by clear fundamentals.
- Target resilience by scanning companies with stronger balance sheets and cleaner fundamentals using this focused list of solid balance sheet and fundamentals (10 results).
- Hunt for mispriced quality by reviewing a curated 10 high quality undervalued stocks that pairs solid cash generation with supportive valuations.
- Strengthen potential income streams by assessing companies in the 5 dividend fortresses that aim to combine higher yields with robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com