
Earnings Update Could Be A Game Changer For Atlas Copco Stock (OM:ATCO A)
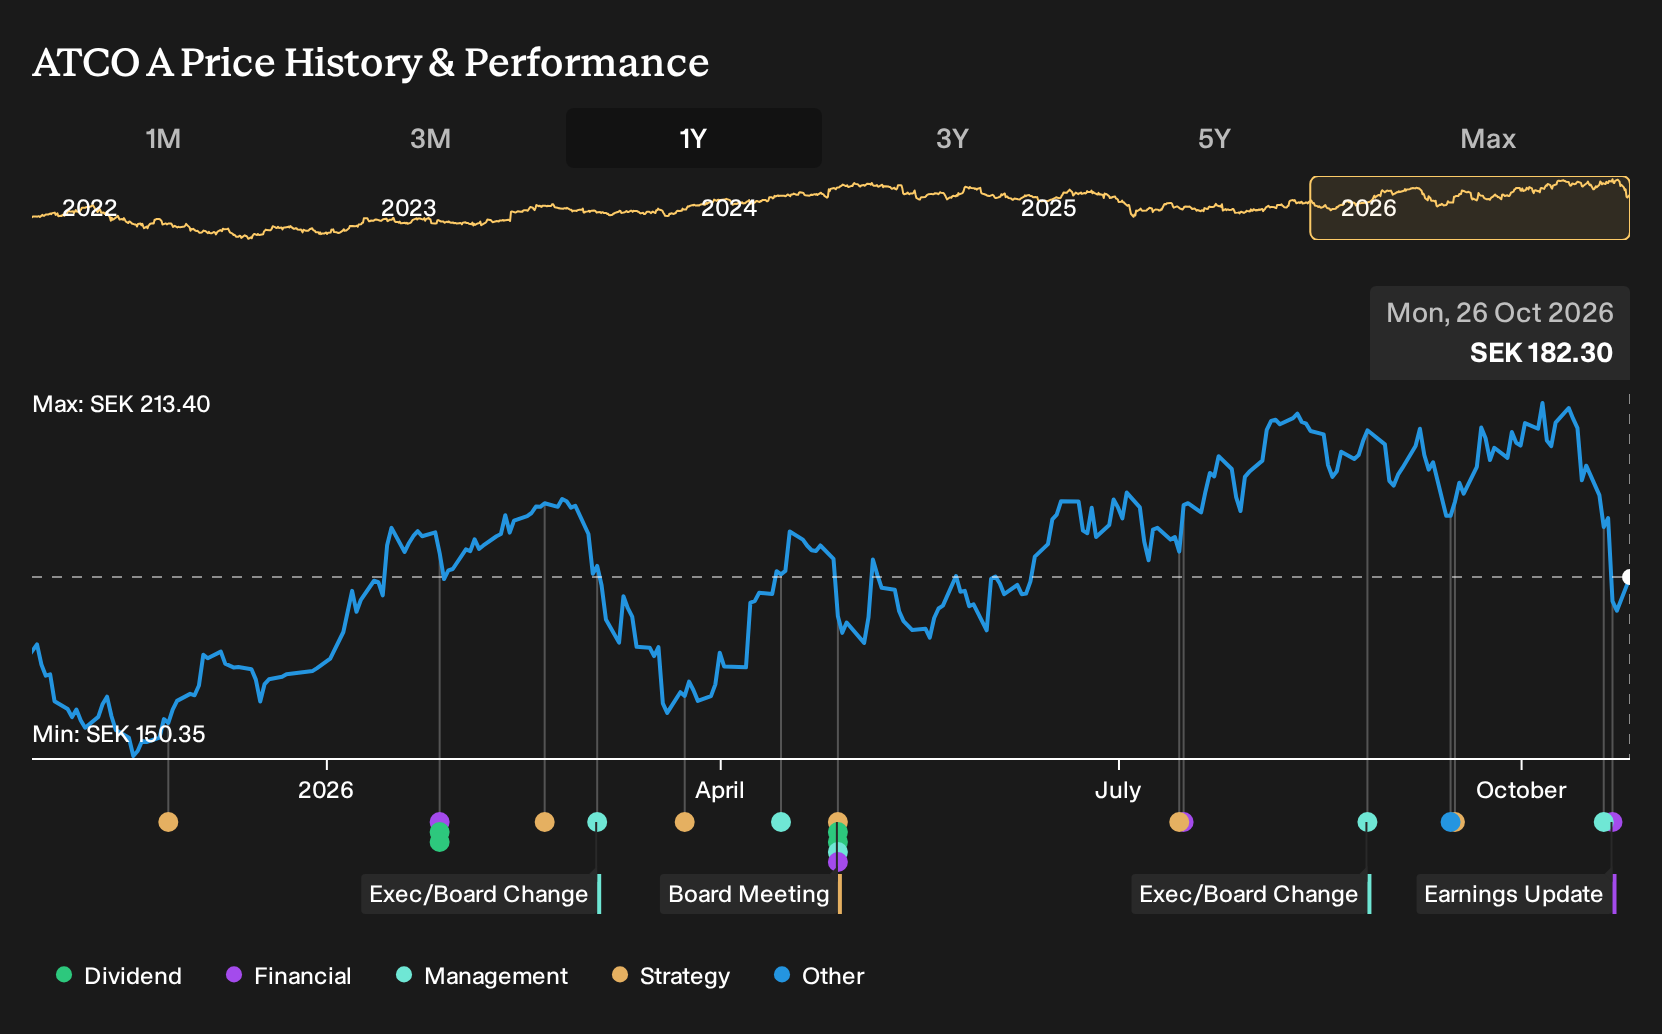
- Atlas Copco reported third quarter 2026 sales of SEK 47,920 million and net income of SEK 7,717 million, with earnings per share from continuing operations at SEK 1.58. For the first nine months of 2026, sales reached SEK 133,434 million and net income was SEK 21,035 million.
- The appointment of long serving executive Mikael Andersson to lead the Power Technique business area from January 2027 highlights internal succession planning that may matter for how Atlas Copco steers capital allocation and execution in a key profit pool.
- The next step is to examine how Atlas Copco's investment narrative aligns with this reported change in sales and profitability.
Atlas Copco Investment Narrative Recap
To own Atlas Copco, an investor needs to be comfortable with an industrial group built on compressed air, vacuum and tools, steadily converting a large installed base into higher margin service revenue. The latest report shows SEK 47,920 million in third quarter sales and SEK 7,717 million in net income, which keeps that earnings story intact rather than rewriting it.
The most important near term swing factor still sits in how well Atlas Copco manages tariff pressure, currency moves and acquisition integration costs relative to that service and semiconductor driven demand. The fresh numbers do not remove those issues, but they give little sign that the core operating thesis has been materially shaken in the short term.
The third quarter earnings release is the clearest signal for catalysts right now. Sales for the period reached SEK 47,920 million with earnings per share from continuing operations at SEK 1.58, and for the first nine months sales were SEK 133,434 million with net income of SEK 21,035 million. That is the data to set against expectations for semiconductor related orders, service activity and acquisitions.
Viewed through that lens, the report helps investors test whether Atlas Copco is converting its order book and acquisition pipeline into solid cash generation while still absorbing tariff, currency and IT or integration bills. In the short term, execution on cost control and pricing around those headwinds remains a key risk, and the earnings print provides a clearer scoreboard for tracking it.
Atlas Copco's current earnings are SEK 26.6b, with analysts forecasting SEK 42.9b of earnings on SEK 240.6b of revenue by 2029, which implies 12.3% yearly revenue growth and an earnings increase of SEK 16.3b from today.
Uncover why Atlas Copco's fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view around Atlas Copco leans heavily on semiconductor demand as a potential accelerator. The most optimistic analysts were working off revenue forecasts of SEK 259.9b and earnings of SEK 46.8b by 2029 before this earnings and management news. You can treat that as a much richer story that may be revised as these fresh numbers sink in.
Explore 3 other Atlas Copco fair value estimates, including one that suggests as much as 27% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Atlas Copco research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Atlas Copco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlas Copco's overall financial health at a glance.
Looking for more investment ideas beyond Atlas Copco?
If Atlas Copco is already on your watchlist, it can help to set it in context by scanning a wider field of opportunities using the Simply Wall St Screener. You get a quick way to compare quality, balance sheet strength and potential upside across hundreds of stocks without needing to build your own spreadsheets.
- If you value steadier profiles and want to dial down risk, take a look at 223 resilient stocks with low risk scores that could help you spot companies with more resilient characteristics.
- For investors who care most about financial strength, use the list of solid balance sheet and fundamentals (207 results) to focus on businesses with sturdier balance sheets and underlying fundamentals.
- If you are hunting for opportunities that the broader market may be overlooking, the 610 high quality undiscovered gems could surface under the radar stocks with stronger quality signals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com