
Rheinmetall (XTRA:RHM) Teams Up With Nel ASA, Is The Upside Already Priced In?
Rheinmetall (XTRA:RHM) just signed a Memorandum of Understanding with Nel ASA to explore decentralised production of low carbon synthetic fuels, targeting defence and critical infrastructure energy security through modular, hydrogen based systems.
Rheinmetall’s share price has been volatile, with a 5.27% 1 month share price return followed by a 4.84% decline over 90 days and a 35.44% drop year to date. Over longer periods, the 3 year total shareholder return is almost 3x and the 5 year total shareholder return is around 12x, which points to long term momentum but fading near term enthusiasm as investors reassess growth prospects and risks around new projects like the Nel ASA collaboration.
Compare Rheinmetall’s fuel security angle with other defence and infrastructure plays by scanning our hand picked 42 power grid technology and infrastructure stocks that could benefit from similar energy resilience themes.
After a near 35% year-to-date slide in Rheinmetall, despite multi-year total returns that are still several times higher, the real puzzle now is whether the meaningful upside has already played out or if the market is underpricing the next leg.
Most Popular Narrative: 82% Undervalued
Rheinmetall last closed at €1,034.20, while the most followed narrative on Simply Wall St assigns a fair value of €5,865. According to user Baranclever, that gap only makes sense if execution, capital intensity and future valuation multiples all become real headwinds.
Rheinmetall can become significantly more profitable between 2027 and 2029 while the share price delivers a much smaller return if the P/E multiple normalizes.
The key question is no longer whether Rheinmetall can grow, but whether its earnings growth will be strong enough to justify the valuation currently assigned to the company.
See why 24 investors see Rheinmetall as 82% undervalued.
Result: Fair Value of €5,865 (UNDERVALUED)
Still, execution missteps on Rheinmetall’s €80.5b backlog or weaker free cash flow while capital spending remains high could quickly puncture that undervaluation narrative.
Find out about the key risks to this Rheinmetall narrative.
Another View: Rheinmetall Through The P/E Lens
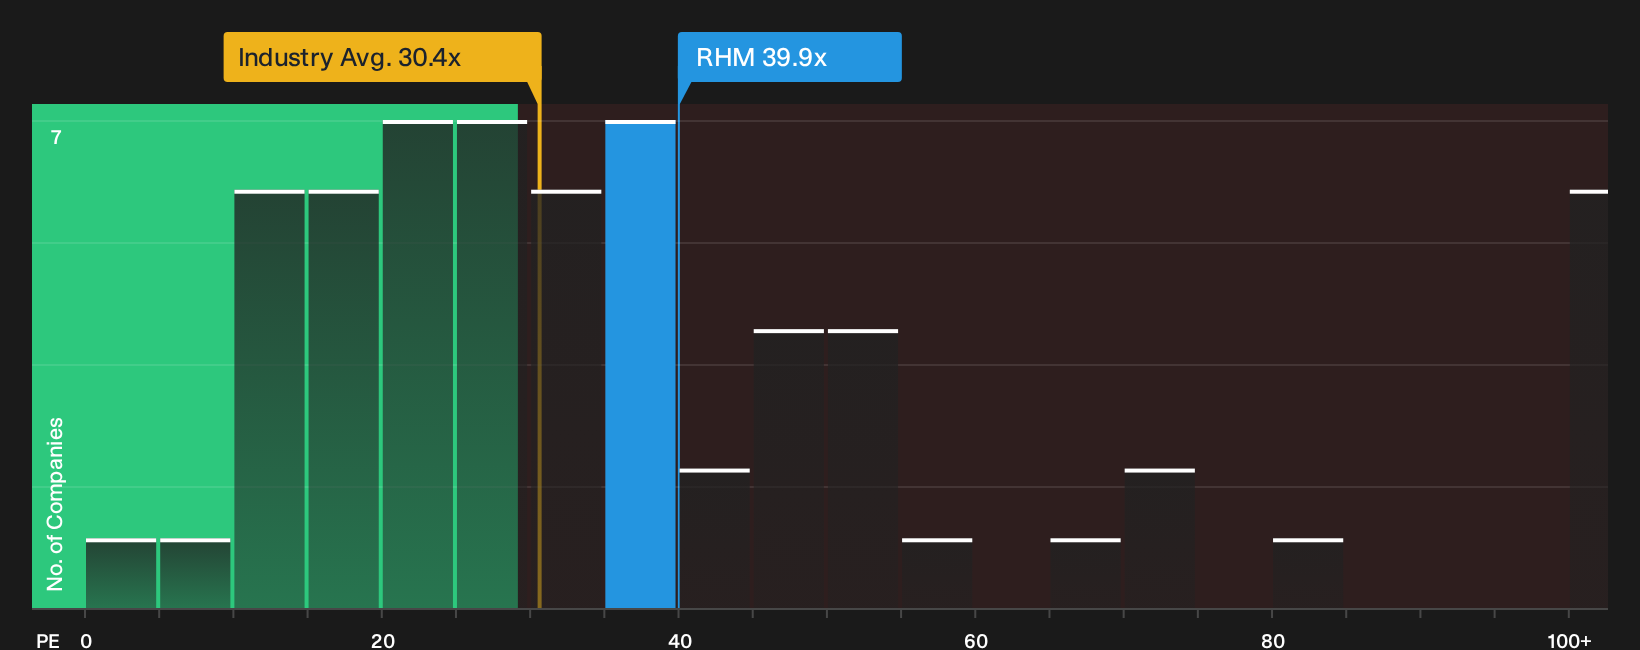
That €5,865 fair value hinges on long term earnings and multiples. The current 39.9x P/E tells a different story. It is richer than the European Aerospace & Defense average on 30.4x, yet below peers on 69x and under the 45.2x fair ratio that the market could move towards.
If sentiment drifts closer to the sector on 30.4x, today’s valuation could look demanding. If pricing instead leans toward the 45.2x fair ratio or the 69x peer level, the recent share price slide may look more like a reset than an endgame. Which direction do you think dominates next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Rheinmetall leave you on the fence, move quickly from headline impressions to your own view by using the detailed breakdown of 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Rheinmetall?
If Rheinmetall has sharpened your focus on risk, reward and valuation discipline, do not stop here. Broaden your watchlist with targeted screens that surface very different types of opportunities.
- Target potential bargains early by reviewing the 195 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Strengthen the defensive side of your portfolio by using the 224 dividend fortresses to zero in on higher yielding payouts supported by underlying business cash flows.
- Protect against nasty balance sheet surprises by filtering with the list of solid balance sheet and fundamentals (207 results) so you focus on companies with more resilient finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com