
Is Ringkjøbing Landbobank (CPSE:RILBA) Fairly Valued On Raised 2026 Guidance?
Ringkjøbing Landbobank (CPSE:RILBA) just raised its 2026 earnings guidance, now pointing to net profit toward the upper end of DKK 2.2b to 2.5b, backed by updated nine month results.
The guidance upgrade comes amid a mixed price picture. The share price is at DKK1,703.0 after a 1-day share price return of 1.67%. It is down 7.24% over 30 days and slightly lower over 90 days, while the year-to-date share price return of 10.30% and 1-year total shareholder return of 19.49% indicate that longer term momentum for Ringkjøbing Landbobank has been stronger than the recent pullback suggests.
Scan how Ringkjøbing Landbobank compares with other Nordic financials by reviewing a curated set of resilient bank stocks in the 223 resilient stocks with low risk scores.
Guidance is higher, the share price has cooled, and Ringkjøbing Landbobank trades at a reported discount to some value estimates. Does that make buying today more appealing than waiting for a cheaper entry later?
Preferred P/E of 16.9x: Is it justified?
On simple multiples, Ringkjøbing Landbobank carries a P/E of 16.9x, which is higher than several reference points even though the DKK1,703 share price trades at a reported discount to some fair value estimates.
The P/E ratio compares the current share price with earnings per share and, for a bank like Ringkjøbing Landbobank, it is a quick way to see how much investors are paying for each unit of profit. A richer multiple can reflect expectations for steadier earnings growth, the 7.9% forecast annual profit increase, high quality earnings, or the 55.5% net profit margin.
RILBA is described as expensive on a P/E basis compared with its own estimated fair P/E of 15.9x and also versus peers. The 16.9x P/E is above the peer average of 12.5x and above the wider European Banks industry average of 11.5x. This represents a meaningful premium that the market could eventually re-rate closer to the fair ratio level if sentiment or growth expectations shift.
Explore the SWS fair ratio for Ringkjøbing Landbobank.
Result: Price-to-earnings of 16.9x (OVERVALUED)
Still, if earnings projections or Danish credit conditions soften, Ringkjøbing Landbobank’s premium P/E and recent share price gains could come under pressure.
Find out about the key risks to this Ringkjøbing Landbobank narrative.
Another View: SWS DCF Points To Undervaluation
The P/E workup paints Ringkjøbing Landbobank as expensive, yet the SWS DCF model suggests the opposite. In that framework, the shares at DKK1,703 are compared with an estimated future cash flow value of DKK2,738.86, which implies a wide gap that could matter for long term holders.
Look into how the SWS DCF model arrives at its fair value.
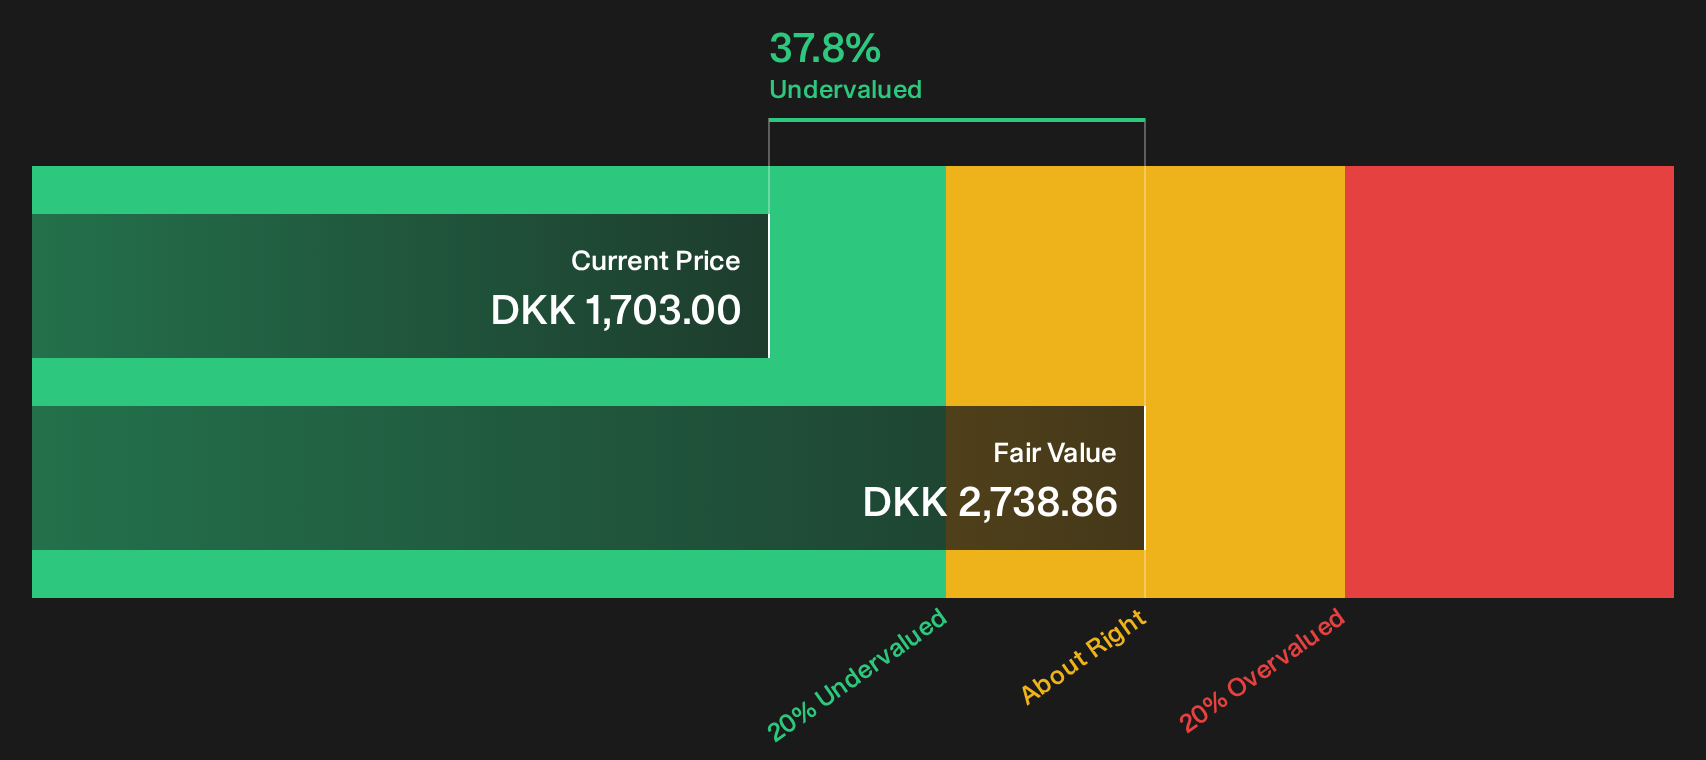
If one method flags a premium and the other signals a discount, which lens do you want to lean on when sizing a position in Ringkjøbing Landbobank?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ringkjøbing Landbobank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Ringkjøbing Landbobank leave you split, step into the data yourself and stress test your own thesis. To understand why some investors are still optimistic about its strengths, start with the 3 key rewards.
Looking for more investment ideas beyond Ringkjøbing Landbobank?
Do not stop with Ringkjøbing Landbobank. Put the same scrutiny to work across fresh ideas so your watchlist keeps evolving instead of drifting behind the market.
- Target potential mispricing by scanning a curated set of quality stocks that look cheap on fundamentals through the 195 high quality undervalued stocks.
- Strengthen your income stream by checking companies with robust payouts and yields in the 224 dividend fortresses.
- Raise the bar on financial resilience by filtering for businesses with strong balance sheets in the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com