
What Lennar Investors Missed Before The Fall
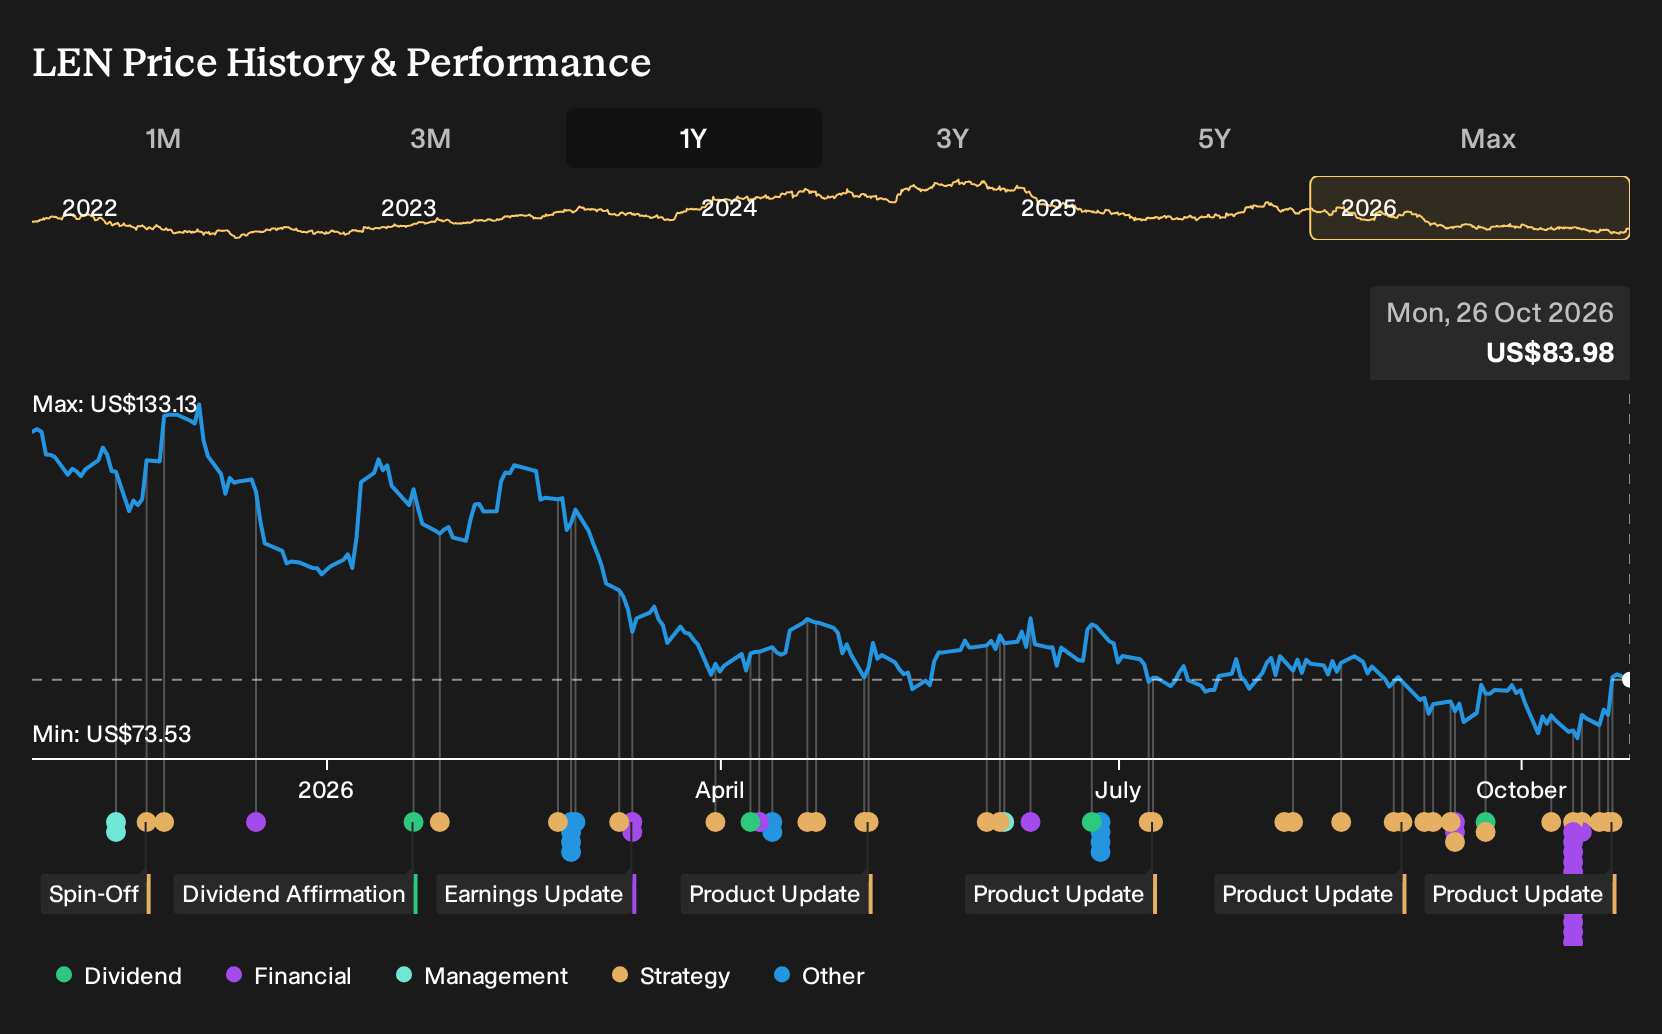
If you had looked at Lennar in late October 2025, with housing affordability in the headlines and analysts split between cautious and optimistic outlooks, it might have felt easier to sit on the sidelines. For Lennar shareholders, the loss over the past year was 33.3%, including dividends. Given what was already on record then about high mortgage rates, softer orders and margin pressure, which early warning would you have focused on before making a call?
The easy part of this move is behind Lennar. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Argument Investors In Lennar Had To Weigh
The shares cost US$128 at the start of the period, so every Lennar decision began with the same simple question. Was that too low, too high, or roughly fair given the housing backdrop?
The bullish narrative put Fair Value at US$169. This price was implied by forecasts of 7.0% annual revenue growth, a 10.0% profit margin and a future P/E of 11.6x over a 3 year window.
The bearish view pointed to a Fair Value of US$95, built on assumptions that housing demand would stay constrained and that profit margins could compress toward 5.5%.
What The Results Changed In The Lennar Debate
The clearest test of the Lennar thesis came from Q3 2026, when revenue fell from US$8.81b to US$8.05b and net income dropped from US$585.7m to US$282.0m. Net margin moved from 6.6% to 3.5%, which leaned toward the cautious case that warned about earnings pressure in a high-rate housing market.
The episode turned on one simple assumption: that Lennar could protect profitability while using incentives and an asset-light land strategy. For any builder, you would now watch reported net margin and the level of sales incentives together to see whether that trade off is holding.
What Lennar's Lower Price Now Asks You To Believe
Lennar trades today at US$83.98, after the share price fell about 33.3% over the past year. The selected Narrative places its Fair Value above that level, reflecting a view that the asset light model and efficiency push are not fully reflected in the current valuation.
The crux is whether faster build times, standardized product and land banking structures can outweigh affordability pressure, resale competition and option costs. For the fall to look like an opening rather than a warning, a buyer would need confidence that these efficiency gains translate into steadier margins and cash generation.
"The current valuation implies that the market is pricing Lennar as if land banking costs, housing affordability pressures, and resale competition will continue to weigh on margins more heavily than the asset light model and efficiency gains will support them."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 32% below our estimate - turns shorter brownfield tiebacks and bundled iEPCI contracts into extended subsea development programs.
- Company 2 - 48% below our estimate - converts a technology heavy project backlog into high-capacity data center and modular build deployments.
- Company 3 - 37% below our estimate - wins multidisciplinary consulting mandates where AI complexity meets tightening regulatory and compliance needs.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com