
Enerflex (TSX:EFX) Climbed Today, What Is Behind The Latest Attention?
Enerflex (TSX:EFX) just landed a sizeable Engineered Systems contract tied to a large North American data center, pushing its low emission behind the meter power generation backlog above 1.75 gigawatts.
For Enerflex, the new data center deal lands after a strong run, with the share price delivering a 50.25% year to date return and the 1 year total shareholder return reaching 85.38%, while the 3 year total shareholder return is very large at over 6x.
Scan how Enerflex fits into the broader low emission energy build out by reviewing a curated list of 42 power grid technology and infrastructure stocks that are helping power data centers and digital infrastructure.
After a move like Enerflex has just posted and with the shares trading at a sizeable discount to published fair value estimates, how wide is the gap between price and what the business may be worth?
Most Popular Narrative: 34% Undervalued
On the most followed view of Enerflex, a fair value of CA$50.06 compares to the last close at CA$32.83. This frames a wide valuation gap built on specific growth and margin assumptions rather than sentiment alone.
Modernization and buildout of global energy infrastructure, including multi-decade upgrades in emerging markets, is reflected in the company's $1.2 billion backlog and robust BOOM projects internationally. This indicates continued top-line revenue expansion and geographic diversification.
Increased regulatory and customer focus on emissions reductions and produced water management is driving demand for Enerflex's technology and services, seen in the performance and expansion of produced water projects in Oman. This should underpin margin strength and potentially grow average project value.
See why 8 investors see Enerflex as 34% undervalued.
Result: Fair Value of CA$50.06 (UNDERVALUED)
Still, if data center orders slow or leadership changes take longer to settle, the Enerflex narrative around recurring power projects could look far less secure.
Find out about the key risks to this Enerflex narrative.
Another View: Enerflex On Earnings Multiples
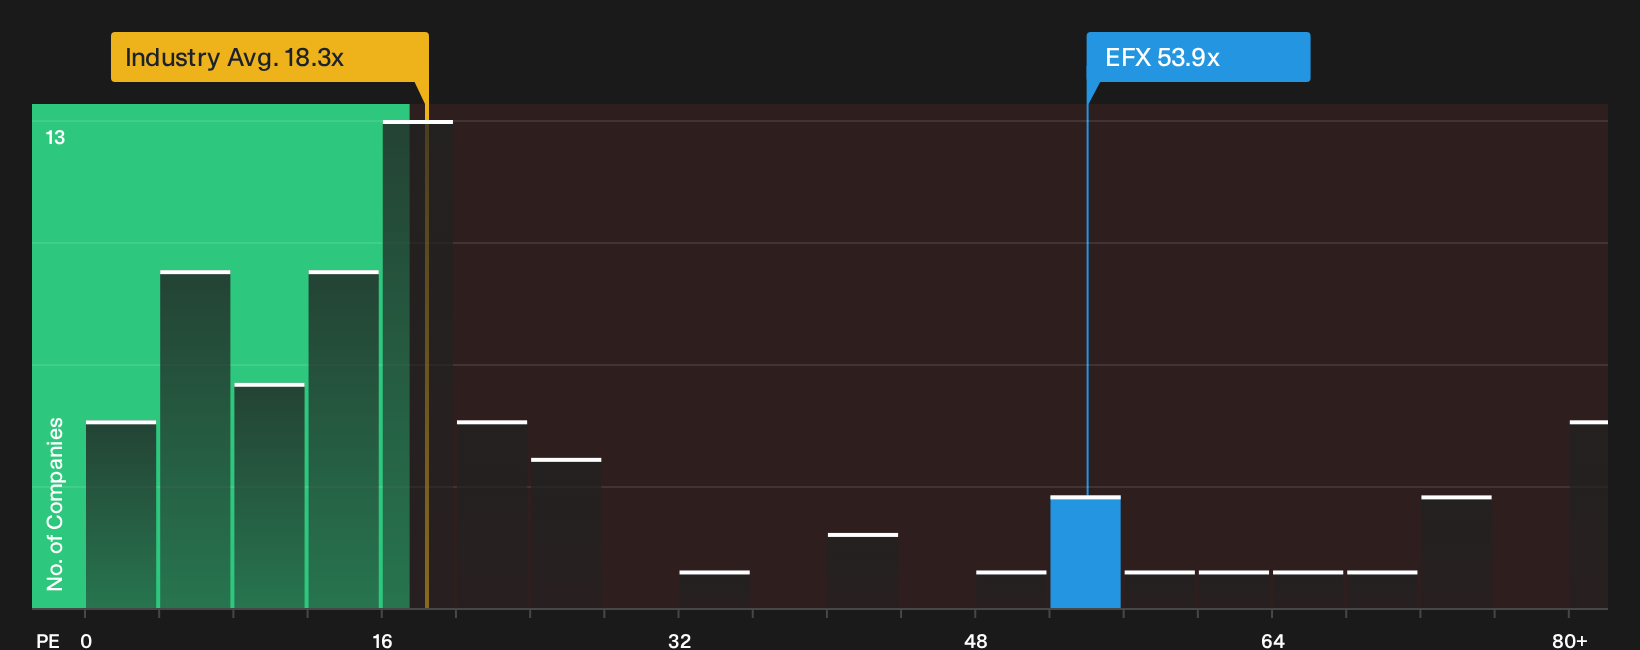
On a simple earnings lens, Enerflex looks far less forgiving. The shares trade on a P/E of 53.9x, while the North American Energy Services industry sits at 18.4x and the fair ratio for the stock is 21.3x. That gap points to valuation risk if expectations cool. Where does that leave you on the story versus the sticker price?
For a closer look at how current pricing compares with earnings power and peers, review the valuation breakdown in detail, then weigh whether the market could move toward that fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by Enerflex's surge and the mixed signals on valuation? Move quickly to test the data yourself, weigh both sides, and review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Enerflex?
If Enerflex has sharpened your focus, do not stop here. Broader context across other opportunities can help you judge risk, return potential, and portfolio fit.
- Target resilient compounding potential by scanning a curated 3 high quality undervalued stocks list that blends quality metrics with pricing that may not fully reflect business fundamentals.
- Prioritize stability and income by reviewing a hand picked set of 3 dividend fortresses that combine higher yields with a focus on durability.
- Protect your downside by filtering through a 8 resilient stocks with low risk scores universe built around stronger balance sheets and more conservative risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com