
UK Stock Market Today: FTSE 100 Futures Edge Higher On Strong PMI And Budget Risks
The Morning Bull - UK Market Morning Update Tuesday, 27 Oct 2026
UK stocks are set for a cautiously positive open, with sentiment driven mainly by a clean upside surprise in domestic activity data. The latest purchasing manager surveys point to the UK economy carrying more momentum into year end than many assumed.
October’s UK composite PMI printed at 53.1, an 8 month high, with both services at 53.1 and manufacturing at 52.8. Readings above 50 indicate expansion, so this cluster of figures signals broad based private sector growth, even as input costs edge higher.
Stronger PMIs usually give the Bank of England less reason to relax. Firmer demand can keep wage and pricing pressure alive, which supports higher for longer borrowing costs and tight financing conditions for rate sensitive areas such as construction and smaller domestic businesses.
The live question now is how this growth pulse feeds into the UK Autumn Budget. Any shift in fiscal stance that leans toward extra spending or tax cuts could collide with this stronger data and reshape the interest rate debate again.
Stocks to Watch Before the Opening Bell
Ithaca Energy (ITH)
The UK government is weighing whether to approve the £8.7b Rosebank oilfield, which could supply about 69,000 barrels per day at peak, roughly 10% of UK output. Ithaca Energy holds 20% of the project and has signalled it may halt UK investment if approval is refused. Watch for any decision or fresh commentary from ministers.
Barclays (BARC)
Rosen Law Firm has started investigating potential securities claims tied to Barclays exposure to collapsed mortgage provider Market Financial Solutions. The law firm is preparing a class action aimed at recovering investor losses. The focus now is how large any associated charges might be and whether Barclays issues further information on its total exposure.
Melrose Industries (MRO)
Reports of a substantial increase in UK defence spending ahead of the Autumn Budget have helped lift defence related stocks, including Melrose Industries. Investors are reacting to suggestions the Chancellor could borrow billions for military funding through public finance bodies. Any confirmation of specific procurement or investment priorities will matter for Melrose’s aerospace focused operations.
Top Movers
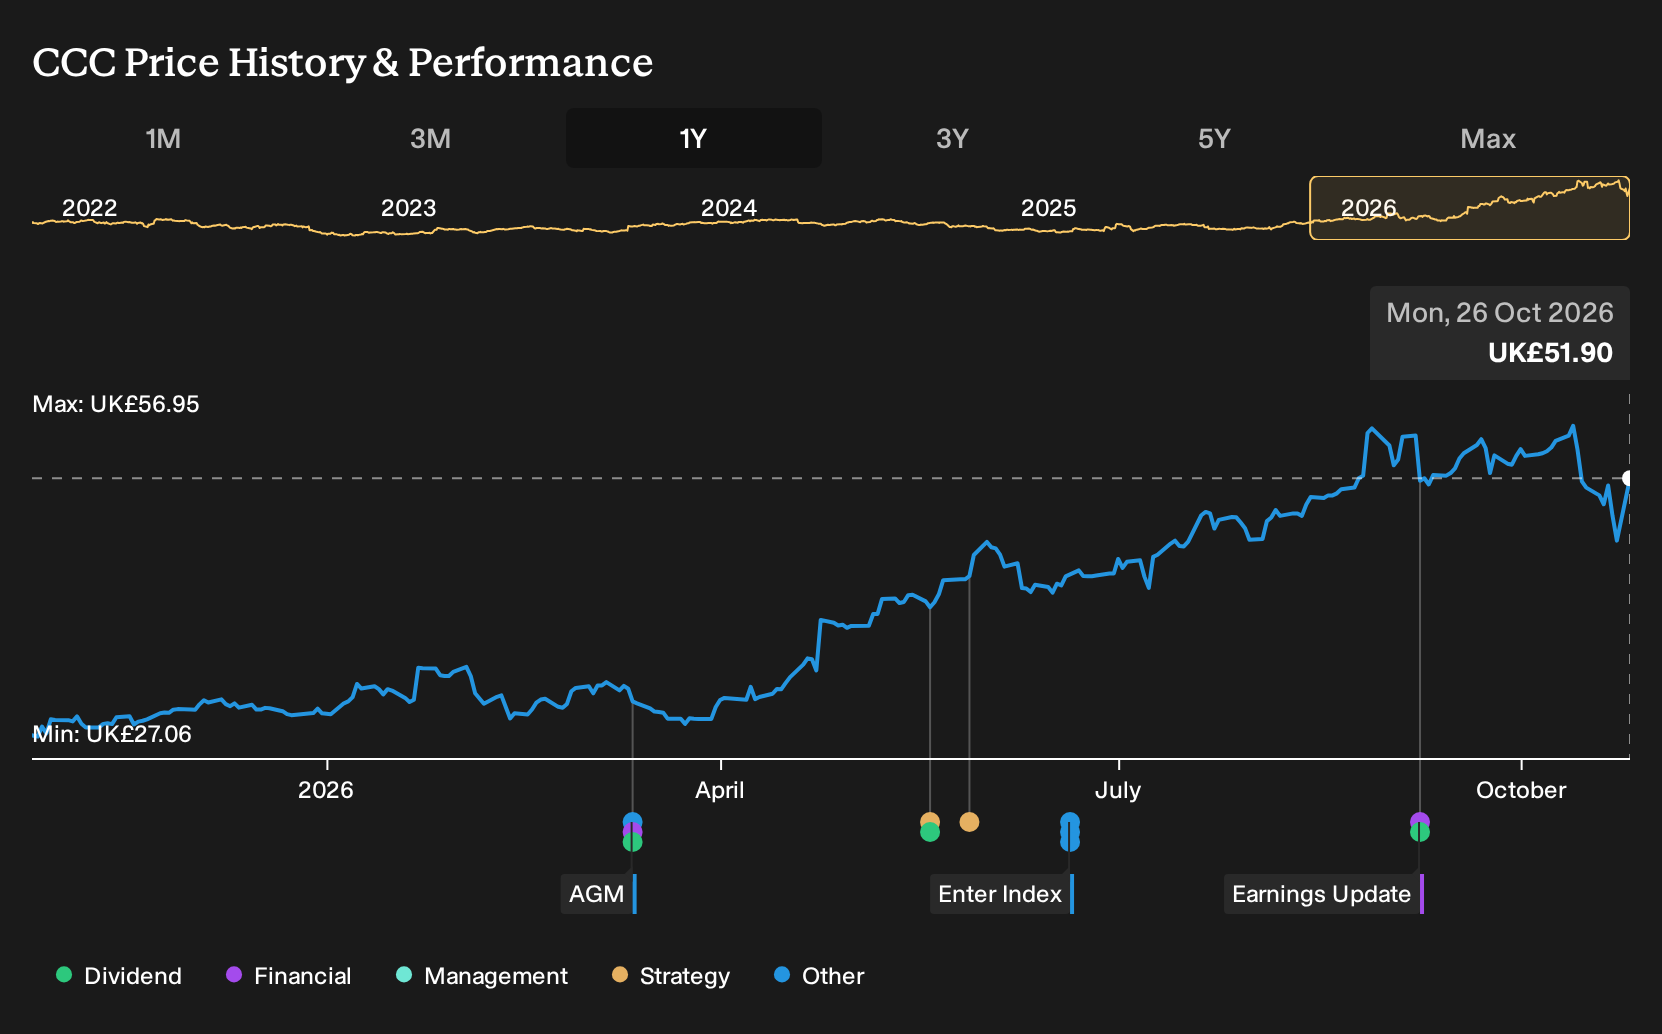
- Computacenter (LSE:CCC) jumped 13.07% after raising 2026 profit guidance and highlighting a record AI driven order backlog.
- Man Group (LSE:EMG) climbed 6.63% after expanding its Meiji Yasuda partnership with a planned $1.25b private credit commitment.
- Babcock International Group (LSE:BAB) advanced 6.39% as investors focused on broader strength in UK industrials and defence related stocks.
Top Losers
- Trustpilot Group (LSE:TRST) declined 5.59% after traders reacted to the scheduled date for its 2026 results announcement.
- Seplat Energy (LSE:SEPL) declined 2.84%.
- Canal+ (LSE:CAN) declined 2.80%.

On The Radar
UK housing and banking data collide with a packed late week of FTSE 100 earnings, while central bank decisions in the US and euro area sit in the background for sterling and rates.
- HSBC Holdings Tue 27 Oct. Q3 2026 results land as UK PMIs sit in expansion territory, so commentary on loan demand, deposit pricing and credit quality in the UK franchise gives you a cleaner feel for how higher borrowing costs are feeding through.
- Standard Chartered Wed 28 Oct. The Q3 2026 update at 4:00 AM UTC focuses attention on income trends across Asia and the Middle East and what that means for fee and trading lines that matter for London listed bank sentiment.
- Lloyds Banking Group Thu 29 Oct. Q3 2026 figures at 7:00 AM UTC put UK mortgage margins and arrears in focus, since any pressure here feeds directly into how investors think about domestic rate sensitive stocks after the strong October PMIs.
- Shell Thu 29 Oct. Q3 2026 earnings arrive with Brent pricing and global fuel demand under scrutiny, so capital allocation, upstream cash flow and any comments on UK tax or investment plans feed into broader FTSE energy sector positioning.
- NatWest Group Fri 30 Oct. Q3 2026 numbers at 7:00 AM UTC, alongside AstraZeneca and BP results and UK consumer credit and mortgage approvals for September, line up as a busy pre Autumn Budget checkpoint for lenders, pharma and energy heavyweights in the UK market.
Sector & Industry Watch
Energy: Politics press on North Sea plans
Energy has gained over the past week, helped by firmer UK activity data and a positive 7 day sector return. At the same time, sentiment is split, with Ithaca Energy warning it could rethink UK spending if the £8.7b Rosebank oilfield is rejected while Jersey Oil and Gas has fresh approval at Jackdaw in its corner.
The sector’s near term tone is highly sensitive to Autumn Budget hints on North Sea taxes and project approvals, because those decisions directly shape cash flows, investment appetite and dividends for UK listed producers.
Real Estate: Gentle rebound, funding still in focus
Real Estate has moved higher over seven days and over the past month, outpacing the broadly flat GB Market over the week. Behind that, Grit Real Estate is lining up asset disposals to shore up its finances, while Dar Global is talking about new high end projects and a Dubai focused fund.
If you hold REITs or housebuilders, the key check point is Thursday’s Bank of England figures on mortgage approvals and wider consumer credit, which give a cleaner read on how higher interest costs are feeding through to housing demand and landlord balance sheets.
Materials: Miners pull back despite better PMIs
Materials and Metals and Mining have both fallen sharply over the past week and past month, even though UK manufacturing PMI is in expansion territory. Larger groups such as Rio Tinto and Anglo American have seen mixed trading, while juniors like Pensana and Atlantic Lithium are pressing on with funding and project deals.
For anyone with mining exposure, the external data point that matters next is Thursday’s US durable goods orders report, since demand for heavy machinery often shapes expectations for future metals use and can sway sentiment toward commodity producers in London.
Financials: Banks cool as Budget risk builds
Financials have softened modestly over the last week after a stronger year to date, with Banks seeing a steeper pullback over seven days and over the month. Headlines range from class action scrutiny at Barclays to upbeat partnership news at Man Group and improved guidance at Bridgepoint, which shows how uneven this area can be.
The sector’s big catalyst now is this week’s UK bank reporting run from HSBC and Standard Chartered, because comments on loan demand, deposit pricing and any sight of the bank surcharge in Budget chatter will influence how investors think about UK lenders’ earnings power.
Tech: Profit upgrades but chip swings bite
Tech has slipped slightly over seven days after a strong year, while Semiconductors have given back a very large chunk of earlier gains over the month. Computacenter just raised its 2026 profit guidance on the back of a record £12.6b AI focused order backlog, and Kainos and Catenai reported supportive contract and customer news.
If you own UK technology funds, the trend to track is company guidance following the current US Big Tech earnings season, since any shift in corporate AI hardware and cloud spending plans tends to ripple straight into demand for UK IT services providers and chip exposed businesses.
Identify The Next Market Leaders
With UK banks softening as Budget risk builds and several major lenders reporting this week, you can stress test your own holdings against this list of 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com