
Is Norwegian Cruise Line Holdings (NCLH) Cheap As Softer Q3 Expectations Pressure Valuation?
Norwegian Cruise Line Holdings (NCLH) heads into its upcoming Q3 report with expectations for softer results, as forecasts point to year-over-year declines in earnings per share, revenue, passenger ticket revenue, and occupancy.
Norwegian Cruise Line Holdings' share price has slipped over the past few months, despite a recent 1-month share price return of 4.38%. The 90-day share price return is down 28.13% and the 1-year total shareholder return has fallen 35.13%, which signals fading momentum as the market reassesses both recovery prospects and risk around earnings softness.
Spot under-pressure travel plays like Norwegian Cruise Line Holdings and compare them with a curated group of resilient consumer stocks in the 30 resilient stocks with low risk scores.The question now is simple. After Norwegian Cruise Line Holdings' sharp drawdown and modest recent bounce, does the current price still compensate you for softer earnings expectations, or has the easy part of the risk reward already played out?
Most Popular Narrative: 22% Undervalued
Norwegian Cruise Line Holdings last closed at $15.25, while the most followed narrative anchors fair value at $19.44. That gap frames the turnaround story investors are weighing against softer near term earnings expectations.
Measured fleet renewal that retires older ships, adds higher earning vessels and moderates capacity growth after 2027 is set to reduce growth capex by about $1b annually from 2028. This can free up cash flow that supports deleveraging and, over time, net margin and earnings quality.
See why 54 investors see Norwegian Cruise Line Holdings as 22% undervalued.
Result: Fair Value of $19.44 (UNDERVALUED)
Still, high leverage, with net debt expected above 6x, and ongoing yield pressure at the Norwegian brand could drag on the turnaround that underpins this undervalued story.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View: SWS DCF Model Paints A Harsher Picture
The market signal for Norwegian Cruise Line Holdings looks very different when you swap the narrative fair value for the SWS DCF model. On this framework, NCLH at $15.25 trades well above an estimated future cash flow value of $3.78, which points to an overvalued stock rather than a bargain.
The gap between a $19.44 narrative fair value and a $3.78 cash flow estimate raises a practical question for investors: Which set of assumptions about future cash generation feels more realistic for your own portfolio?
Look into how the SWS DCF model arrives at its fair value.
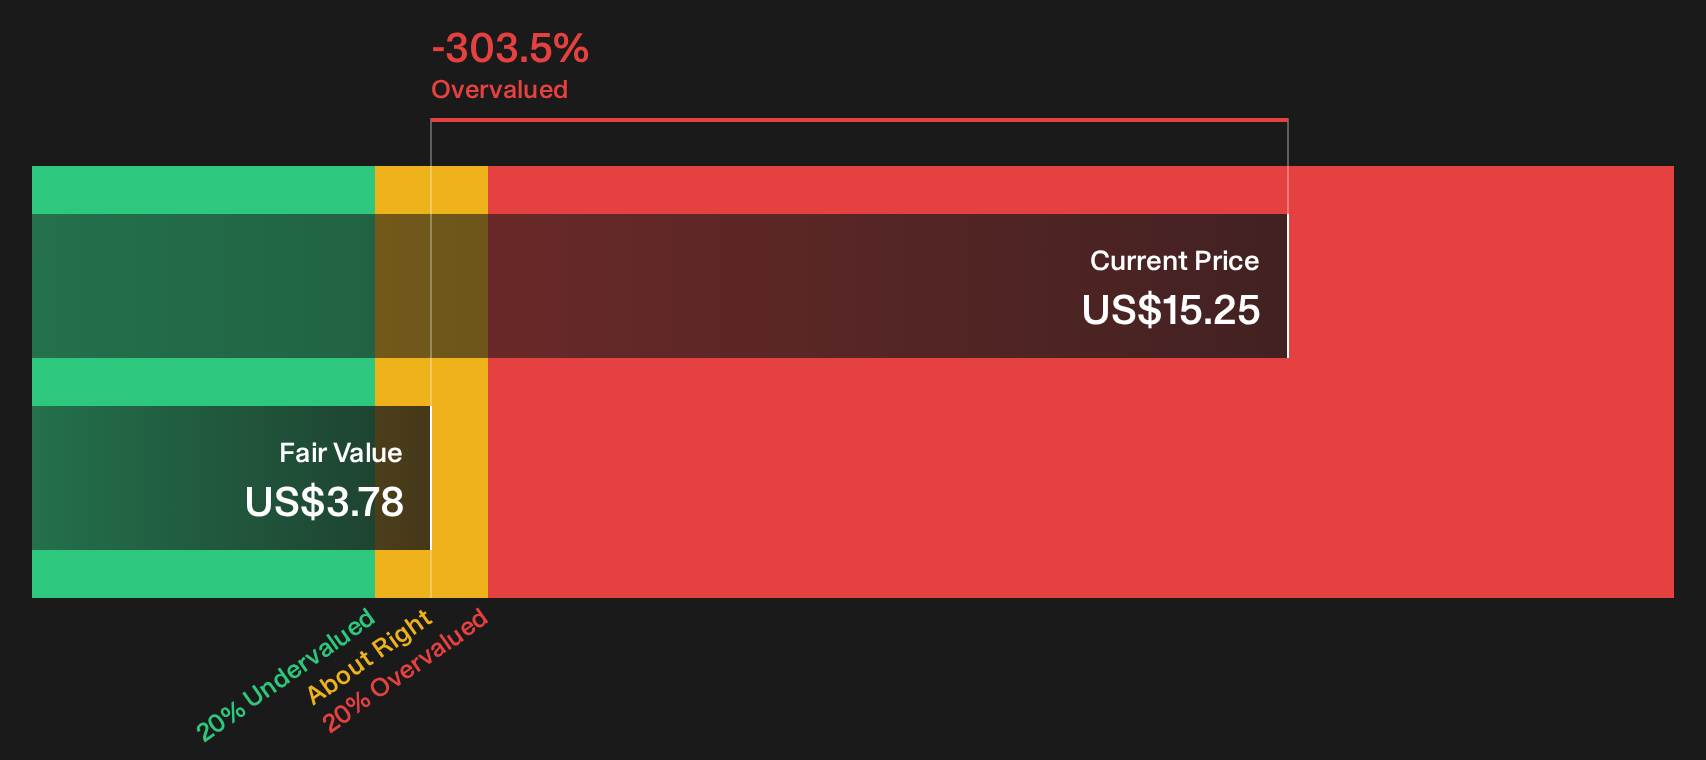
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Norwegian Cruise Line Holdings so far. If you want to move quickly and form your own view, start with the balance of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Norwegian Cruise Line Holdings?
If Norwegian Cruise Line Holdings has you rethinking risk, do not stop there. Put that curiosity to work by scanning other opportunities that better match your comfort zone.
- Target steadier compounding by focusing on durable balance sheets and consistent fundamentals through a curated list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by comparing Norwegian Cruise Line Holdings with a focused pool of 29 high quality undervalued stocks that may offer a different risk profile.
- Build a cash flow focused plan by lining up potential income ideas from a hand picked group of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com