
Elite Indian Growth Stocks For October 2026
Artificial intelligence stocks on Wall Street have been grabbing attention, and Asian markets have reacted with gains as investors focus on companies tied to that theme. Indian high growth businesses with management heavily invested in their own shares tap into a similar story investors are watching closely. This article walks through three fast growing Indian stocks with high insider ownership from our screener that fit this moment.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management is heavily invested alongside shareholders. However, if you want the absolute best, these 40 high growth high conviction stocks are the cream of the crop.
Rubicon Research (NSEI:RUBICON)
Rubicon Research is a specialty pharmaceutical player that leans into the screener’s theme through niche, higher value drug formulations built on its RubiReten and RubiSRL platforms. This gives investors a focused way to gain exposure to differentiated therapies.
Rubicon Research generates ₹19,358 million from pharmaceutical products, including generics, specialty drugs, APIs and related services. This reflects a concentrated model around complex formulations. The stock carries a market value of about ₹246.7 billion.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
What really matters next is how a single pressure on the product mix and pricing power shapes the durability of those improving margins.
To see how that pressure could either cap or accelerate Rubicon Research over the next phase, read the full narrative for Rubicon Research for the full pricing and margin story.

Tonbo Imaging India (NSEI:TONBO)
Tonbo Imaging India builds electro-optical and infrared systems for defense, surveillance, and security buyers worldwide, with the fast growing tactical thermal imaging and weapon-sight line aligning it with the screener’s high growth theme. It generated ₹3,279 million from vision technology products and carries a market value of about ₹69.5b.
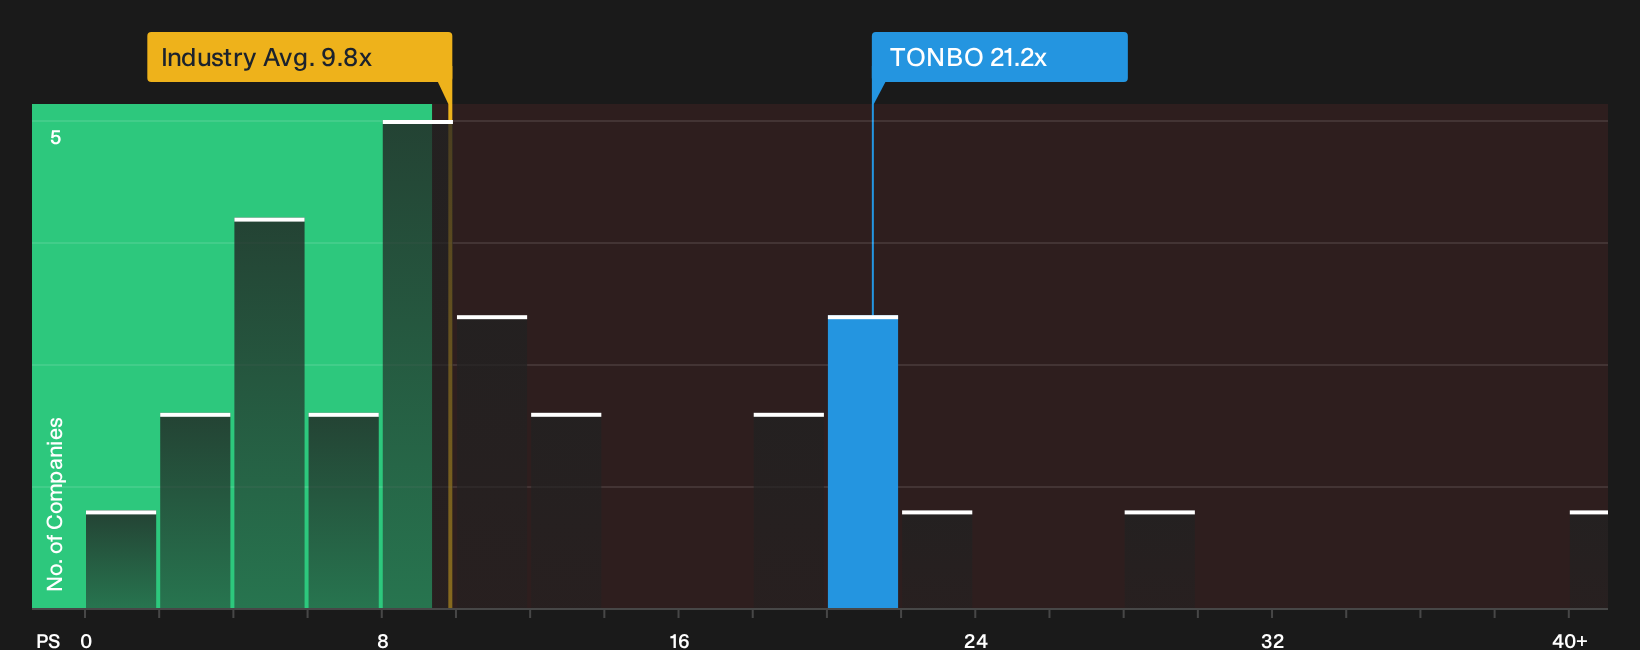
Tonbo Imaging India fits the screener’s pitch. Analysts expect revenue to rise 33.3% a year and earnings to advance 53.7% annually, while the stock trades on a relatively high 21.2x P/S and has seen margins narrow. A single shift in pricing power or contract mix could have a significant effect on how that growth translates into shareholder outcomes.
That contract mix question is exactly what the analysis report for Tonbo Imaging India unpacks, examining how Tonbo Imaging India’s pricing power and margin path could decouple from headline growth.
Bajel Projects (NSEI:BAJEL)
Bajel Projects runs EPC contracts for extra high voltage transmission and distribution infrastructure, a direct fit with the fast growing, high insider ownership theme through large, long duration power projects. It generated ₹27,508 million from power transmission and distribution and has a market value of about ₹18.1b.
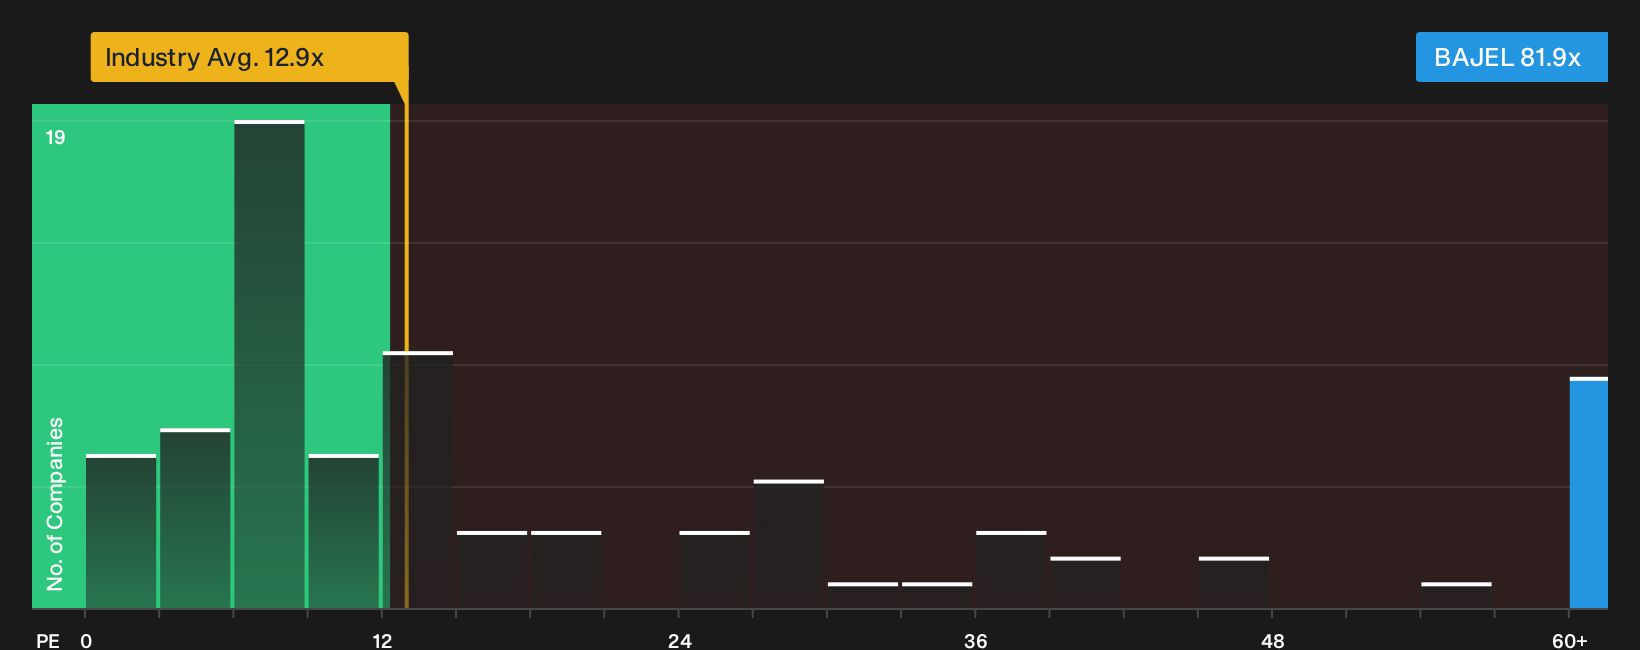
Bajel Projects aligns with the screener theme through rapid earnings growth of 71% over the past year and a pipeline of high value EPC orders in 220 kV and 765 kV transmission. The trade off is a rich P/E of about 81.9x, so a single shift in how those big contracts feed through to cash and margins could matter a lot.
When those rich contracts start converting to cash, the 2 key rewards and 1 important warning sign shows where Bajel Projects’ high P/E could either compress or be fully earned in.
Seeking Alternatives Before Momentum Flies
Fresh ideas do not stay under the radar for long. Once momentum hits, entry points move fast and quietly drop out of reach.
- Review sturdier payers and stress test your income picks against the 224 dividend fortresses before yields change and the crowd focuses on the same payouts.
- Look for early AI leaders and scan the 39 profitable AI stocks that aren't just burning cash that already support ambitious plans with real earnings before valuations shift.
- Monitor the grid upgrade theme and consider exposure through the 42 power grid technology and infrastructure stocks while these infrastructure names are still treated as overlooked utilities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com