
Is Stronger Earnings Altering The Investment Case For Atea (OB:ATEA)?
- Atea ASA reported Q3 2026 sales of NOK 9,860 million and net income of NOK 279 million, with higher basic and diluted earnings per share from continuing operations than a year earlier. For the first nine months, sales reached NOK 29,937 million with net income of NOK 886 million.
- The combination of higher year-on-year sales and earnings for both the quarter and year to date may indicate improved operating efficiency and cost control in Atea's core IT infrastructure and services activities, which can influence how investors view the durability of its cash generation.
- This context helps clarify how Atea's investment narrative could be affected by the stronger year-on-year earnings in its latest report.
Compare Atea's latest earnings momentum with a curated set of financially solid peers using our list of solid balance sheet and fundamentals (207 results) to see where capital-heavy IT and infrastructure businesses cluster on quality.
Atea Investment Narrative Recap
A shareholder in Atea needs to be comfortable with a story built on Nordic and Baltic IT spending, large public contracts and a balance between hardware heavy rollouts and higher margin services such as cloud, security and AI projects. The latest quarter, with higher sales and earnings year on year, supports the idea that the operating model can convert big contract flows into profit.
The near term swing factor remains mix. Strong hardware demand helps revenue, but recurring services are key for margins and resilience. The main risk is that customers keep tilting budgets toward devices while services stay soft, which could cap earnings quality even if reported numbers look healthy.
The Q3 2026 earnings release is the clearest recent signal for those catalysts. Sales of NOK 9,860 million for the quarter and NOK 29,937 million for the first nine months, alongside higher net income versus a year earlier, point to an organisation handling volume and pricing reasonably well across its Nordic footprint.
For an investor tracking triggers like Windows 10 replacement cycles, defense related demand and AI related projects, that earnings pattern gives context. It shows how Atea enters those upcoming contract opportunities, with current profitability, working capital needs and the hardware or services mix all visible in the latest reported figures rather than just in forecasts.
Atea's narrative projects NOK 46.8b revenue and NOK 1.5b earnings by 2029, which implies forecast revenue growth of 5.5% per year and an earnings increase of NOK 300m from current earnings of NOK 1.2b.
Uncover how Atea's fair value signals a 9% potential upside to its current price. This opportunity could narrow quickly if Atea keeps executing on its current trajectory.
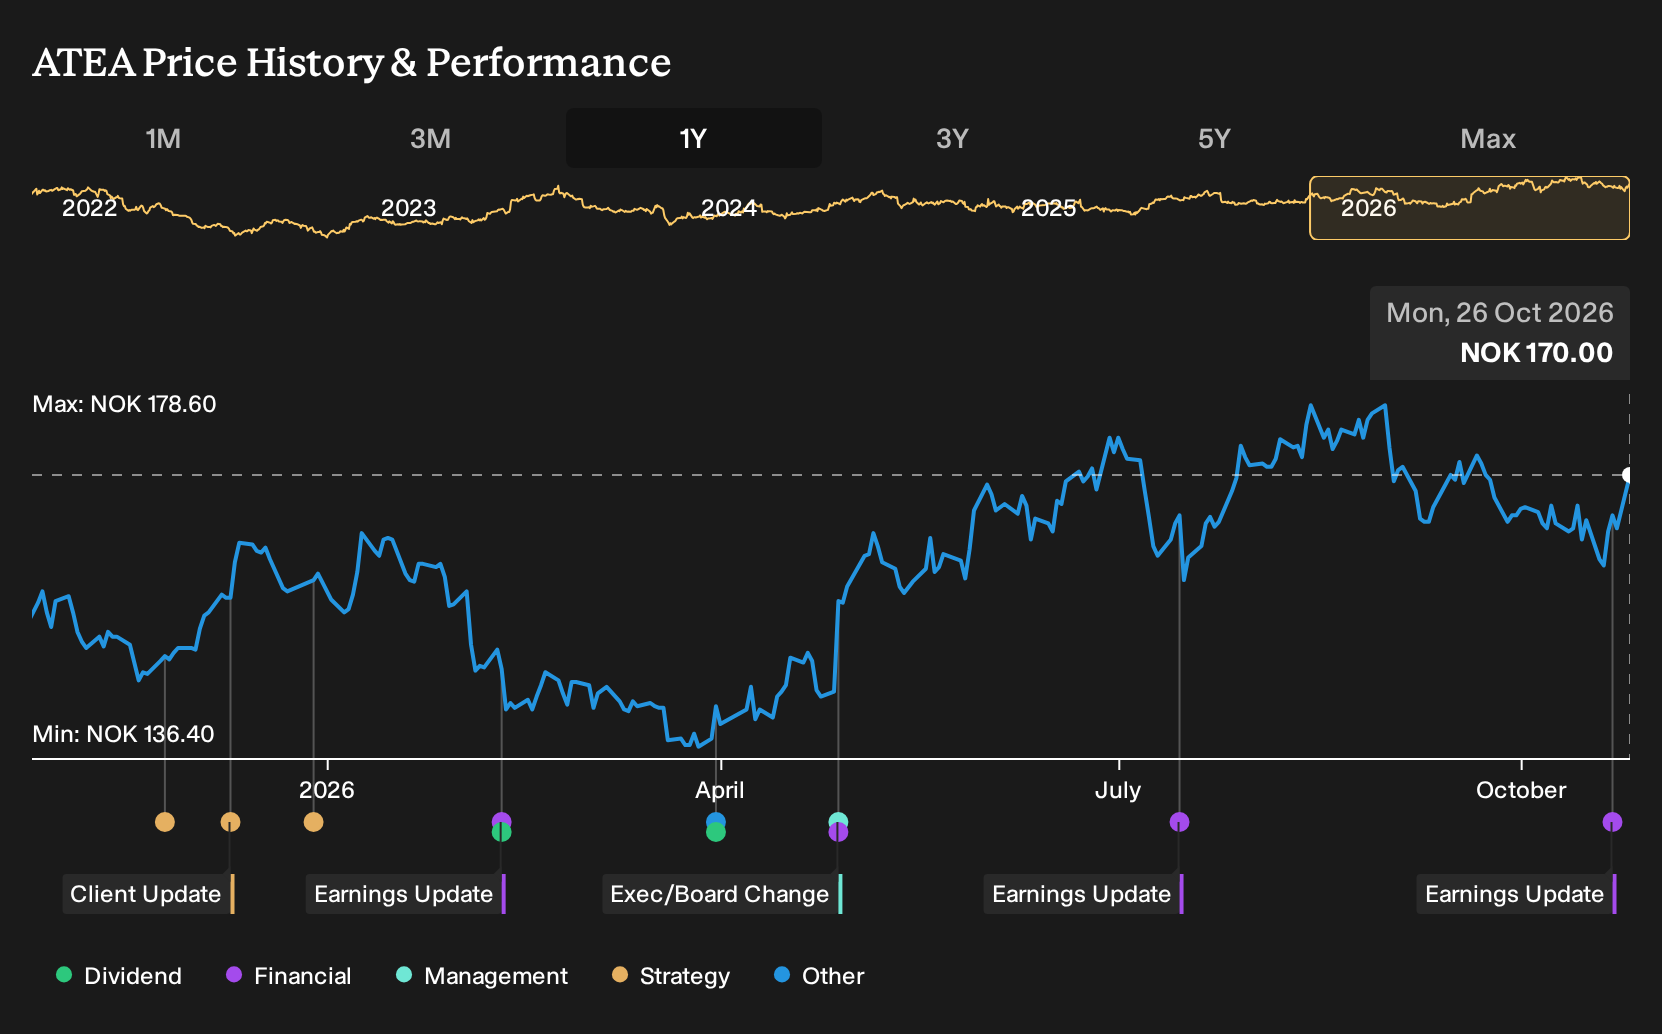
Exploring Other Perspectives
One alternate view on Atea focuses squarely on the cash picture. Before this Q3 report, the most cautious analysts were working off slower revenue assumptions of about NOK 45.0b and earnings around NOK 1.3b by 2029. That group worries the Q2 inventory related cash outflow could signal tougher cash conversion ahead. You can compare that more cautious story with today’s stronger earnings print and determine which version of Atea’s future aligns more closely with your own expectations.
Explore 3 other Atea fair value estimates, including one that suggests it could be worth just NOK180.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your Atea research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Atea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Atea's overall financial health at a glance.
Looking for more Atea style investment ideas?
If Atea's mix of scale, contracts and cash generation appeals to you, it can help to line it up against other listed businesses with different profiles but comparable financial discipline. The Simply Wall St Screener gives you a way to filter that wider universe down to a short list that fits what you care about most, whether that is balance sheet strength, value, income or lower risk.
- For investors who want quality at a reasonable entry point, you can filter for potential value opportunities with our screener showing 195 high quality undervalued stocks.
- If capital preservation and a smoother ride matter most to you, you can narrow the field to sturdier businesses through our tool that highlights 223 resilient stocks with low risk scores.
- For those hunting beyond the usual watchlists, you can broaden your opportunity set with our search focused on 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com