
High Tide Resources (CSE:HTRC) Is In A Good Position To Deliver On Growth Plans
Just because a business does not make any money, does not mean that the stock will go down. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So, the natural question for High Tide Resources (CSE:HTRC) shareholders is whether they should be concerned by its rate of cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
Does High Tide Resources Have A Long Cash Runway?
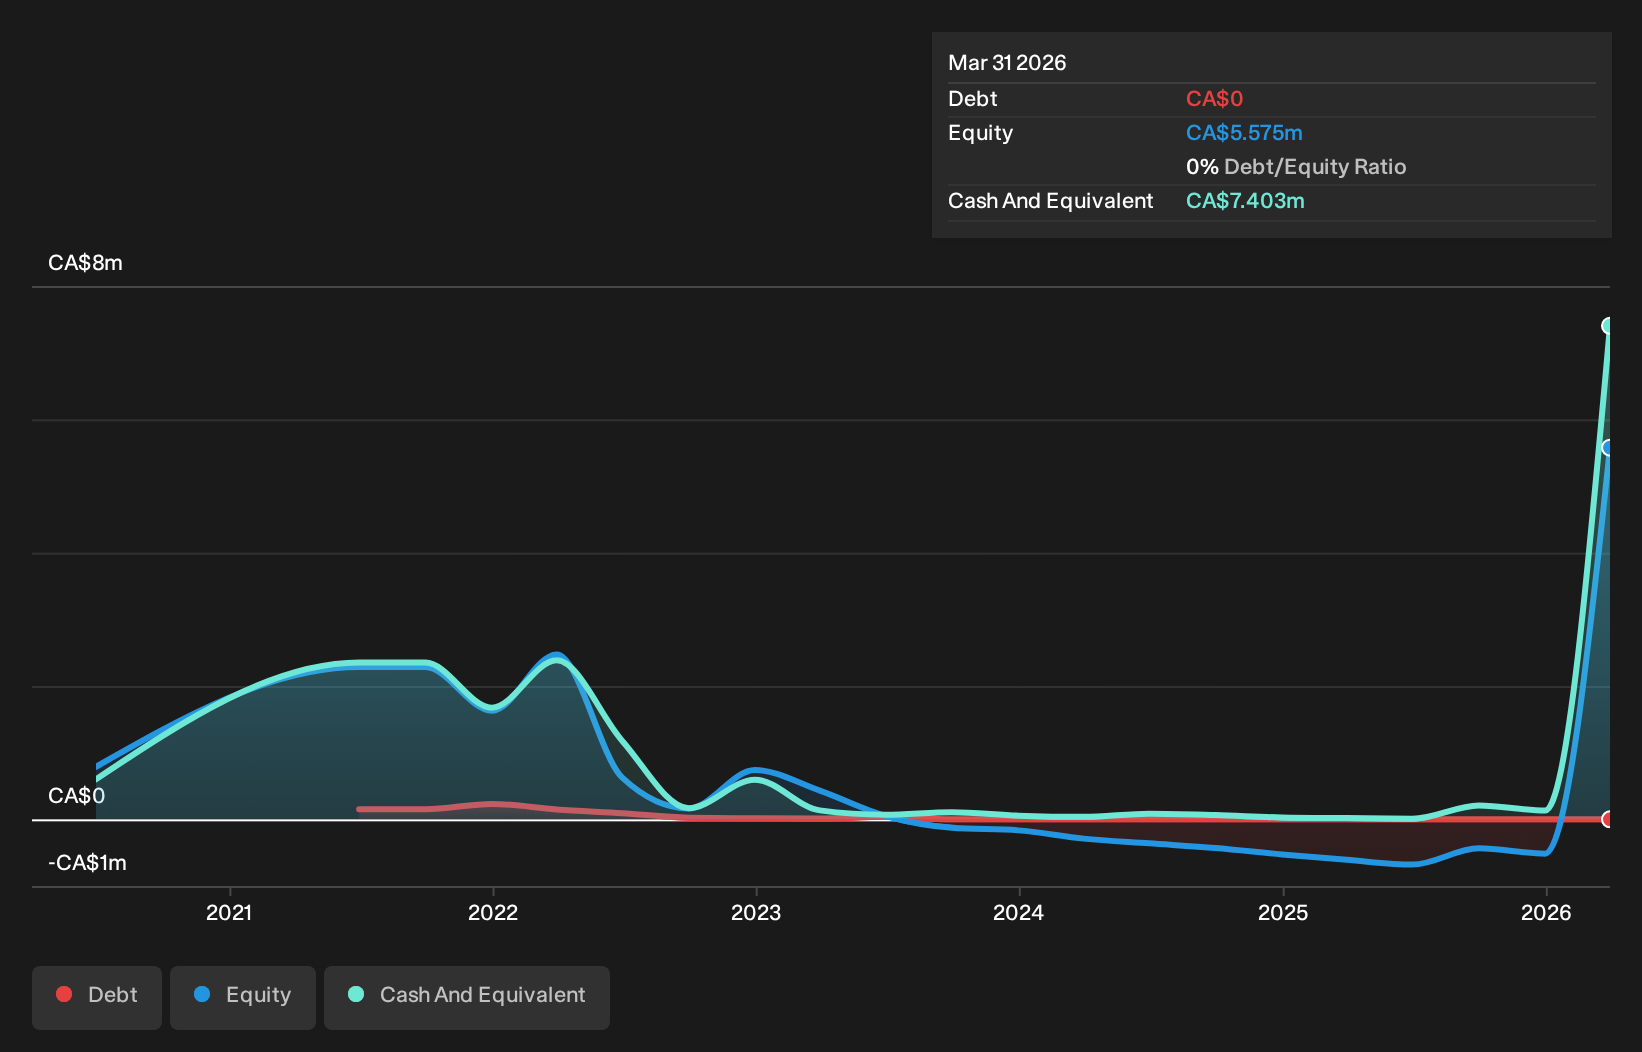
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at March 2026, High Tide Resources had cash of CA$7.4m and no debt. Importantly, its cash burn was CA$793k over the trailing twelve months. Therefore, from March 2026 it had 9.3 years of cash runway. Even though this is but one measure of the company's cash burn, the thought of such a long cash runway warms our bellies in a comforting way. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for High Tide Resources
How Is High Tide Resources' Cash Burn Changing Over Time?
Because High Tide Resources isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. Remarkably, it actually increased its cash burn by 4,097% in the last year. That kind of sharp increase in spending may pay off, but is generally considered quite risky. Admittedly, we're a bit cautious of High Tide Resources due to its lack of significant operating revenues. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
Can High Tide Resources Raise More Cash Easily?
Given its cash burn trajectory, High Tide Resources shareholders may wish to consider how easily it could raise more cash, despite its solid cash runway. Companies can raise capital through either debt or equity. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
High Tide Resources' cash burn of CA$793k is about 2.5% of its CA$32m market capitalisation. So it could almost certainly just borrow a little to fund another year's growth, or else easily raise the cash by issuing a few shares.
So, Should We Worry About High Tide Resources' Cash Burn?
As you can probably tell by now, we're not too worried about High Tide Resources' cash burn. For example, we think its cash runway suggests that the company is on a good path. Although we do find its increasing cash burn to be a bit of a negative, once we consider the other metrics mentioned in this article together, the overall picture is one we are comfortable with. Looking at all the measures in this article, together, we're not worried about its rate of cash burn; the company seems well on top of its medium-term spending needs. Separately, we looked at different risks affecting the company and spotted 4 warning signs for High Tide Resources (of which 2 are a bit unpleasant!) you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.