
Prologis (PLD) Could Be 17% Undervalued On Updated 2026 Earnings Guidance
Prologis (PLD) has been back in focus after reporting third quarter 2026 earnings and updating full year guidance, giving investors fresh numbers on sales, profit and expected net earnings per share.
Prologis shares trade at US$126.31 after a mixed stretch where the share price fell 14.1% over three months and 5.1% over the past month. However, the 3 year total shareholder return of 40.7% hints that longer term holders have still seen solid gains as recent earnings and guidance updates reset expectations around growth and risk.
Scan how Prologis compares on quality and valuation by lining it up against our hand-picked 29 high quality undervalued stocks that share strong fundamentals with compressed expectations.
Recent results, updated guidance and a pullback to US$126.31 put Prologis at an interesting crossroads. Does it make sense to step in after this reset, or wait for a cheaper shot at the same earnings profile?
Most Popular Narrative: 17% Undervalued
Against a fair value estimate of $152.85 based on the most widely followed Prologis narrative, the last close at $126.31 implies a clear valuation gap that investors now have to explain with either slower growth assumptions or higher risk around the story.
The build out of value added services, including a dedicated data center development platform with 5.8 GW of power pipeline and an expanding on site solar and storage business of roughly 1.3 to 1.4 GW, creates additional fee and rental streams that can support higher consolidated revenue and margins as projects are delivered.
See why 111 investors see Prologis as 17% undervalued.
Result: Fair Value of $152.85 (UNDERVALUED)
Still, the Prologis narrative can break if equity issuance keeps diluting per share results or if the large SEGRO deal fails to deliver as modeled.
Find out about the key risks to this Prologis narrative.
Another View: Prologis Through The P/E Lens
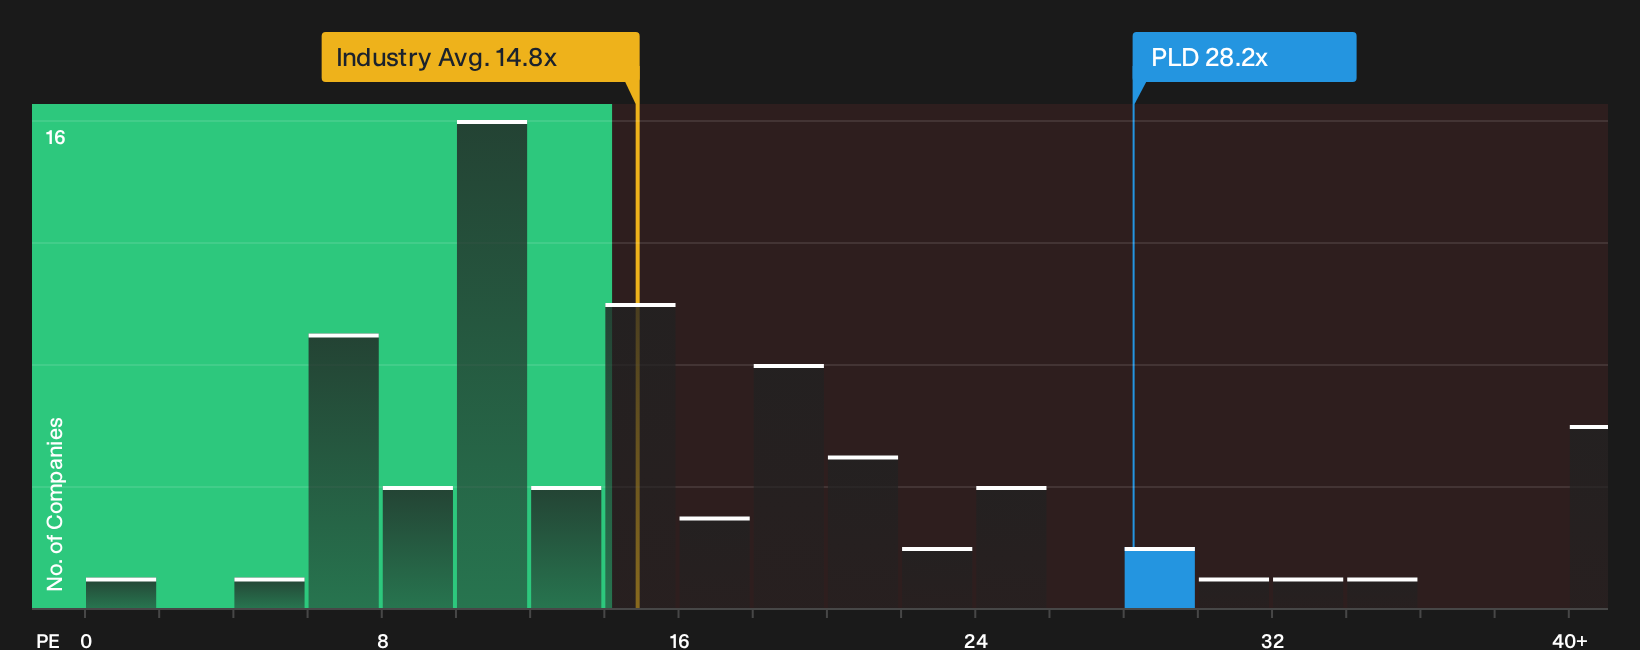
That 17% gap to fair value is one story. A different picture emerges when you look at Prologis through its P/E. The stock trades on 28.2x earnings, richer than both the Global Industrial REITs average at 14.8x and its direct peer group on 25.3x, yet only slightly below a fair ratio of 30.7x that the market could drift toward over time.
If investors already pay a premium multiple for Prologis, even with that modest discount to the fair ratio, how much room is really left if sentiment cools or growth expectations soften?
See what the numbers say about this price by reviewing our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between premium P/E and implied undervaluation feels messy, that is the point. You need to check the underlying data yourself and decide whether the rewards justify the issues that concern investors by weighing the 4 key rewards and 2 important warning signs.
Looking for more Prologis style investment ideas?
If Prologis has you thinking harder about price and quality, you can use the same lens across other opportunities with a focused screen of potential candidates.
- Target potential mispricing in stronger businesses by scanning a curated 29 high quality undervalued stocks that already combine quality fundamentals with restrained expectations.
- Anchor your portfolio with steady income ideas by hunting through 5 dividend fortresses that pair higher yields with more resilient payout profiles.
- Protect against fragile balance sheets by filtering for companies in the list of solid balance sheet and fundamentals (24 results) that can better withstand financial pressure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com