
Hecla Mining (HL) Stock Could Be 33% Undervalued Following Record Silver Output
Hecla Mining has delivered a very strong 236.7% return over the past 3 years, and fresh production records have kept the stock firmly on investor watchlists. With that kind of price performance on the table, the obvious question is whether the current share price lines up with the cash flows the business is expected to generate.
- A roughly 3.4x gain over 3 years has transformed the experience of long term holders. This now puts far more weight on whether Hecla Mining's current valuation can be supported by its cash flow profile.
- Record silver output, lower all in sustaining cost guidance and a larger cash buffer may support expectations for more resilient future cash generation, which matters directly for any cash flow based assessment of Hecla Mining today.
- What if you looked at Hecla Mining through its earnings instead? See why Hecla Mining's 17.0x P/E tells a different valuation story.
The stock's next move may depend on whether the present share price is justified by the intrinsic value suggested by its cash flows.
If you are weighing whether Hecla Mining's recent 3 year surge still lines up with its cash flows, it can help to compare that same question across 29 high quality undervalued stocks.
Is Hecla Mining Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model estimates what Hecla Mining could be worth based on the cash it is expected to generate for shareholders. On recent numbers, the business produced last twelve month free cash flow of about $398.1 million, and the DCF framework uses projections that point to growing annual cash flows rather than a shrinking profile.
Those forecasts stretch well into the next decade using a two stage Free Cash Flow to Equity approach, with cash flow estimates rising from the current base before settling into steadier long term growth. The DCF outcome sits substantially above the current share price of $13.98, which suggests the market is putting a relatively cautious label on those future cash streams. Because the Q2 2026 record silver production and stronger balance sheet improve the backdrop for funding future projects, that conservatism helps explain why some investors see more value in Hecla Mining than the price implies today. Find out what Hecla Mining could be worth using our Discounted Cash Flow (DCF) estimate.
The Hecla Mining Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hecla Mining pick up where the cash flow puzzle leaves off. They spell out which paths for production growth, profitability and earnings would need to play out for the shares to be worth materially more or less than today’s market value. Each view ties its number to a concrete read on how Hecla Mining's growth prospects, cost profile and risk picture could shift, giving you something specific to revisit as new information comes through.
One of the top community narratives on Hecla Mining: 37% undervalued
"Hecla may benefit from accelerating demand for silver driven by ongoing global electrification and renewable energy growth…"
Discover why this Narrative puts Hecla Mining at 37% undervalued.
One more piece of the Hecla Mining puzzle
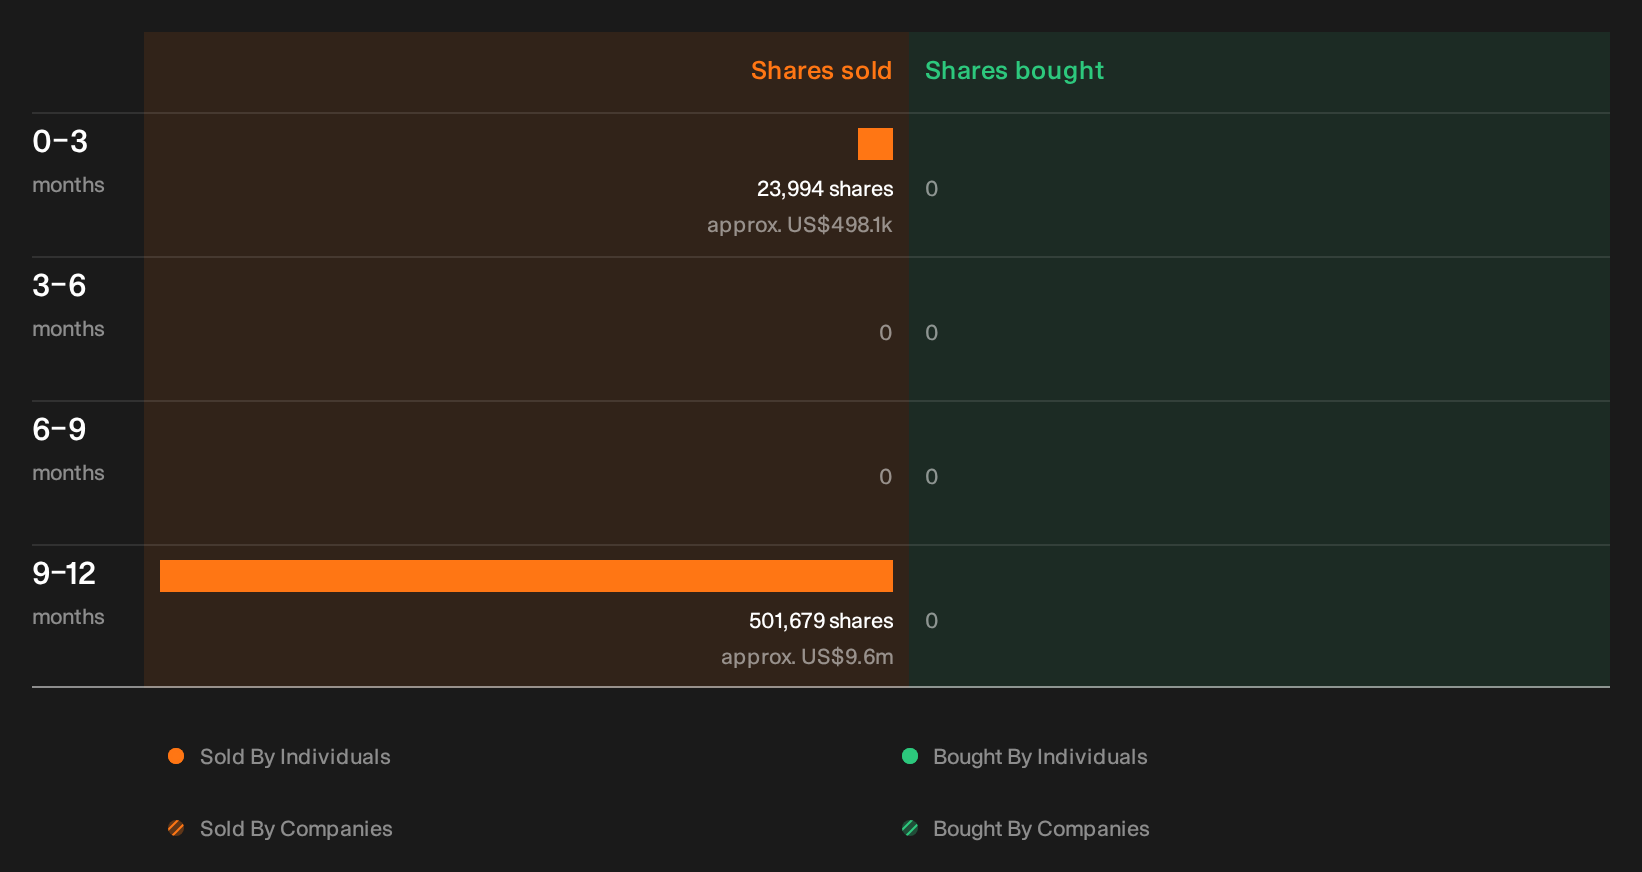
Price, production and cash flow only tell part of the story for Hecla Mining, since recent insider transactions have also been flagged by our checks and the who, how much and why are still for you to review. See the recent insider selling flagged for Hecla Mining.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com