
Does Earnings Momentum Change The Bull Case For Mullen Group (TSX:MTL)?
- Mullen Group reported third quarter 2026 sales of C$653.17 million and net income of C$51.5 million, with higher basic and diluted earnings per share than a year earlier.
- The board also confirmed a monthly dividend of C$0.07 per common share, indicating continued cash returns to shareholders alongside reported profitability for both the quarter and year to date.
- We will assess how Mullen Group's third quarter earnings profile fits into the existing investment narrative around scale and profitability.
Mullen Group Investment Narrative Recap
Mullen Group appeals to investors who want a diversified trucking and logistics operator that leans into asset light services and technology to support earnings. The latest quarter shows the business generating higher sales, net income and earnings per share versus a year earlier. That reinforces the idea that integration of acquisitions and cost control remain near term drivers rather than a single transformative project.
The main short term catalyst stays the same. Investors are watching whether recent earnings momentum can be sustained while pricing pressure, wage inflation and regulatory costs remain very real. Reliance on acquired units and exposure to cyclical industrial customers still frame the key operational risk.
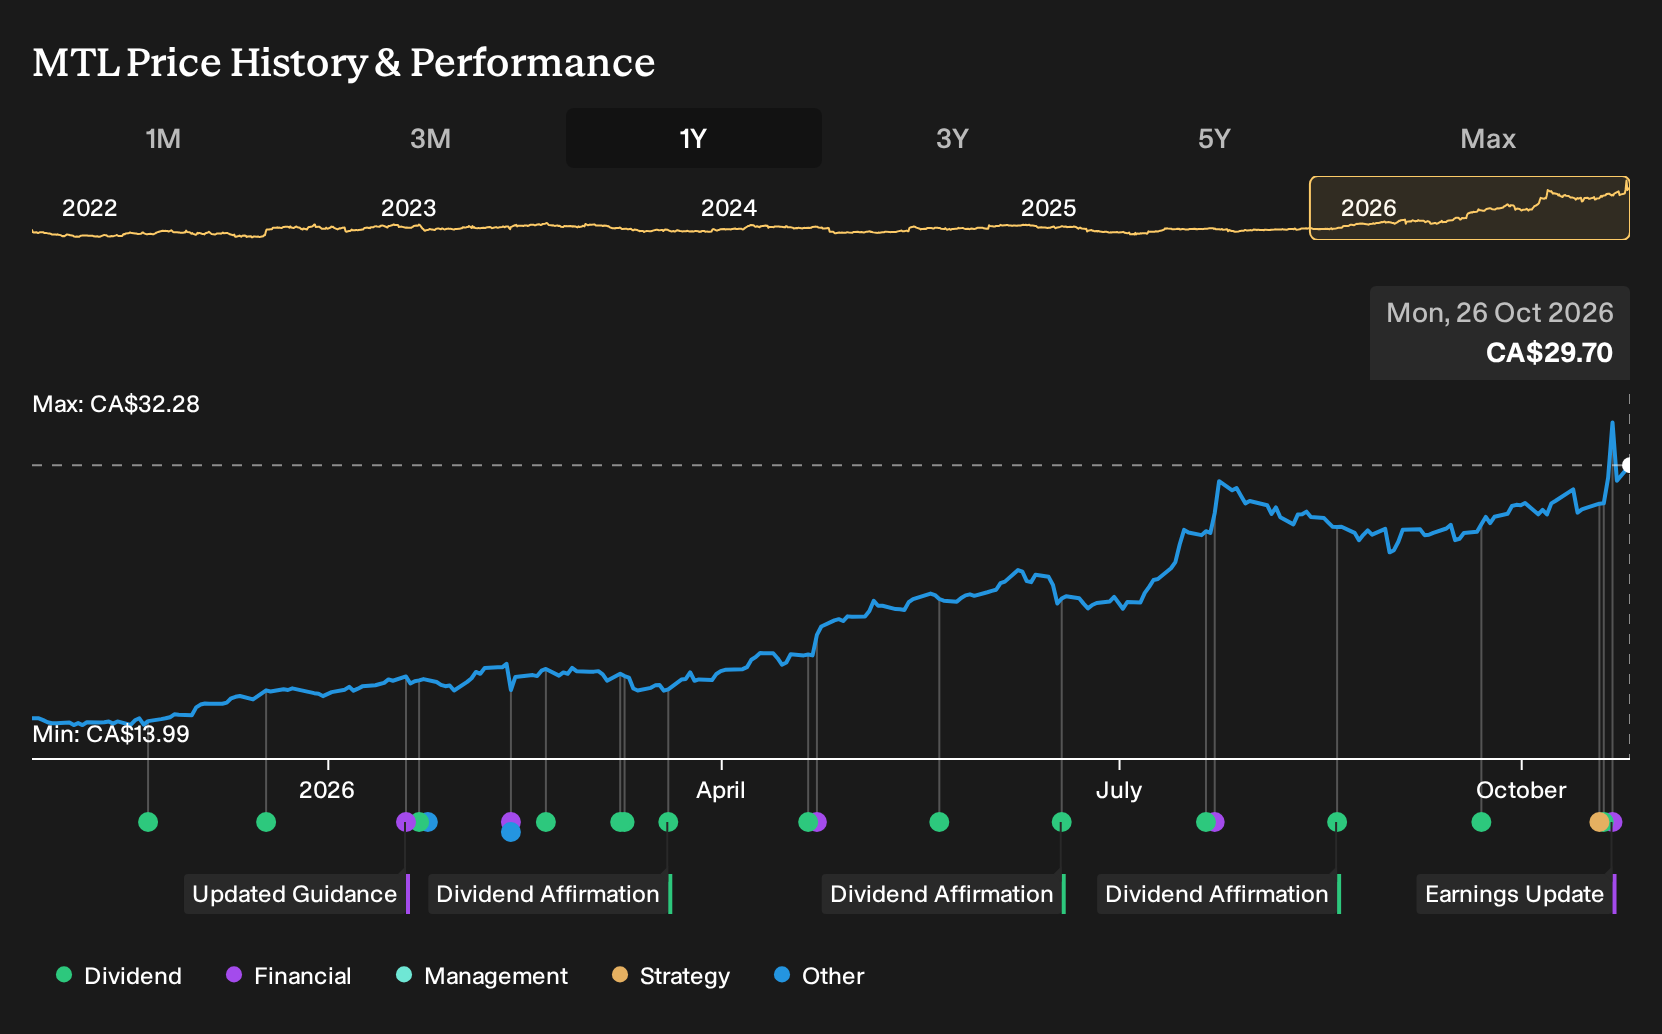
The most relevant fresh data point is the third quarter 2026 print. Sales reached C$653.17 million and net income came in at C$51.5 million, with both basic and diluted EPS from continuing operations higher than in the prior year period. For the first nine months, revenue of C$1,810.17 million and net income of C$108.49 million provide a clearer sense of scale.
Those figures matter for the existing Mullen Group thesis because they speak directly to margin resilience and cash generation, two areas investors watch closely given acquisitions, debt and cyclical exposure. If future quarters keep showing similar earnings quality, that can support the case that pricing pressure and cost inflation are being managed, though the risk of margin compression has not gone away.
Mullen Group's analyst narrative points to forecast revenue of C$2.9b and earnings of C$218.2 million by 2029, underpinned by assumed yearly revenue growth of 7.3%. That profile implies earnings today of C$123.1 million and an earnings increase of about C$95 million to reach the C$218.2 million consensus level.
Uncover how Mullen Group's fair value indicates a potential 4% upside to its current price before other investors close that gap.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span a wide band, from C$15 at the low end to about C$50.52 at the top, showing how far opinions on Mullen Group can stretch. When you set that against risks around pricing pressure, acquisition dependence and cyclical freight demand, you are reminded to weigh several contrasting viewpoints before acting.
Explore 3 other Mullen Group fair value estimates, including one that suggests as much as 70% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mullen Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mullen Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mullen Group's overall financial health at a glance.
Looking for more Mullen Group style investment ideas?
If the Mullen Group story has you thinking about portfolio gaps, it can help to scan a wider field of opportunities with similar qualities. The Simply Wall St Screener lets you filter for dividends, balance sheet strength or valuation factors in a few quick steps, so you can build a watchlist that actually reflects what you care about.
- For investors who want potential value aligned with quality fundamentals, start with a curated set of 3 high quality undervalued stocks that may warrant closer inspection.
- If capital preservation and balance sheet resilience rank high on your checklist, focus on companies from the 8 resilient stocks with low risk scores to see which ones meet your comfort level.
- Those hunting for resilient income streams can scan a hand picked pool of 3 dividend fortresses that could complement Mullen Group in a yield focused portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com