
Does Earnings Strength Change The Bull Case For NextEra Energy Stock (NEE)?
- NextEra Energy reported third quarter 2026 sales of US$8,090 million and net income of US$4,775 million, alongside a regular quarterly dividend of US$0.6232 per share that was declared in October and paid in December 2026.
- The combination of higher earnings per share from continuing operations and a maintained dividend highlights how current profitability supports NextEra Energy's ongoing capital return to shareholders.
- We now examine how NextEra Energy's stronger earnings per share from continuing operations could influence the broader investment narrative.
Scan beyond NextEra Energy and line up other utilities delivering earnings strength with consistent capital returns using our hand picked 5 dividend fortresses as a starting universe.
NextEra Energy Investment Narrative Recap
For you to be comfortable as a shareholder in NextEra Energy, you need to believe the business can keep turning its large project backlog and Florida Power & Light expansion into steady earnings, even with policy changes and rate volatility in the background. The latest quarterly figures support that bigger story, but do not fundamentally change it.
The short term swing factor remains execution on capital projects and financing them sensibly. Higher earnings per share from continuing operations help absorb interest costs, yet debt coverage from operating cash flow and exposure to tax credit policy stay front of mind. Those risks are still in play after this update.
The most relevant update for that thesis is the third quarter 2026 earnings release. Sales for the period were US$8,090 million, with net income of US$4,775 million and basic earnings per share from continuing operations of US$2.29. For the first nine months of 2026, management reported US$22,325 million in sales and US$10,102 million in net income.
For you as an investor, those numbers matter because the investment case around data center load growth, a large renewables and storage backlog, and new gas build depends on converting projects into earnings that comfortably fund interest, capital spending, and the dividend. The stronger earnings per share print supports that execution story, while risks tied to policy incentives and financing costs remain important to track.
NextEra Energy's current analyst framework points to revenue of US$39.9b and earnings of US$10.6b by 2029, based on an assumed 11.6% yearly revenue growth rate. That profile implies earnings would increase by about US$1.3b from US$9.3b today to reach the 2029 consensus target.
Uncover why NextEra Energy's fair value indicates an 18% potential upside to its current price that could narrow quickly.
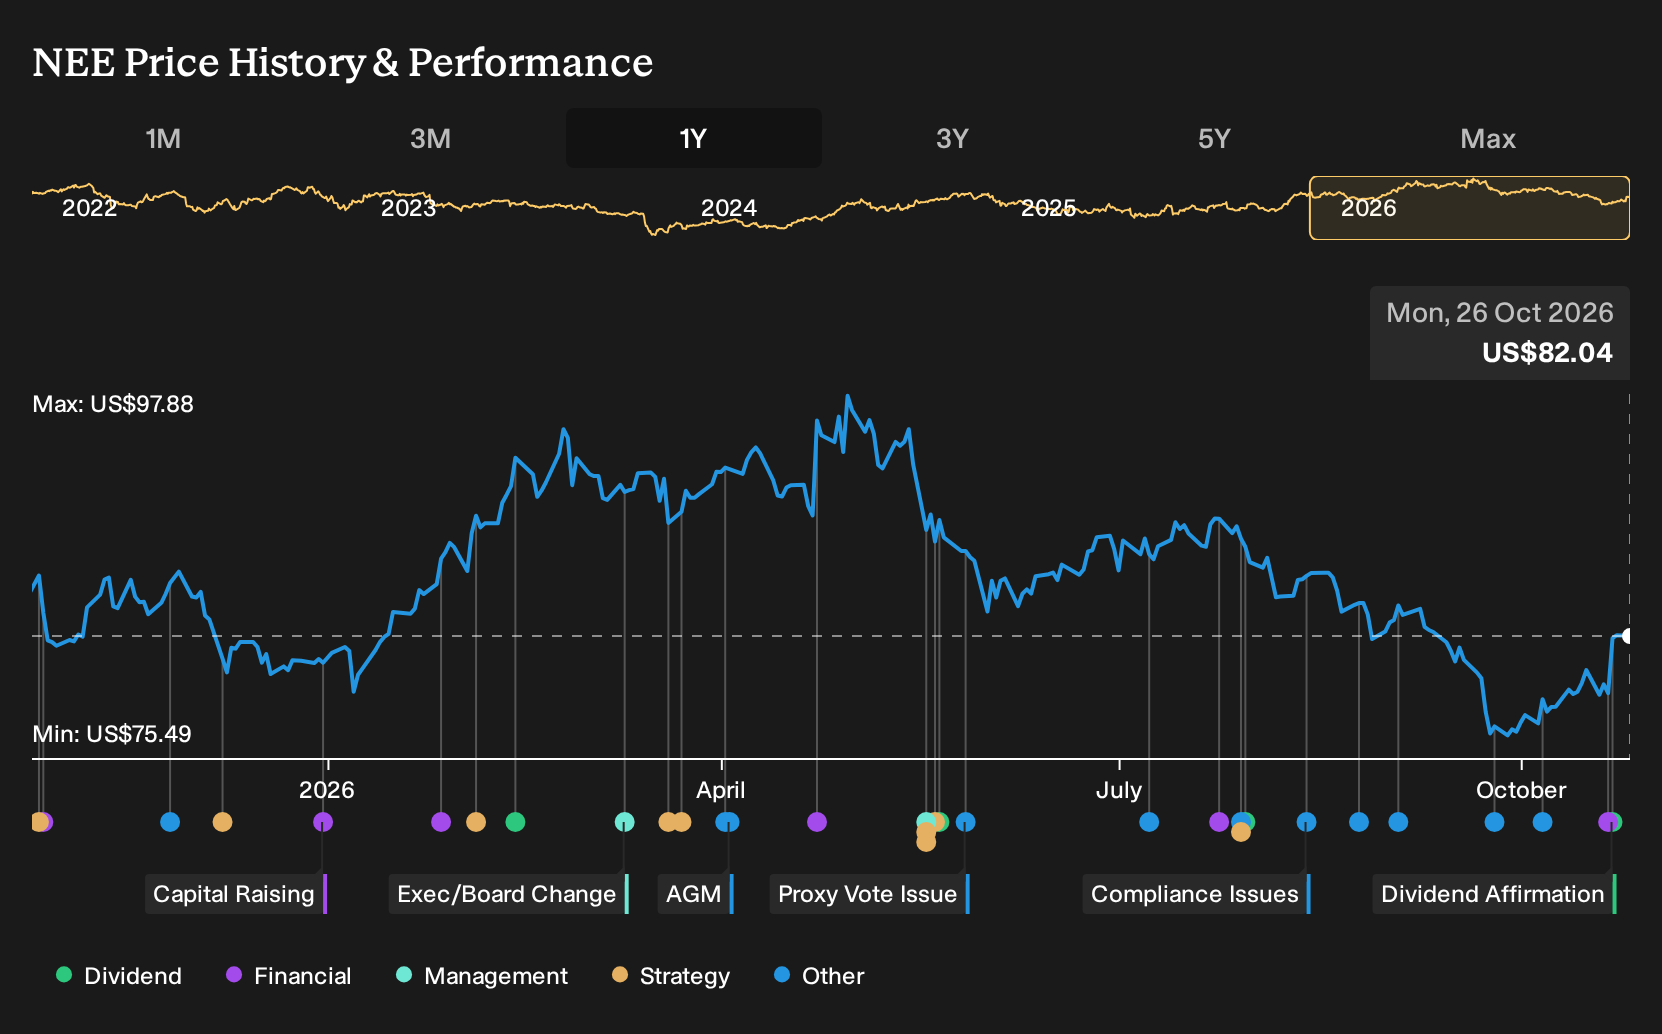
Exploring Other Perspectives
One alternative view for NextEra Energy puts regulatory pressure at the center of the story. The most cautious analysts worried that tighter allowed returns could cap value creation and were penciling in 2029 revenue of about US$33.6b and earnings of roughly US$9.7b. Those projections came before this dividend affirmation and earnings release, so expectations may shift from here.
Explore 7 other NextEra Energy fair value estimates, including one that suggests up to 6% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your NextEra Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NextEra Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NextEra Energy's overall financial health at a glance.
Looking For More Ideas Beyond NextEra Energy?
If the latest NextEra Energy update has you thinking about portfolio balance, use the Simply Wall St Screener to line up other businesses that fit your income, quality, or risk profile.
- For investors who care most about stability and lower volatility, start with a curated set of 30 resilient stocks with low risk scores that may better match a more defensive approach.
- If robust finances matter most to you, filter for companies on our list of solid balance sheet and fundamentals (24 results) and focus your time on businesses with healthier balance sheets.
- To widen your opportunity set beyond well known tickers, cast a wider net across 21 high quality undiscovered gems that combine fundamental strength with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com