
Wondering Why Canada Goose Fell? Here's What Bears Saw
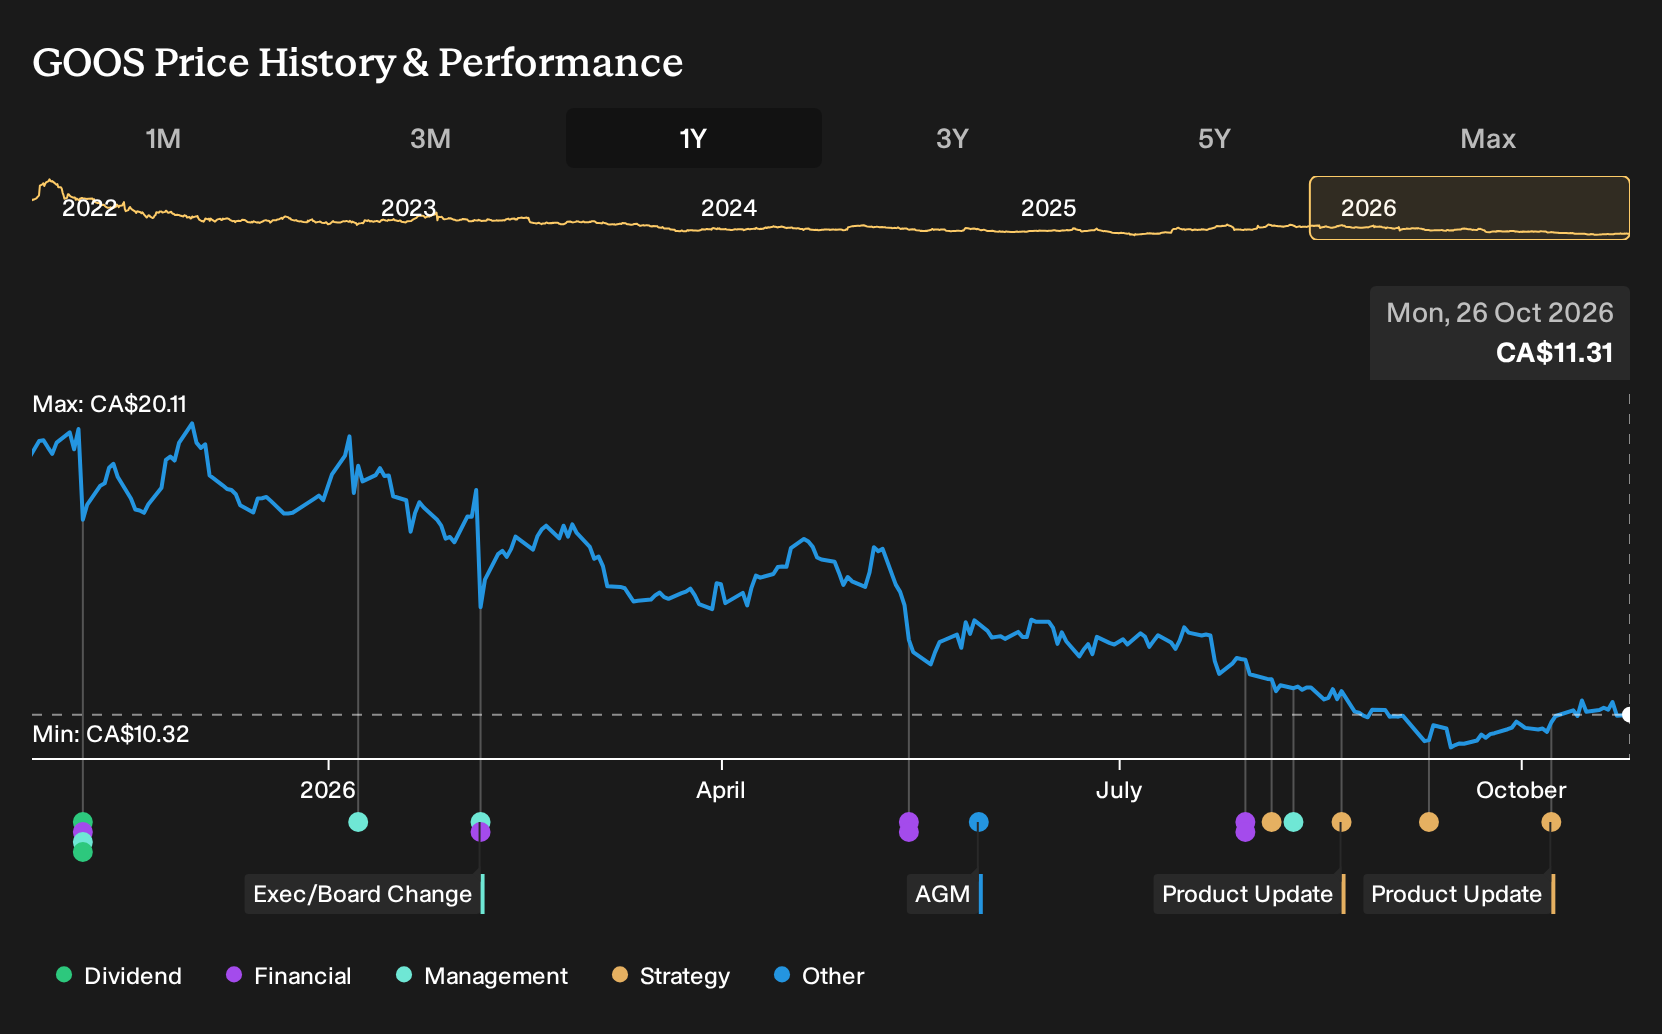
If you had glanced at Canada Goose in late October 2025 and decided to hold off, the outcome over the next twelve months looked very different to those who stayed in. For Canada Goose shareholders, the loss over the past year was 42.2%, including dividends. Recent headlines now focus on upcoming earnings and earlier quarterly results, but the key question is simpler: What assumptions, already on record back then, might have justified more caution?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Canada Goose has already moved. See which of 3 high quality undervalued stocks still trade below our estimates.
The Argument Canada Goose Investors Faced Back Then
The shares cost CA$18.91 at the start of the period, and anyone looking at Canada Goose then was weighing two very different stories that both looked plausible on the record.
The bullish narrative put Fair Value at CA$21.03, built on revenue growth of 4.8% and an assumption that profit margins could reach 5.5% over three years, helped by direct-to-consumer momentum and broader product ranges.
The bearish view pinned Fair Value at CA$10, assuming revenue would decline 2.5% a year and arguing that milder winters and fast-fashion rivals could limit demand and pressure a future P/E of 9.0x.
What The Results Changed For Canada Goose
The clearest fresh fact was Canada Goose’s Q1 2027 report. Revenue was CA$118.9m compared with CA$107.8m a year earlier, while the loss shrank from CA$125.2m to CA$90.8m and net margin improved from a loss of 116.1% to a loss of 76.4%. That mix supported the stronger revenue story but left the profitability goal still unproven.
The episode turned on one simple assumption: that higher sales would come with sustainably better earnings. When you review another retailer or luxury stock, track whether revenue, absolute profit and net margin move together in the reported numbers or start to pull apart.
What Canada Goose’s Drop Asks You To Believe Now
Canada Goose trades at CA$11.31 today, with the selected Narrative’s Fair Value sitting above that market price. The current argument leans on international demand, a heavier direct-to-consumer mix and a broader, year round assortment rather than just heavyweight down parkas.
For the decline over the past year to look like an opportunity instead of a warning, a buyer would need to believe direct-to-consumer productivity and rebuilt wholesale relationships can support the margin plan described in the Narrative.
"Expansion of Canada Goose Holdings into year round categories such as apparel, knitwear, fleece, rainwear and windwear, which now contribute a large share of revenue and roughly half of units, can deepen wardrobe penetration and support more diversified revenue beyond heavyweight down. Ongoing focus on direct to consumer productivity, with store level sales per square foot and EBIT margin targets that the fleet recently exceeded, can support higher contribution from this higher margin channel and benefit earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Canada Goose
Thinking about Canada Goose keeps you focused on outerwear and cold weather demand. One step away, a different kind of performance gear matters.
Your winter jacket choice solves warmth. Another brand is trying to solve how people run, train and move all year.
Its business depends on keeping products premium, even when much of the market discounts heavily.
That approach leans on direct sales and higher value apparel to do more of the work.
If that full price discipline holds, this player's place in activewear could end up unlike a traditional shoe label.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 90% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com