
Will Pipeline Growth Change Worley's (ASX:WOR) Narrative
- Worley reported a 24% year-on-year increase in its factored sales pipeline and secured more than A$10b of recent work across LNG, power, and energy transition materials, reflecting demand for its engineering and project services in low carbon and conventional energy markets.
- The company’s growing role in nuclear power projects within its low carbon energy arm highlights how Worley’s technical expertise is tied directly to decarbonisation driven project demand and potential future earnings power.
- We will look at how Worley’s investment narrative is affected by the 24% sales pipeline uplift and related energy transition contract wins.
Scan 16 nuclear energy infrastructure stocks to see which other nuclear and energy transition plays share Worley’s mix of engineering depth and long-duration project pipelines.
Worley Investment Narrative Recap
To own Worley, you need to believe its role in energy transition and large, complex projects translates into a steadily larger pool of work and a healthier earnings mix. The 24% uplift in the factored sales pipeline and A$10b of recent wins support that broader thesis, even if the share price has fallen 29% over the past year.
The key short term swing factor is how quickly new LNG, power and nuclear contracts turn into backlog and margins, especially after delayed awards and flat FY26 revenue. The biggest near term risk is that more project deferrals or cancellations, particularly in chemicals and conflict exposed regions, offset the stronger pipeline and keep EBITA under pressure.
The most relevant piece of context is Worley’s A$15.5b of FY26 bookings across gas infrastructure, pumped storage, nuclear and low carbon power. That booking level sits behind today’s 24% higher sales pipeline and helps explain why energy transition work, including nuclear, is becoming more central to how the business earns its fees.
For investors, the link is simple. If those multi year awards convert into reimbursable EPC and EPCM backlog at decent margins, Worley’s shift toward higher value consulting, digital delivery and long duration energy transition projects has a clearer path to supporting earnings. If project delays persist, that same backlog and catalyst set looks less powerful.
Worley's narrative projects A$13.6b revenue and A$447.7m earnings by 2029. This assumes 8.2% yearly revenue growth and an earnings increase of about A$209.7m from A$238.0m today.
Uncover why Worley's fair value indicates a 20% potential upside to its current price, which could close sooner than many investors expect.
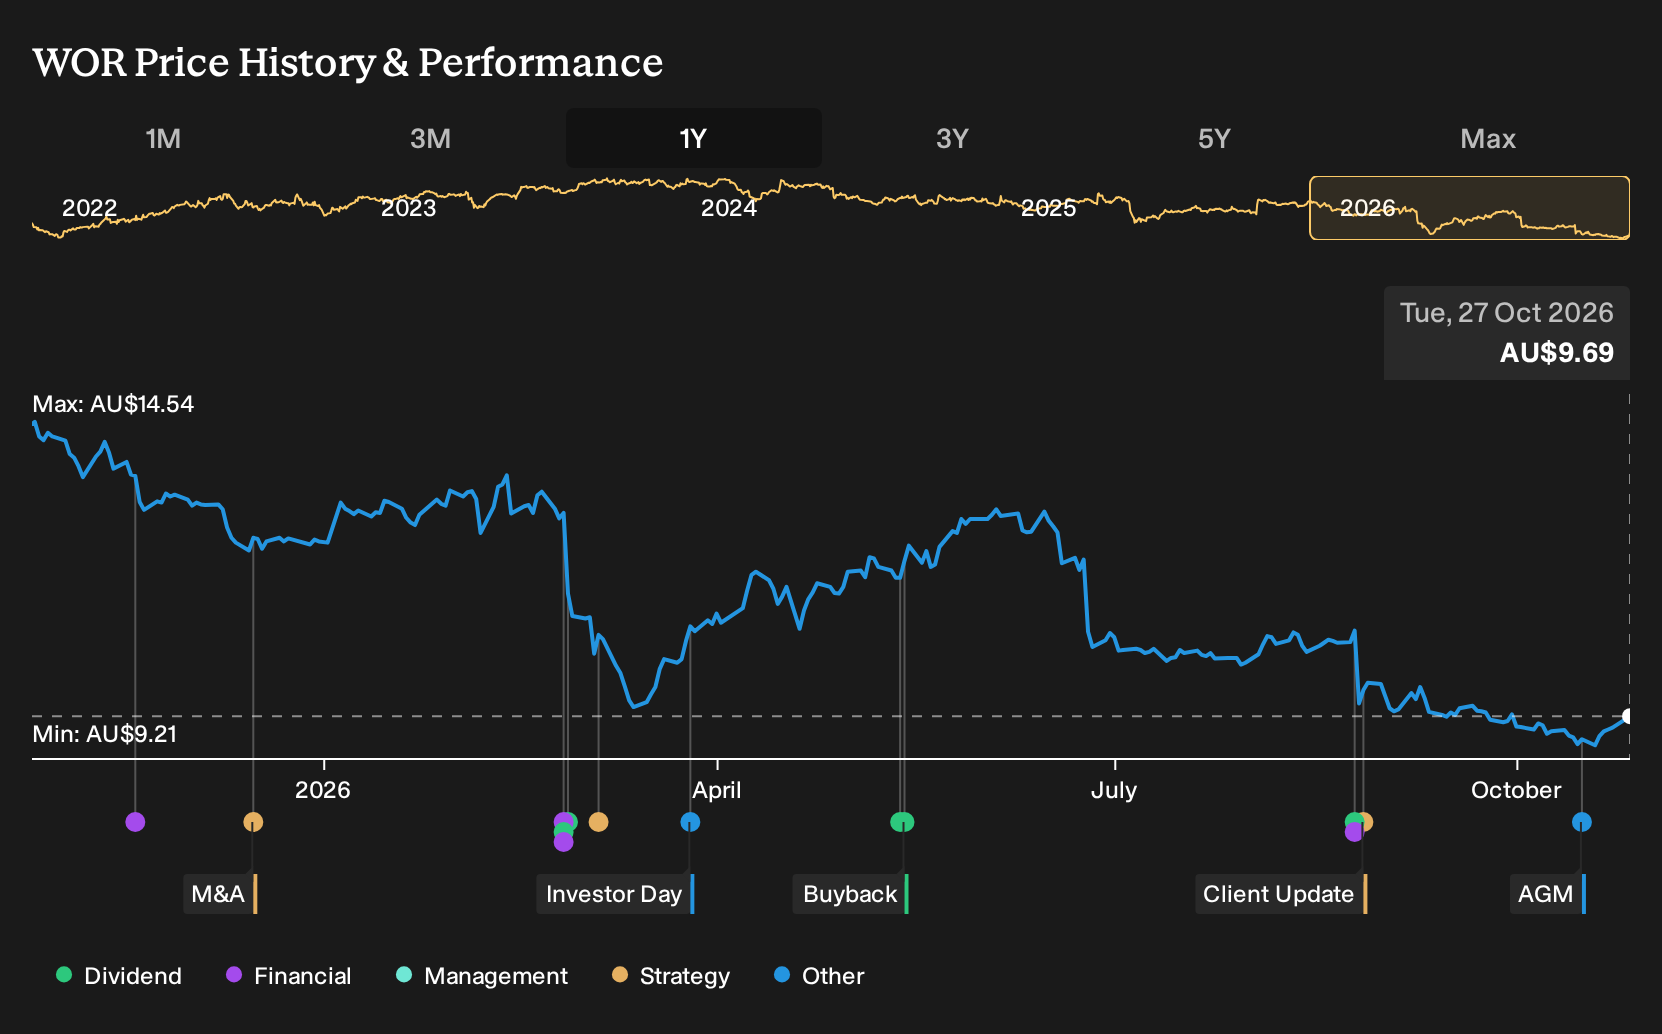
Exploring Other Perspectives
One alternate, more optimistic view focuses on Worley’s energy transition mix rather than project delays. In that storyline, rising nuclear, data center and low carbon work supports faster compounding than consensus, with bullish analysts previously pencilling in 10.4% annual revenue growth and A$586.9m earnings by 2029. Those pre news forecasts may shift once this latest pipeline update is absorbed.
Explore 4 other Worley fair value estimates, including one that suggests as much as 50% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Worley research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Worley. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Worley's overall financial health at a glance.
Looking For More Investment Ideas Beyond Worley?
Worley might fit your view on energy transition and long duration projects, but a stronger portfolio usually rests on more than one stock. The Simply Wall St Screener can help you quickly filter for other companies that match your preferred balance of quality, value, and resilience.
- If capital preservation matters most to you, focus on sturdier balance sheets and earnings consistency with a 6 resilient stocks with low risk scores that keep downside risk in check.
- For investors who want dependable income on top of potential capital gains, zero in on resilient payers through a 4 dividend fortresses that aim to combine yield with staying power.
- If you are hunting for tomorrow's leaders before the crowd notices, cast a wider net across underfollowed opportunities using a 15 high quality undiscovered gems that already show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com