
PLTR Stock Earnings Preview: What to Expect From Palantir's Q3 Report
Palantir Technologies (PLTR) will release its third-quarter earnings on Monday, Nov. 2. Ahead of the release, PLTR stock has rebounded strongly, up about 62% over the last three months. The stock got a significant boost from its solid Q2 performance and upward revision in its full-year outlook for revenue, operating income, and adjusted free cash flow.
Palantir has reported strong results in recent quarters, supported by solid demand for its Artificial Intelligence Platform (AIP). However, Q3 faces tough year-over-year comparisons, which could impact its growth rate. Let’s take a closer look.
PLTR Q3 Outlook
While Palantir faces tough year-over-year comparisons in Q3, business momentum will likely hold. Solid momentum in the domestic business, especially from commercial customers, is likely to support growth. In the second quarter, Palantir’s revenue surged 93% year-over-year to $1.94 billion, reflecting robust U.S. performance.
U.S. revenue more than doubled from the year-ago quarter to $1.57 billion, accounting for over 81% of total sales. The commercial business was a major contributor, generating $764 million in revenue, up 149% YOY and 28% sequentially.
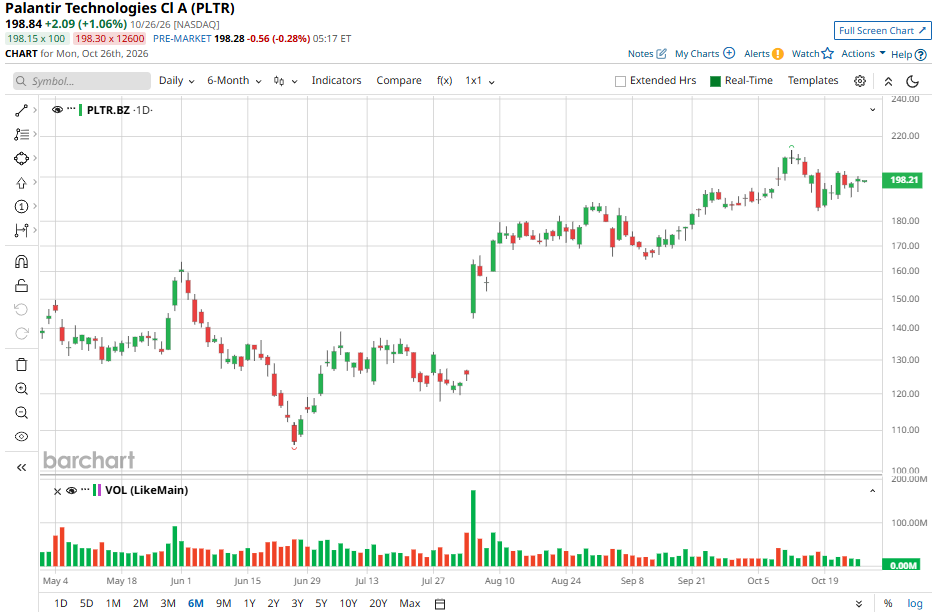
The solid momentum in its U.S. business is expected to continue in Q3 and beyond. Based on the midpoint of management’s guidance, Palantir is projected to generate $2.16 billion in revenue, up 83% year-over-year. Given its recent accelerating revenue growth and persistent demand for its AI platform, PLTR could exceed its top-line guidance.
Customer acquisition and deeper engagement with existing clients are also expected to drive growth. Palantir ended Q2 with 653 U.S. commercial customers, marking a 35% increase from the prior-year period and a 6% rise from the previous quarter. PLTR’s customer count is expected to increase in the commercial segment.
Spending trends among large accounts further highlight the growing adoption of Palantir’s solutions. Revenue from its 20 largest customers over the trailing 12 months increased 67% year-over-year, with average revenue per customer reaching approximately $124 million. Further spending growth from these accounts would strengthen top- and bottom-line growth.
Palantir’s government business is another important driver of its growth. U.S. government revenue rose 90% year-over-year to $809 million in Q2. The business will benefit from continued execution in existing programs and new awards driven by growing demand for its AI platform.
Taken together, rising U.S. commercial sales, sustained government demand, and an expanding customer base could support further gains in both revenue and profitability.
Palantir expects adjusted income from operations of about $1.29 billion for Q3, compared with $601 million in the year-ago quarter. Moreover, its adjusted operating income is also projected to increase sequentially.
Higher revenue and improved operating income are likely to support Q3 earnings. Analysts expect Palantir to report Q3 earnings of $0.33 per share, up 83.3% year-over-year.
Palantir has beaten consensus earnings estimates in each of the past four quarters, and it could do the same in Q3.
Here’s What Analysts Recommend for Palantir Stock
Palantir’s Q3 results are expected to reflect sustained demand for its AI platform, strong U.S. commercial growth, and continued government spending. While tough year-over-year comparisons may moderate growth, rising customer adoption and higher spending from existing clients could support revenue and earnings growth.
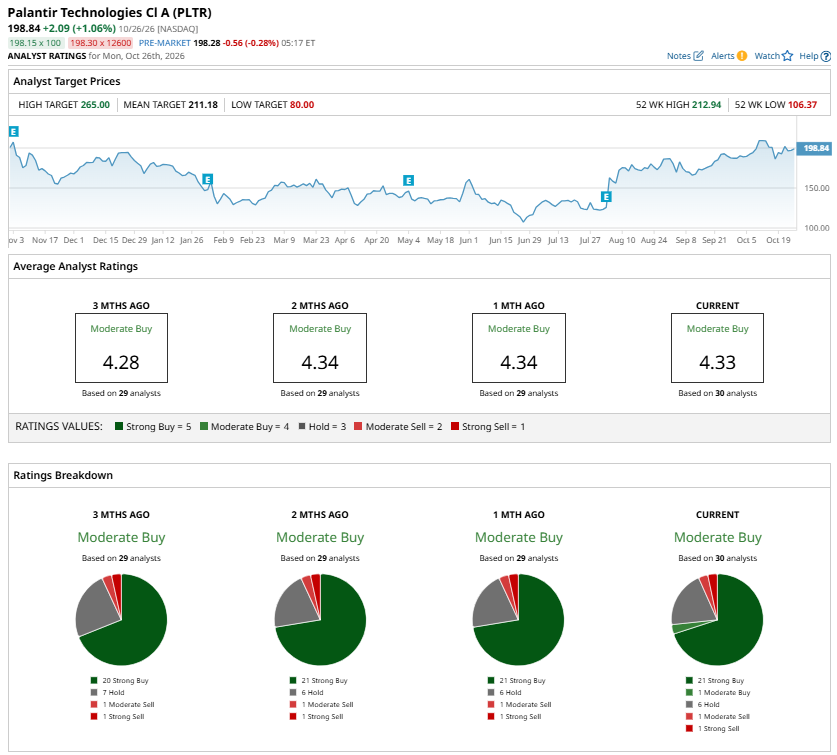
However, following PLTR’s sharp rally, the stock’s valuation appears high. Palantir is trading at a price-to-sales multiple of 105.3, significantly higher than peers. This explains why analysts are divided ahead of PLTR’s Q3 earnings release.
While the consensus rating is “Moderate Buy,” most analysts still rate it a “Strong Buy” ahead of the Q3 earnings release.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.