
What Verizon Communications (VZ)'s Earnings Beat Means For Shareholders
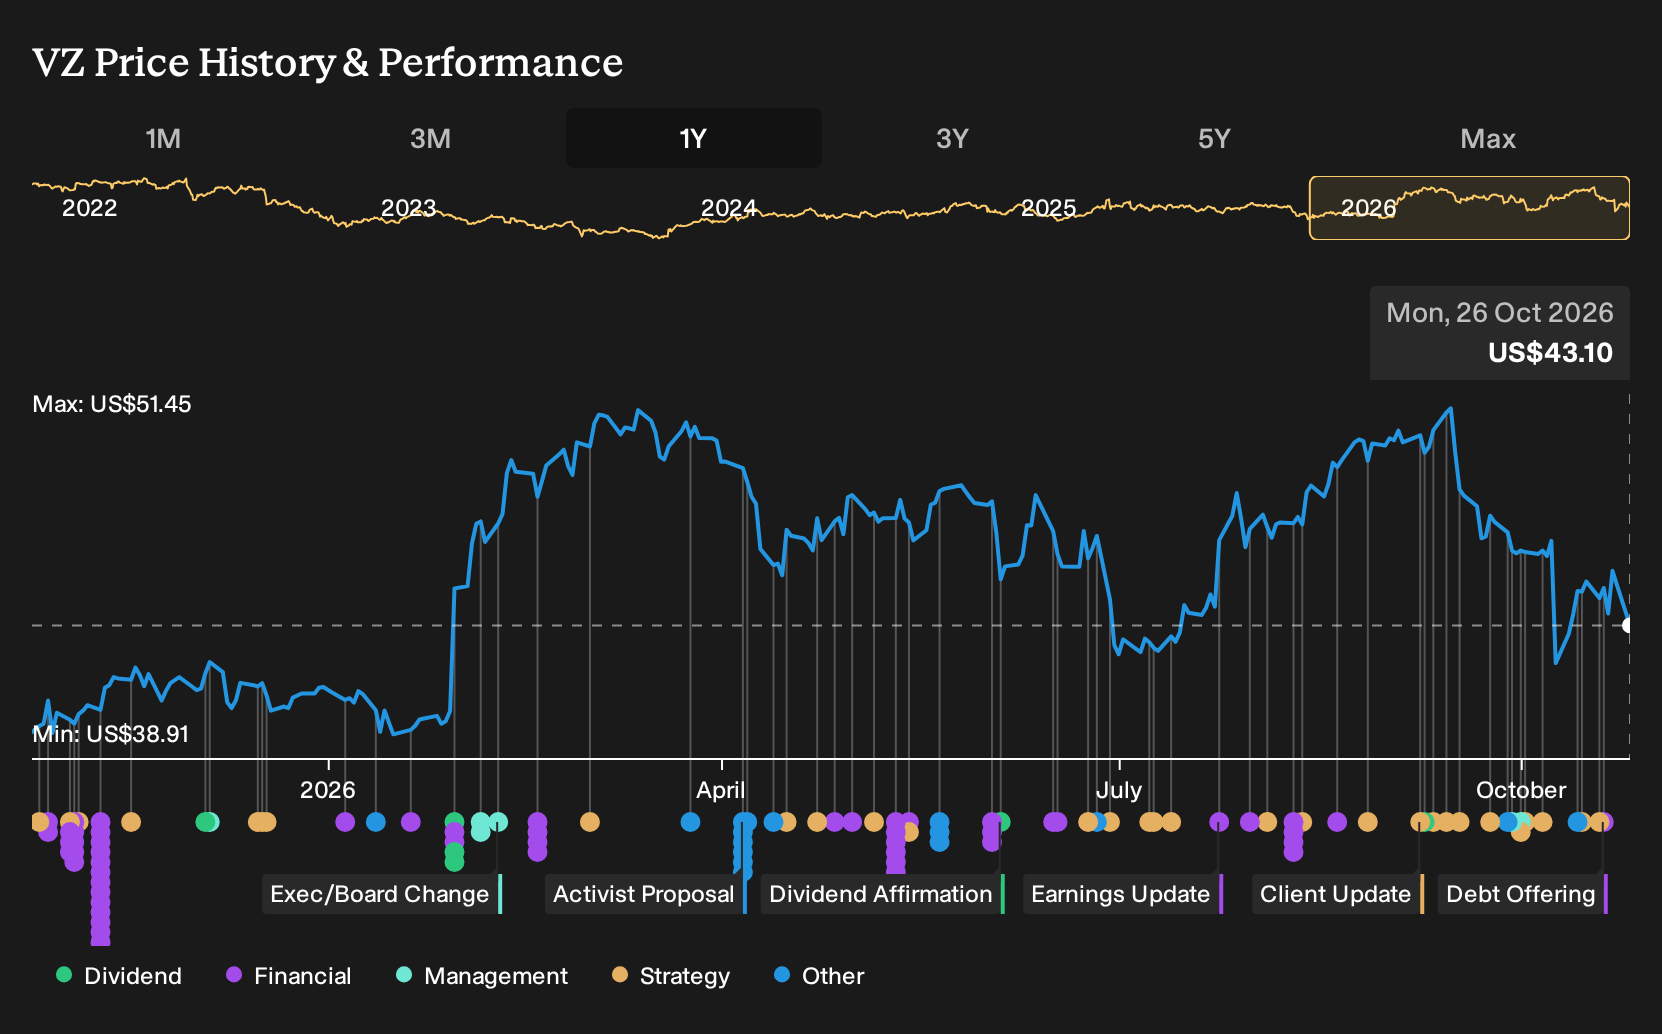
- Verizon Communications reported Q3 2026 revenue of US$34.31b and net income of US$5.20b, beat profit expectations, delivered its strongest third quarter for postpaid phone additions in five years, raised full year guidance, and announced an AI infrastructure agreement with Amazon Web Services worth more than US$2b.
- The sharp rebound in postpaid phone net additions and expansion of AI Connect and fiber contracts show Verizon Communications leaning harder into higher value recurring connectivity and enterprise data infrastructure, rather than relying on heavy device subsidies.
- Next, the focus will be how Verizon Communications’ raised guidance and multi billion dollar AWS AI deal reshape the longer term investment narrative.
Verizon Communications Investment Narrative Recap
To stay invested in Verizon Communications, you need to believe that recurring wireless, broadband and enterprise connectivity can carry earnings even as the US mobile market matures. The key short term catalyst is execution on customer growth and pricing under the refreshed plans, after Q3’s 406,000 postpaid phone adds and raised 2026 guidance. The biggest near term risk remains churn pressure if competitors lean harder into promotions, which could slow service revenue and squeeze margins.
Quarterly figures show Q3 2026 revenue of US$34.31b and net income of US$5.20b. Over nine months, revenue reached US$103.01b while net income was US$14.08b, slightly lower than the prior year. That mix means the latest beat on earnings per share sits alongside only modest top line progress, so the narrative still hinges on cost efficiency, capital discipline and turning large 5G and fiber outlays, plus AI Connect, into durable, higher margin cash flow.
The AI infrastructure agreement with Amazon Web Services, valued at more than US$2b, is the announcement that most directly connects to Verizon Communications’ evolving catalyst list. Management has already signed about US$4b of dark fiber and edge computing contracts across AI Connect. The AWS deal reinforces that enterprise connectivity and data infrastructure are becoming a more visible second leg next to consumer mobility.
For you as an investor, this matters because it tests whether big 5G, C band and fiber investments can attract long duration, higher value contracts rather than just more volume on a mature wireless base. The opportunity is a growing stream of recurring enterprise revenue. The risk is that these AI and private network projects stay niche relative to the size of the balance sheet, which would leave Verizon Communications more exposed to pricing pressure in core mobile and to its already high debt load.
Verizon Communications is currently modelled by analysts to reach US$147.7b in revenue and US$23.0b in earnings by 2029. This aligns with an assumed 2.1% yearly revenue growth rate and an earnings increase of about US$6.8b from roughly US$16.2b today.
Uncover why Verizon Communications' fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Verizon Communications using AI and cost cuts to widen margins, not just steady wireless demand. Before this earnings beat and the AWS deal, the bullish camp was already modelling revenue around US$151.3b and earnings near US$26.0b by 2029. Those forecasts could prove either conservative or aggressive once this quarter’s news is fully reflected, so treat them as one lens and explore a range of other viewpoints before deciding how this story fits your portfolio.
Explore 6 other Verizon Communications fair value estimates, including one that suggests potential upside of as much as 350% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Verizon Communications research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verizon Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verizon Communications' overall financial health at a glance.
Looking For More Investment Ideas Beyond Verizon Communications?
Once you have a view on Verizon Communications, it can help to widen the lens and compare it with other businesses that match your preferred mix of quality, risk and income. The Simply Wall St Screener is built for exactly that, letting you filter by fundamentals rather than headlines.
- If you want potential upside but still care about financial strength, start with a curated set of resilient companies in our 30 resilient stocks with low risk scores.
- If dependable cash flows matter most to you, focus on businesses that prioritise balance sheet resilience and earnings quality by checking the list of solid balance sheet and fundamentals (24 results).
- If you enjoy hunting for underfollowed opportunities, scan through a focused pool of sturdier lesser known stocks via the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com