
OHB (XTRA:OHB) Eu BEST Completion Puts Its Valuation Back In Focus
Why the Eu-BEST milestone matters for OHB stock
OHB (XTRA:OHB) just completed the EU funded Eu-BEST engine and stage testing project, commissioning a full scale modular test bench at its OHB Digital Connect site in Mainz.
Backed by €4.96 million from Horizon Europe and reviewed by senior European space agencies, the initiative highlights OHB’s role in shared test infrastructure for future launch vehicle systems.
That Eu-BEST update landed while momentum in OHB has been strong, with the share price up 8.70% over the last day, 25.70% over 30 days and an 82.19% share price return year to date, even though the 90 day move dipped 4.05%. Multi year total shareholder returns above 400% show how long term holders have been rewarded as sentiment has shifted around its role in European space infrastructure.
Scan for other space and infrastructure stocks showing similar momentum to OHB by reviewing our curated list of 610 high quality undiscovered gems in this corner of the market.
OHB has already delivered very strong multi year gains and a sharp recent jump, yet the current discount to analyst targets and intrinsic value estimates raises a blunt question: How much of the upside is actually still on the table?
Most Popular Narrative: 27% Undervalued
Against a last close of €225, the most followed narrative on OHB anchors fair value at €307, which frames recent share price momentum through a valuation lens rather than just hype.
Record order backlog of EUR 3.1 billion together with management guidance for strong revenue and EBITDA growth through 2026 indicates that current profitability is still absorbing upfront transformation and hiring costs. This leaves room for earnings and net margin expansion as efficiency programs and industrialization gains increasingly flow through the income statement.
See why 9 investors see OHB as 27% undervalued.
Result: Fair Value of €307 (UNDERVALUED)
Still, OHB’s heavy spending on new facilities and staff, along with the risk of lower European space and defense budgets, could quickly weaken that undervaluation story.
Find out about the key risks to this OHB narrative.
Another view on OHB’s valuation
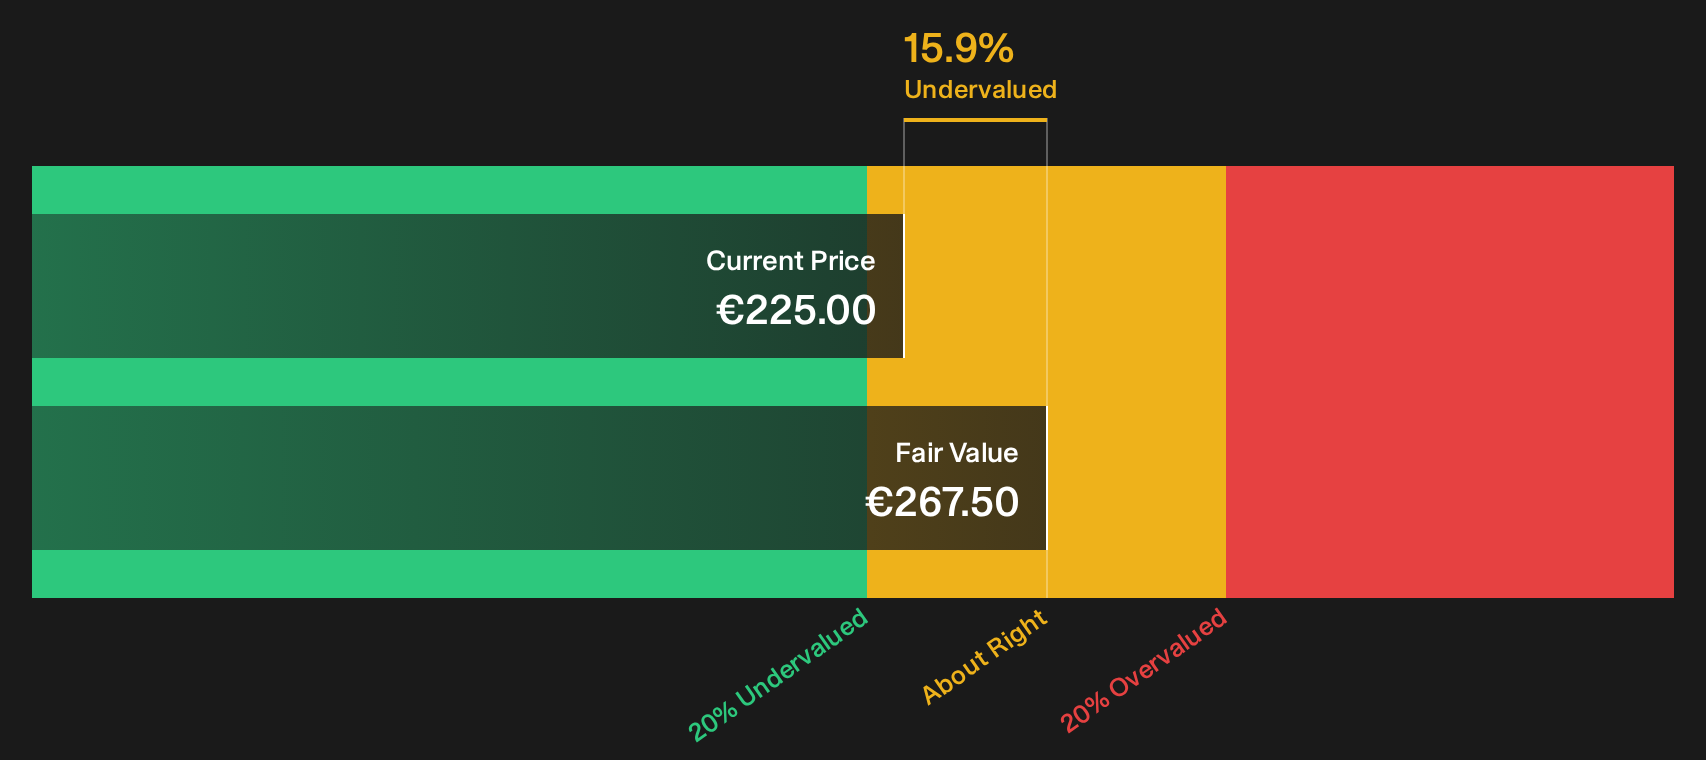
There is a clear split in how OHB is priced. On one hand, Simply Wall St’s cash flow model points to a fair value of €267.5, which sits above the current €225 share price. On the other, the market is paying a P/E of 106.6x, roughly double the estimated fair ratio of 54x and well above both European Aerospace & Defense at 30.4x and direct peers at 51.4x. For anyone watching OHB, the question is which signal carries more weight: cash flows or multiples?
To unpack how the cash flow view is built and what would need to happen for that gap to close, take a closer look at the SWS DCF workup, Look into how the SWS DCF model arrives at its fair value. which also maps that €267.5 estimate visually in the context of recent market pricing.
Next Steps
Mixed messages on OHB’s valuation and risk reward profile can feel messy. Move quickly from headlines to hard numbers and shape your own view by weighing its 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond OHB?
If OHB has sharpened your focus on quality opportunities, do not stop here. Use the tools available and keep your idea pipeline full.
- Target companies that combine strong fundamentals with attractive pricing by scanning our current pool of 195 high quality undervalued stocks before the crowd chases them.
- Prioritize capital protection and steadier potential outcomes by filtering for 223 resilient stocks with low risk scores that can help anchor your portfolio.
- Spot resilient balance sheets that can better handle shocks by reviewing the list of solid balance sheet and fundamentals (207 results) and upgrading your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com