
Q3 Results Could Change The Case For Investing In Smurfit Westrock Stock
- Smurfit Westrock released its Q3 FY2026 results on October 28 after several quarters of missing estimates, with the update arriving against a backdrop of tighter global containerboard supply, stronger pricing and a recently completed acquisition that is beginning to influence how the business is positioned across mills and converting operations.
- The key angle for investors is how this earnings report intersects with cost inflation, higher freight and energy bills and the integration of new assets. Together, these factors shape whether Smurfit Westrock can sustain EBITDA margins near its recent 14.2% Q2 level while still working through loss making contracts and mix upgrades.
- We will assess how Smurfit Westrock's investment narrative is affected by the Q3 earnings release and improving analyst expectations on pricing.
Scan how Smurfit Westrock compares to a hand picked list of solid balance sheet and fundamentals (24 results) that may be better positioned for cost inflation, freight pressures and tighter containerboard supply.
Smurfit Westrock Investment Narrative Recap
To own Smurfit Westrock, you need to be comfortable with a packaging group that is trying to turn tighter containerboard supply, higher prices and integration synergies into steadier margins. The near term hinge is whether operating performance around Q3 can stay close to the recent 14.2% EBITDA margin level while contract mix keeps shifting toward more profitable work.
The biggest swing factor right now is how freight and energy inflation flow through the income statement over the next few quarters. The key risk is simple. If Smurfit Westrock cannot offset these higher bills through pricing and self help, margin pressure and weaker cash generation remain on the table.
The recent acquisition and associated synergy plan is the announcement most tied to the current Q3 focus. Management has flagged at least US$400 million of identified synergies, which sets a clear execution test as these savings are tracked against rising freight and energy costs and the work to reduce loss making contracts.
For you as a shareholder, the important question is whether Smurfit Westrock can integrate the acquired assets, realise those efficiencies and refill North American capacity with better margin business before cost inflation bites too hard. Analyst optimism on earnings recovery in FY2027 sits in the background, but the real catalyst is operational delivery on these integration and pricing milestones.
Smurfit Westrock's current analyst narrative points to revenues of US$35.4b and earnings of US$2.2b by 2029. This outcome is based on forecast revenue growth of 4.2% per year and an earnings increase of about US$1.7b from US$497.0m today.
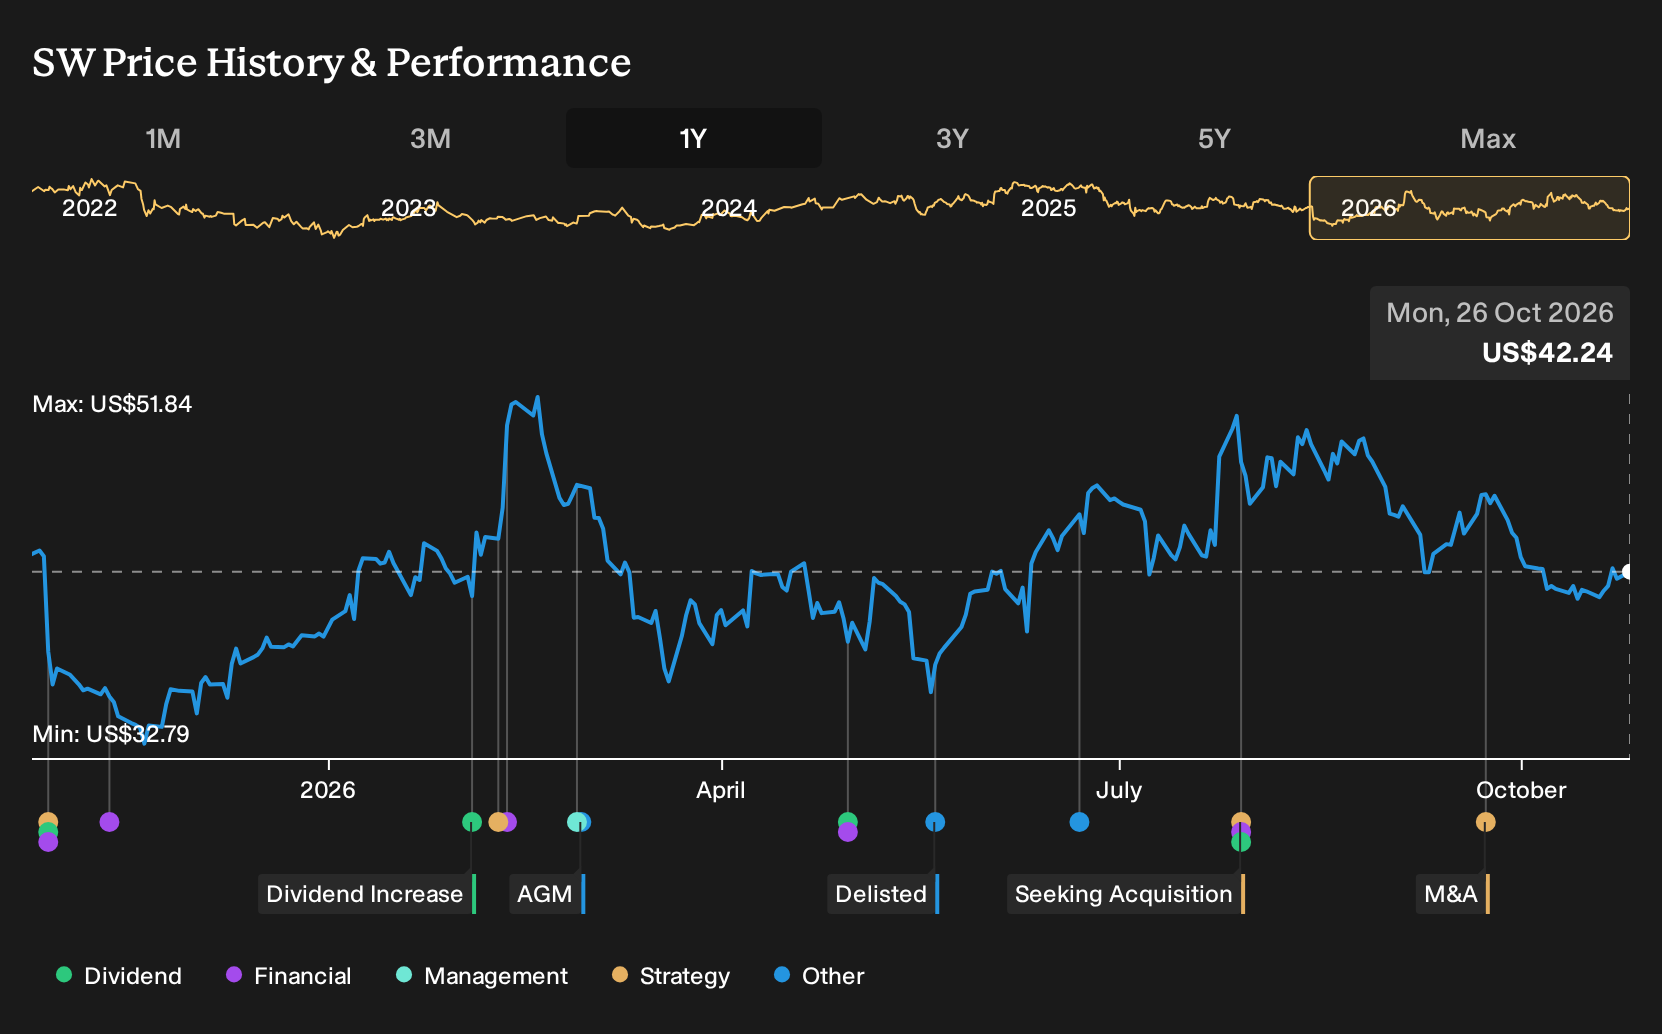
Uncover why Smurfit Westrock's fair value indicates a 34% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
The sharpest contrast comes from freight. Where the consensus for Smurfit Westrock leans on tight paper markets, the most bearish analysts focus on roughly US$300 million of higher freight costs and only 3.0% annual revenue growth assumptions toward about US$34.2b by 2029. Their pre‑Q3 view is far more cautious, and Q3 could reshape it.
Explore 3 other Smurfit Westrock fair value estimates, including one that suggests it could be worth just $47.14.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Smurfit Westrock research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Smurfit Westrock. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Smurfit Westrock's overall financial health at a glance.
Looking for more Smurfit Westrock style investment ideas?
If the Smurfit Westrock story has sharpened your thinking on balance sheets, pricing power and cash generation, it can be useful to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- If you want candidates that combine earnings strength with what our models judge to be appealing valuations, scan through 29 high quality undervalued stocks that might merit a place on your watchlist.
- For investors who care most about income stability, focus on companies in 5 dividend fortresses that offer higher yields while still clearing quality checks.
- If capital preservation and steadier fundamentals are a priority, start with 30 resilient stocks with low risk scores that our scoring framework views as having more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com