
Oil Refineries (TASE:ORL) Stock Dropped, What Is Driving Attention Now?
Renewed attacks on Russian refining infrastructure have pushed Oil Refineries (TASE:ORL) into sharper focus, as investors reassess how shifting refining margins and export flows might influence the group’s future cash generation.
In the short term, Oil Refineries’ share price has slipped, with a 1-day move down 3.82% and a 30-day share price return down 8.24% from ₪1.937. However, the year-to-date share price return of 96.25% alongside a 1-year total shareholder return of 122.99% indicates momentum built over a longer run, as investors weigh recent geopolitical headlines against several years of strong cumulative total returns of 131.39% over three years and 315.32% over five years.
Scan beyond Oil Refineries and compare how other energy-focused operators are priced on cash generation and risk profiles through our hand picked 195 high quality undervalued stocks.
Oil Refineries now trades at a sizeable discount to one estimate of fair value, even after the sharp multi year run and recent pullback. Is that a simple mispricing of cash flows, or justified caution on refining risk and geopolitics?
Price-to-Earnings of 5.3x: Is it justified?
On simple earnings terms, Oil Refineries looks inexpensive. The shares last closed at ₪1.94 while the stock trades on a P/E of 5.3x that compares against both regional and direct peer benchmarks.
The P/E ratio links what investors are willing to pay today to the profit the business currently generates per share. For a refiner and petrochemicals group like Oil Refineries, that lens is especially useful because earnings capture refining margins, one off items and the cyclicality of energy markets all in one number.
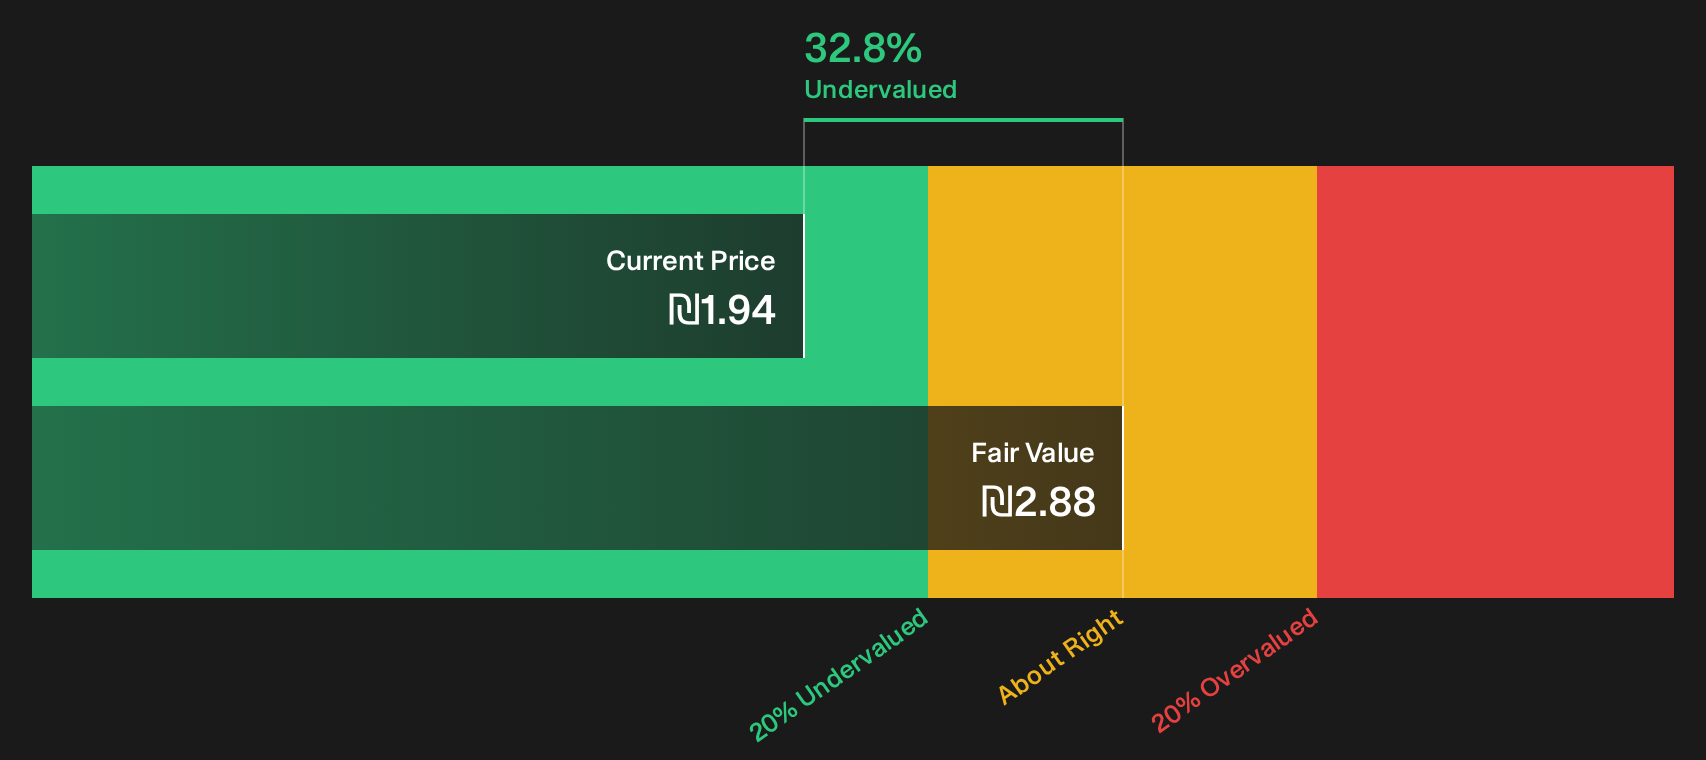
Context matters here. ORL is flagged as trading 32.8% below one estimate of fair value based on the SWS DCF model of future cash flows, and the group only recently moved back into profit after several years where earnings declined by 14.5% a year. That mix of a return to profitability, a low P/E and a DCF flagging a discount suggests the market may be pricing in meaningful risk around refining cycles, one off gains and balance sheet pressure rather than paying up for the current profit line.
The peer comparison is stark. ORL’s P/E of 5.3x is less than half the Asian Oil and Gas industry average of 11x, and far below the 15.8x peer average highlighted in the data. That is a strong relative gap and implies investors are assigning a steeper risk or cyclicality discount to Oil Refineries than to comparable operators.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 5.3x (UNDERVALUED)
Still, the refining-heavy mix at Oil Refineries and exposure to shallow water oil assets could quickly pressure earnings if spreads or operational uptime weaken.
Find out about the key risks to this Oil Refineries narrative.
Another View: What the SWS DCF Model Says About Oil Refineries
The valuation story looks different through the SWS DCF model. In this lens, Oil Refineries at ₪1.94 compares with an estimated future cash flow value of ₪2.88, which indicates an undervaluation of about 33% based on projected cash generation rather than reported earnings.
This gap suggests the market might be assigning a heavy discount to the sustainability of current cash flows, refinery exposure and one off items. It raises a simple question for investors: Is sentiment overshooting the risk, or is the cash flow curve less durable than it appears on paper?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oil Refineries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Oil Refineries is clearly split, with sharp gains over several years sitting alongside fresh questions about risk and resilience. Act quickly, review the data, and weigh both sides for yourself using our breakdown of 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Oil Refineries?
If Oil Refineries has sharpened your focus on value and risk, do not stop here. Broaden your watchlist using targeted stock ideas built from hard numbers.
- Target potential mispriced opportunities by scanning a curated pool of value candidates through the 195 high quality undervalued stocks.
- Strengthen your defense by focusing on companies with healthier finances using the list of solid balance sheet and fundamentals (207 results).
- Hunt for lesser known prospects that still clear quality bars with the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com