
A $1 Billion Reason to Consider Buying the IBM Stock Dip
Tech company International Business Machines Corporation (IBM) reported stronger-than-expected Q3 results, leading the company to expect robust results for the full fiscal year. For 2026, IBM expects 4%-5% revenue growth, supporting its decision to raise free cash flow growth expectations to more than $1 billion. Its software growth is projected to rise approximately 7%-8%, with about 7% as the revised base case.
However, IBM’s stock outlook isn’t all rosy. CEO Arvind Krishna’s comments that enterprises are scrutinizing AI spending returns and that lower-cost open-weight models are approaching frontier-model performance raised doubts about IBM’s pricing power and AI revenue potential. On the other hand, Krishna does not see this as a headwind. IBM may gain as businesses look to streamline operations, cut AI spending, and use the technology more effectively across their workflows.
Against this backdrop, let's take a closer look at IBM.
About IBM Stock
IBM, headquartered in Armonk, New York, is a global technology and consulting company serving clients in several countries. It operates through Software, Consulting, Infrastructure, and Financing segments and provides hybrid cloud, enterprise AI, data, cybersecurity, automation, and IT services. The company has a market capitalization of $239.65 billion.
IBM’s latest strategic focus centers on watsonx-based enterprise AI, hybrid-cloud modernization, and quantum computing, while expanding its software capabilities through acquisitions, including HashiCorp and a purchase of Confluent. The company is positioning itself as a provider of trusted AI systems, automation, and mission-critical digital infrastructure for businesses and governments.
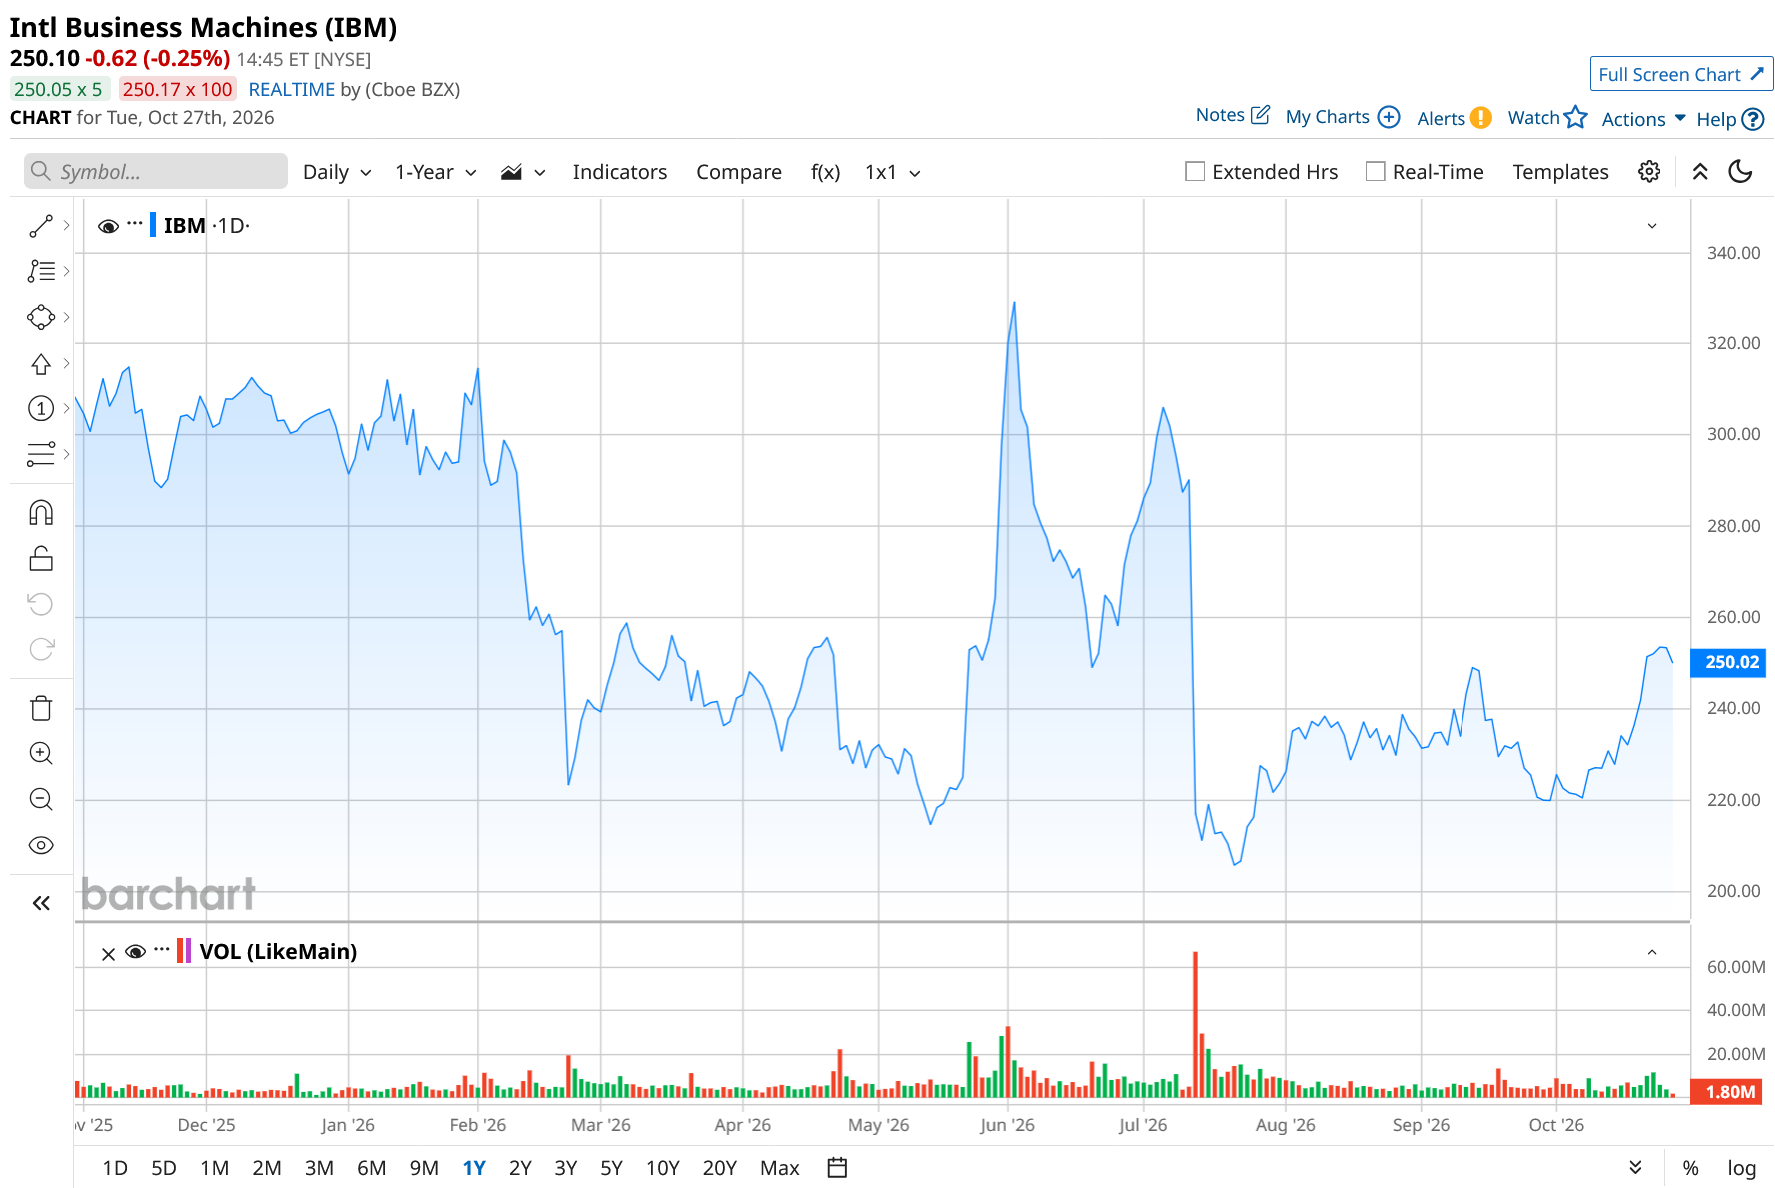
IBM stock has fallen 20% over the past 52 weeks and 15% year-to-date (YTD), mainly because investors lost confidence in the durability of its growth after a major second-quarter miss, even though the company later reported better Q3 results. However, the stock has gained 9% over the past month. It had reached a 52-week low of $199.19 on July 23, but is up 27% from that level.
On a forward-adjusted basis, IBM’s price-to-earnings (non-GAAP) ratio of 20.42x is slightly lower than the industry average of 21.60x.
Q3 Revenue, Profit Beat Estimates as Software Sales Rise
For the third quarter, IBM reported $17.1 billion in revenue, up 5% year-over-year (YoY), higher than the $16.87 billion Wall Street analysts expected. This was driven by software revenue up 8% YoY to $7.8 billion, due to gains in hybrid cloud and data revenue. However, consulting revenue remained roughly flat compared to the prior-year period at $5.3 billion.
However, IBM’s total gross profit margin dropped from 57.3% to 56.8% over the same period due to a broad-based drop in gross margins across all segments. Meanwhile, adjusted EPS rose 11% YoY to $2.95, surpassing the $2.88 analysts expected.
IBM ended the third quarter with $11.1 billion in cash, restricted cash, and marketable securities, down $3.4 billion from the end of 2025. It spent $11.4 billion on acquisitions this year. Total debt, including $12.7 billion of IBM financing debt, rose $2.6 billion YTD to $63.8 billion.
For the current fiscal year, Wall Street analysts project the company’s EPS to increase 7.1% YoY to $12.41, followed by a 6.7% improvement to $13.24 in the next fiscal year. Moreover, for the current quarter, EPS is projected to increase by 2.4% YoY to $4.63.
What Do Analysts Think About IBM Stock?
This month, analysts at Goldman Sachs raised IBM’s price target from $270 to $300, while maintaining a “Buy” rating. Analysts believe that IBM’s software beat and improving consulting trends point to stronger execution and a possible turning point in the business, which could help restore investor confidence. However, a lasting valuation re-rating will need more evidence of sustained growth.
Citi analyst Fatima Boolani raised the price target from $245 to $280, while keeping a “Buy” rating. Boolani cited IBM’s Q3 revenue growth led by infrastructure and software segments. The analyst also said about two-thirds of the mainframe deals that slipped from the second quarter were recovered, calling it a sign of “franchise stability.”
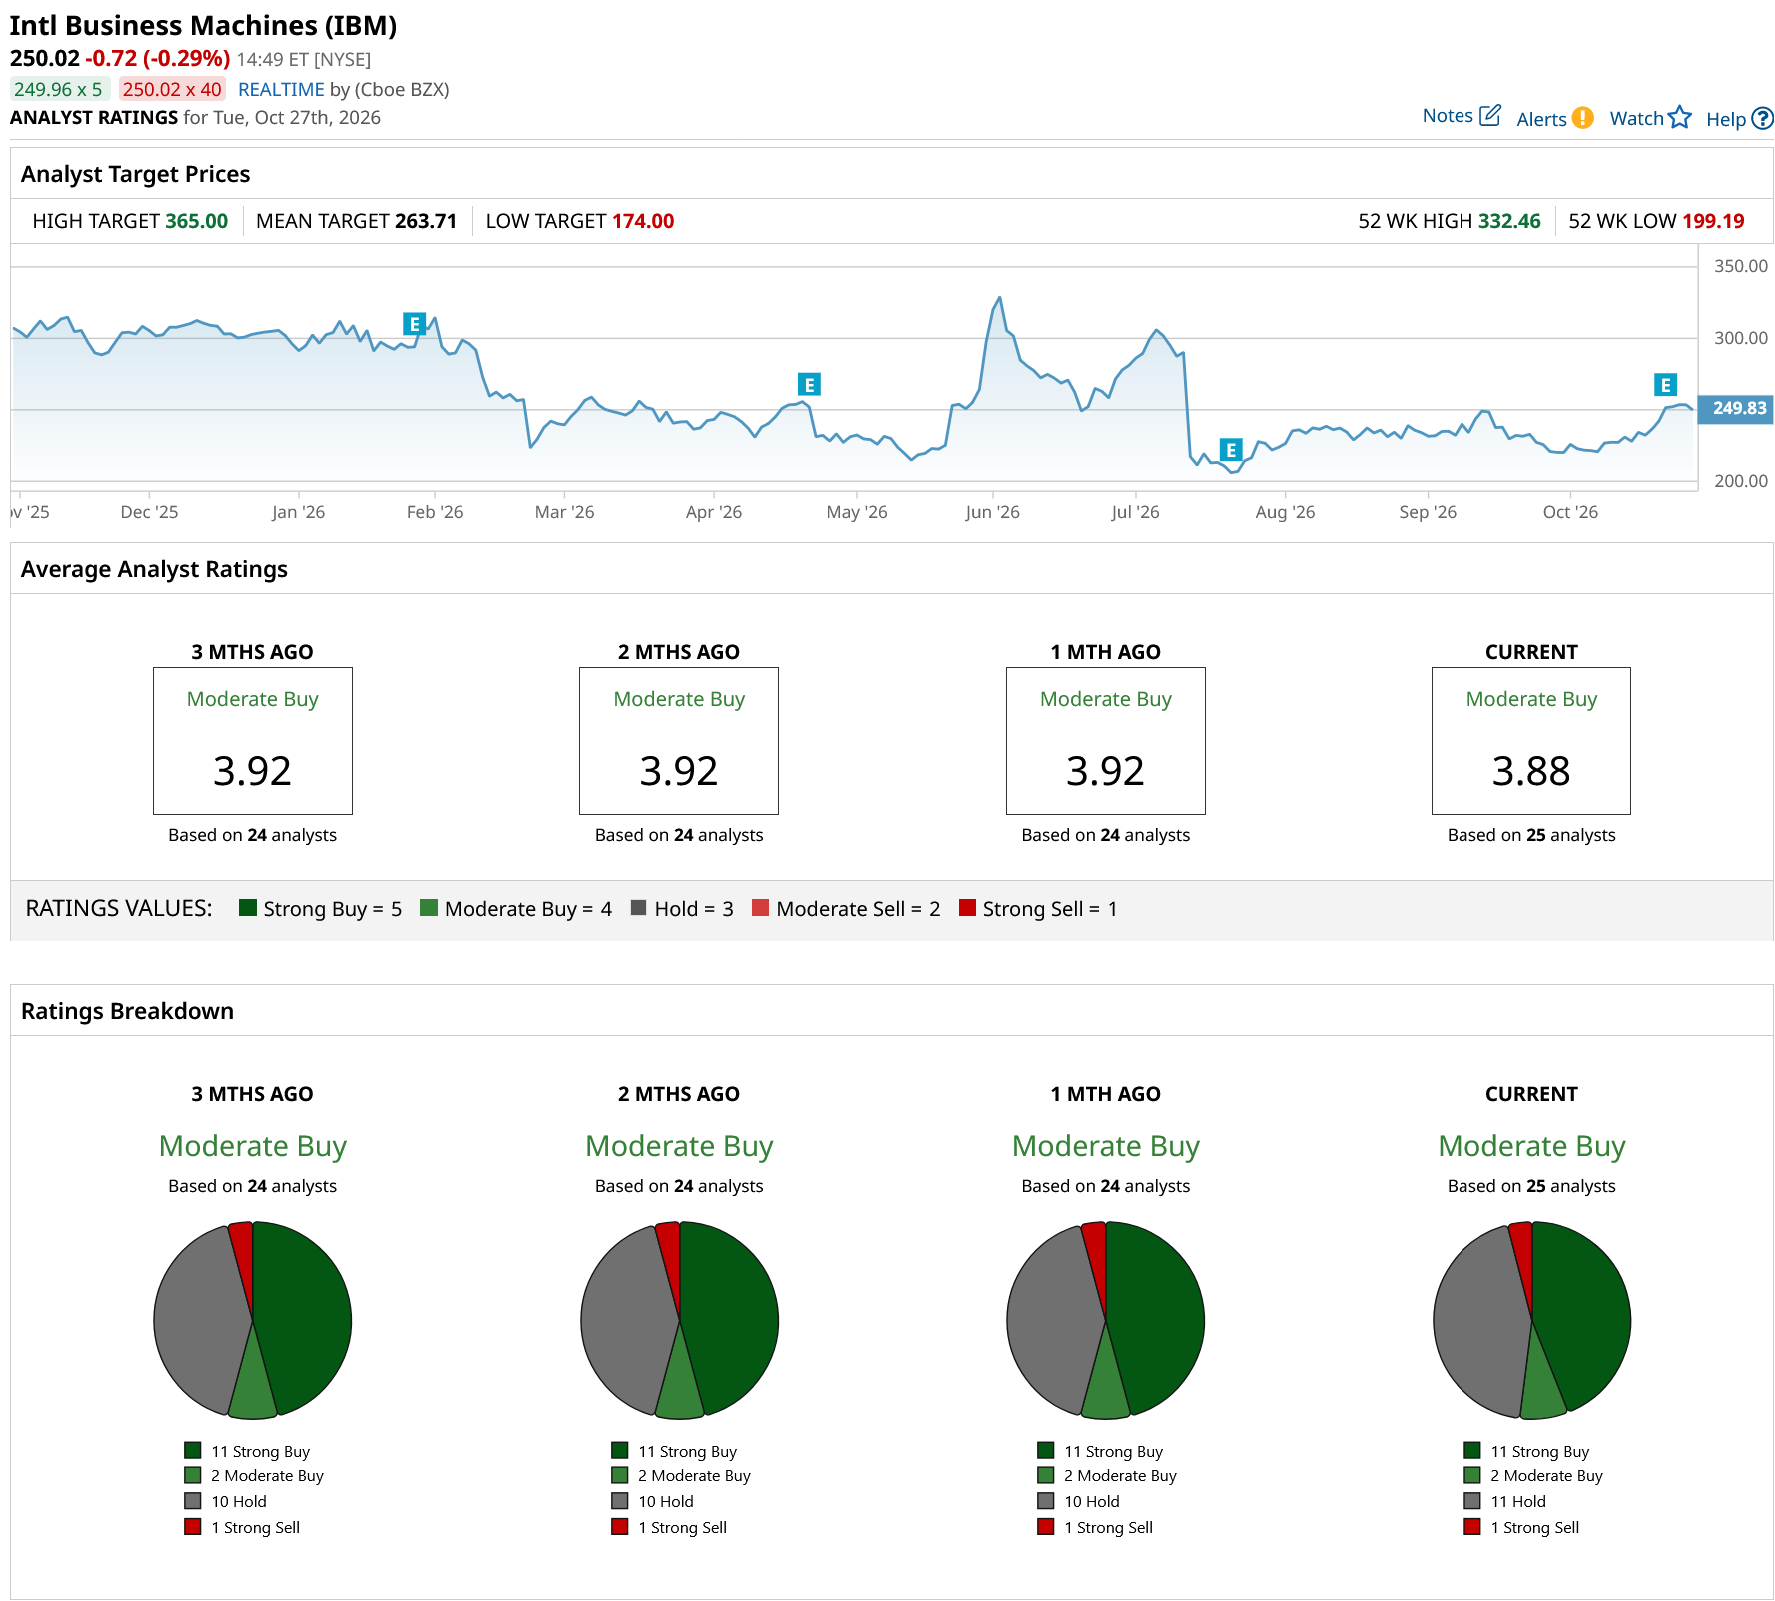
IBM has been in the spotlight on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating. Of the 25 analysts rating the stock, 11 analysts have rated it a “Strong Buy,” two analysts suggest a “Moderate Buy,” while another 11 analysts are playing it safe with a “Hold” rating, and one analyst gave a “Strong Sell” rating. The consensus price target of $263.71 represents a 5% upside from current levels. The Street-high price target of $365 indicates a 46% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.