
Unum Group (UNM) Holds Its Dividend As Undervalued Narrative Faces A Richer P E
Unum Group (UNM) reaffirmed its shareholder payout, with the board declaring a quarterly dividend of $0.505 per share, payable on November 20, 2026, to investors of record on October 30.
Unum Group shares trade at US$90.12, with the stock easing over the past month but still showing a 16.69% year-to-date share price gain and a 21.03% total shareholder return over the last year. This suggests momentum has cooled recently after a strong multi-year run.
Spot opportunities beyond Unum Group by scanning a curated set of income-focused insurers and other payout-heavy stocks in our 5 dividend fortresses.After such strong multi year returns and a recent pause around US$90, the key tension for Unum Group now is simple: Is meaningful upside still on the table or has most of the gain already played out on current valuation?
Most Popular Narrative: 11.5% Undervalued
On Simply Wall St’s most followed view, Unum Group screens as undervalued, with a fair value of $101.85 against the recent $90.12 share price. That gap rests heavily on how management handles long term care risk and pushes its digital tools deeper into the employee benefits franchise.
Unum Group’s ongoing work to shrink and reinsure its long term care block, including the additional US$3.8b of statutory reserves ceded and the reaffirmation that the remaining block is self supporting, keeps more capital and management focus available for employee benefits. This can support earnings stability and reduce pressure on net margins.
Continued investment in connected tools across the franchise, including high adoption of Agent Assist by Colonial Life’s more than 12,000 agents and broader digital links on about 70% of U.S. business, is improving distribution efficiency and service. This can support persistency, sales growth and operating margins.
See why 22 investors see Unum Group as 12% undervalued.
Result: Fair Value of $101.85 (UNDERVALUED)
Still, the story for Unum Group can change quickly if benefit ratios in group disability and life worsen or if long term care reserves face renewed strain.
Find out about the key risks to this Unum Group narrative.
Another View: What Multiples Say About Unum Group
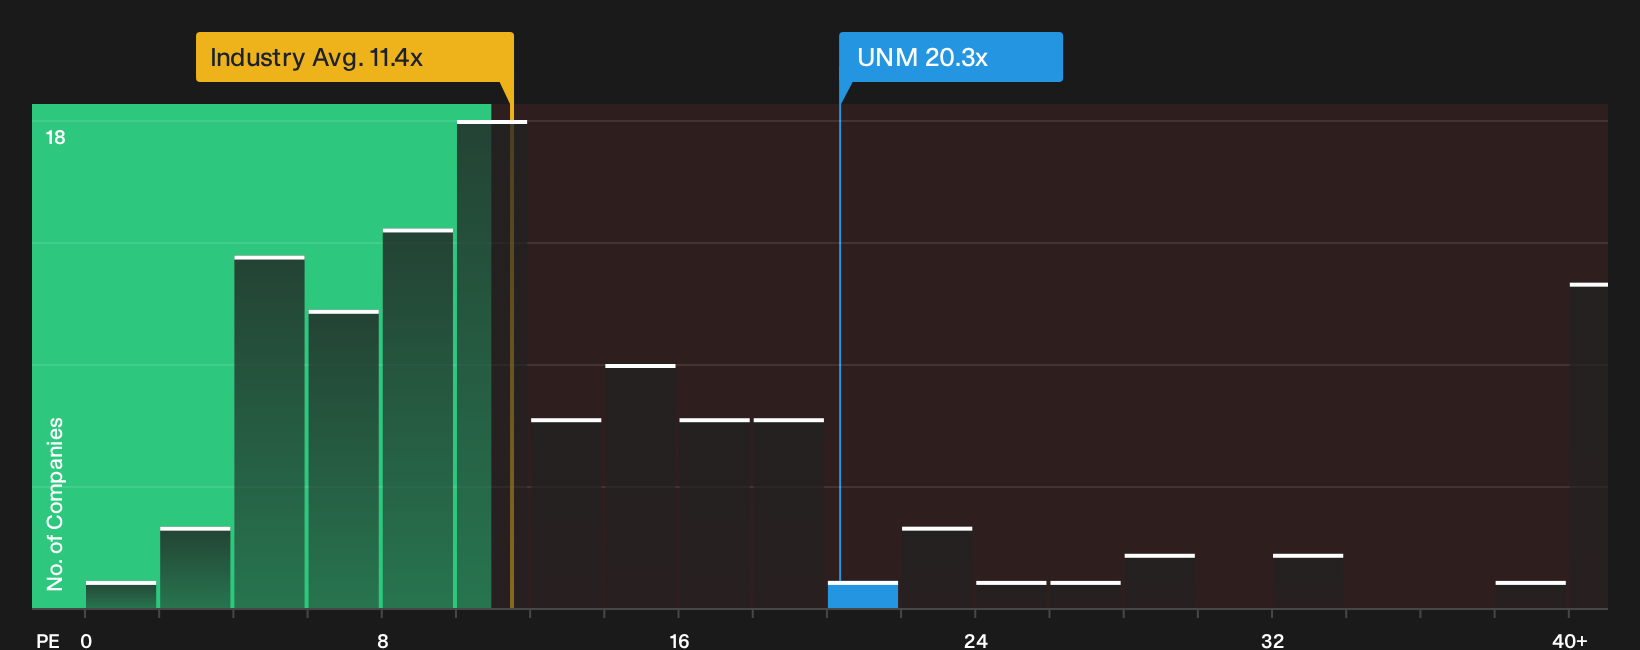
There is a different read on Unum Group when shifting from fair value models to simple market ratios. The shares trade on a P/E of 20.3x, above the US Insurance sector at 11.1x and above a fair ratio of 13x. That premium suggests less margin for error if expectations cool.
For investors comparing price tags rather than cash flow models, the question is whether Unum Group has earned that richer multiple, or whether an eventual move toward the lower fair ratio could compress returns from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Unum Group so far. If you want to move quickly and decide where you stand, consider both sides of the story through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Unum Group?
If you are weighing your next move after Unum Group, do not stop at a single ticker. Cast a wider net and let the data do the heavy lifting.
- Target dependable prospects by reviewing companies that combine strong financials with rock solid balance sheets through our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential bargains by scanning businesses that screen as high quality yet priced below their estimated worth using our 29 high quality undervalued stocks.
- Spot underfollowed opportunities by sifting through financially sound companies that attract less attention via our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com