
Is Flat Q3 Revenue Altering The Investment Case For Masco Stock (MAS)?
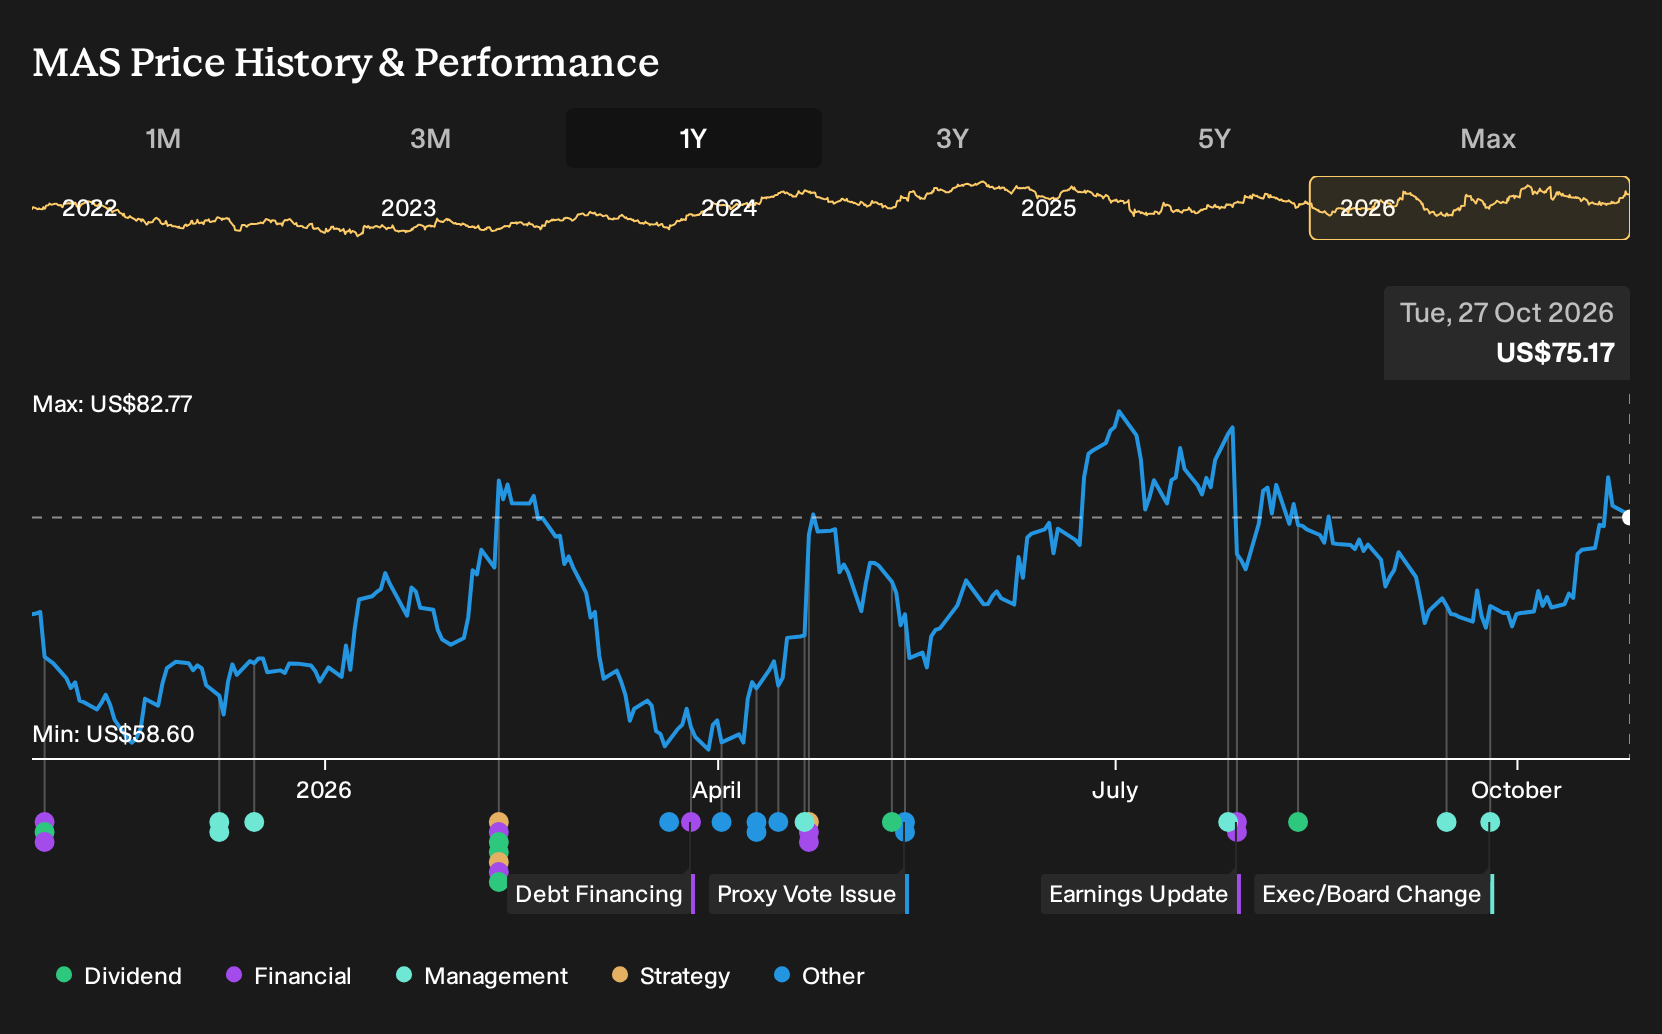
- Masco is set to report Q3 earnings after previously experiencing revenue declines and several missed Wall Street revenue estimates, with analysts now expecting flat year on year sales for the quarter.
- The shift from shrinking revenue to an expected stable top line, particularly as some building products peers reported stronger growth, puts Masco's execution and competitive position under closer scrutiny.
- This raises the question of how Masco's investment narrative is being tested by expectations for flat Q3 revenue following earlier quarters of decline.
Compare how Masco's flat Q3 revenue expectations stack up against peers by scanning a curated set of resilient building-product and housing-related stocks in our list of solid balance sheet and fundamentals (24 results).
Masco Investment Narrative Recap
For someone holding Masco, the core belief is that repair and remodel spending, premium plumbing and paint, and PRO channels can support steady earnings even when overall housing activity feels sluggish. The Q3 setup, with revenue expected to be flat after earlier declines, puts that resilience to the test but does not radically change the story on its own.
The near term swing factor is whether Masco can protect margins as input costs trend higher and tariff refund benefits fade. The biggest risk is that demand in North American repair and remodel stays soft while inflation in materials and tariffs compresses profitability more quickly than Masco can adjust pricing or cut costs.
Recent guidance around tariff refunds in the Plumbing segment matters most in this context. Masco has indicated that mid single digit input cost inflation in the second half of 2026 could offset those refunds, which makes a flat Q3 revenue outcome more about operating discipline than headline growth.
Investors now have to weigh Q3 against that backdrop. If tariff refunds prove temporary while materials inflation persists and volumes stay muted, earnings could rely more heavily on pricing, mix shift toward higher margin products such as Delta and BEHR, and ongoing efficiency programs to keep Masco on its margin targets.
Masco's current analyst narrative points to revenues of US$8.3b and earnings of US$996.4m by 2029, based on a 2.9% yearly revenue growth rate and an earnings increase of about US$111m from US$885.0m today.
Uncover why Masco's fair value indicates a 6% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Masco leans hard into Watkins Wellness as a potential growth spark. That bullish camp was penciling in 3.8% annual revenue growth and about US$994.1m in earnings by 2029 before this flat Q3 setup. You can use that more optimistic storyline as a reference point to judge how opinions may shift from here.
Explore 3 other Masco fair value estimates, including one that suggests up to 23% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Masco research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Masco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Masco's overall financial health at a glance.
Looking for more Masco-like investment ideas?
If Masco has you thinking about where else resilient balance sheets and dependable cash generation might show up, the Simply Wall St Screener can help you cast a wider net without drowning in noise.
- For investors who want stability first, filter for companies with low risk profiles and robust fundamentals through our 30 resilient stocks with low risk scores.
- If you are hunting for potential mispriced opportunities, focus on high quality businesses that look cheap on the numbers by using the 29 high quality undervalued stocks.
- Those looking for growing businesses that are not widely followed yet can scan for stronger fundamentals in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com