
Will Valkyrie Drone Progress Change Kratos Stock Narrative?
- Kratos Defense & Security Solutions recently broke ground on new Helios and AN/SPY-1 facilities in Indiana, funded by US$35 million from the Department of War’s IBAS program alongside cost sharing from the company, to expand radar, directed energy, and hypersonic testing capabilities.
- The combination of this industrial buildout with ongoing unmanned collaborations such as the U740-Valkyrie program and recent earnings outperformance reflects Kratos Defense & Security Solutions’ efforts to turn technology programs into larger scale production and testing capacity across radar, drones, and directed energy.
- We will now examine how Kratos Defense & Security Solutions’ new Helios and AN/SPY-1 complexes could influence the existing investment narrative.
Kratos Defense & Security Solutions Investment Narrative Recap
To own Kratos Defense & Security Solutions, you need to believe heavy spending on hypersonics, unmanned systems, and space infrastructure converts into sustained, higher margin production. The Indiana Helios and AN/SPY-1 buildout fits that story by adding specialized radar and directed energy capacity, although it does not change the near term picture on its own.
The key short term swing factor remains execution around hypersonic and unmanned program ramp, especially as Kratos manages FX headwinds, fixed price drone contracts, and cash tied up in working capital. If these pressures intensify or production timing slips, the investment case becomes harder to support at current expectations.
The U740 Valkyrie first flight with Airbus in Europe matters most in this context. It signals that Kratos Defense & Security Solutions is trying to move Valkyrie from concept into a system that can support scaled production for U.S. and international customers, alongside the planned Marine Corps demand described in recent commentary.
Combined with the Indiana facilities, that test flight points to a broader operating question for you as an investor: Can management synchronize capacity, supply chains, and capital spending so that hypersonic programs, tactical drones, and propulsion orders move from project phase into repeatable output without worsening margin pressure and cash burn?
Kratos Defense & Security Solutions’ current analyst script points to US$2.9b in revenue and US$180.6m in earnings by 2029. This outlook is built on an assumed 24.5% yearly revenue growth rate and an earnings increase of about US$149.7m, from US$30.9m today to that 2029 consensus level.
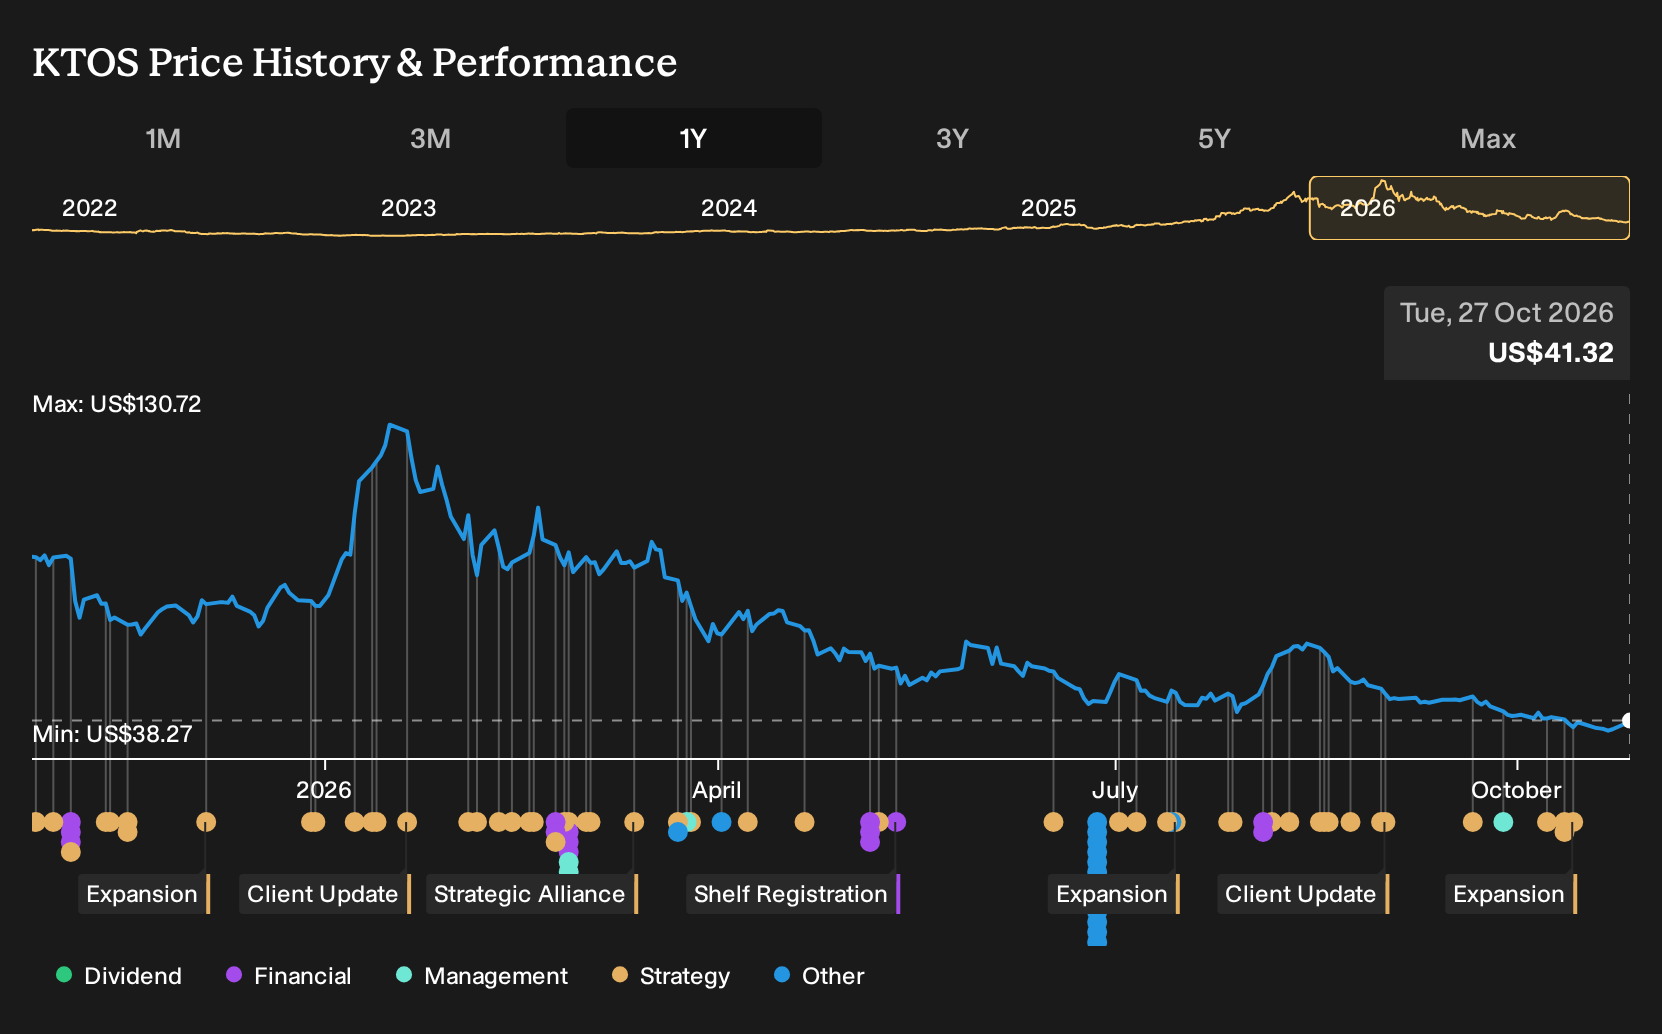
Uncover why Kratos Defense & Security Solutions' fair value indicates a 146% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats Kratos Defense & Security Solutions’ heavy capital spending itself as the main catalyst. The most optimistic analysts were already penciling in US$3.4b of 2029 revenue and US$274.3m of earnings before this Indiana build started. It is likely that both bullish and cautious narratives will evolve as the new facilities come into focus.
Explore 4 other Kratos Defense & Security Solutions fair value estimates, including one that suggests up to 271% potential upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kratos Defense & Security Solutions' overall financial health at a glance.
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
If you want to cross check the Kratos Defense & Security Solutions thesis against other potential opportunities, the Simply Wall St Screener can help you quickly filter the market by quality, value, and risk so you are not relying on a single defense stock to carry your portfolio.
- If capital preservation is front of mind, start with resilient businesses through a 30 resilient stocks with low risk scores that screens for companies with lower overall risk scores.
- If you prefer potential value opportunities, compare Kratos Defense & Security Solutions with a 29 high quality undervalued stocks built around companies that pair strong fundamentals with more modest pricing.
- If balance sheet strength matters most to you, focus on financially robust issuers using a list of solid balance sheet and fundamentals (24 results) that highlights companies with sturdier capital structures and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com