
Lakeland Financial (LKFN) Stock Drifts As Q3 Earnings Back Dividend Confidence
Lakeland Financial stock slipped 0.8% to US$60.71 after the Q3 2026 earnings release, a muted move for a regional bank that just posted another solid profit print. Basic earnings per share landed at US$1.15 and net interest margin came in at 3.58%, numbers that keep this franchise firmly profitable even as the sector wrestles with funding costs.
Short term traders are reacting to a modest price dip. Long term holders are more likely focused on the bigger question: whether a 40.8% trailing net profit margin and a 3.43% dividend justify staying patient through the next rate cycle.
Like Lakeland Financial’s steady net interest margin but uneasy about concentration risk in a single regional bank stock? Compare it with peers from our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$71.80m vs. US$67.03m (up about 7.1%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$28.86m vs. US$26.40m (up about 9.3%)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.15 vs. US$1.03 (up about 12.2%)
- Net Interest Margin (Q3 2026 vs Q3 2025): 3.58% vs. 3.50% (slightly higher, indicating a firmer spread on earning assets)
Earnings jumped faster than Lakeland Financial’s five-year trend. Ask Charlie what makes Lakeland Financial’s earnings growth look sustainable.
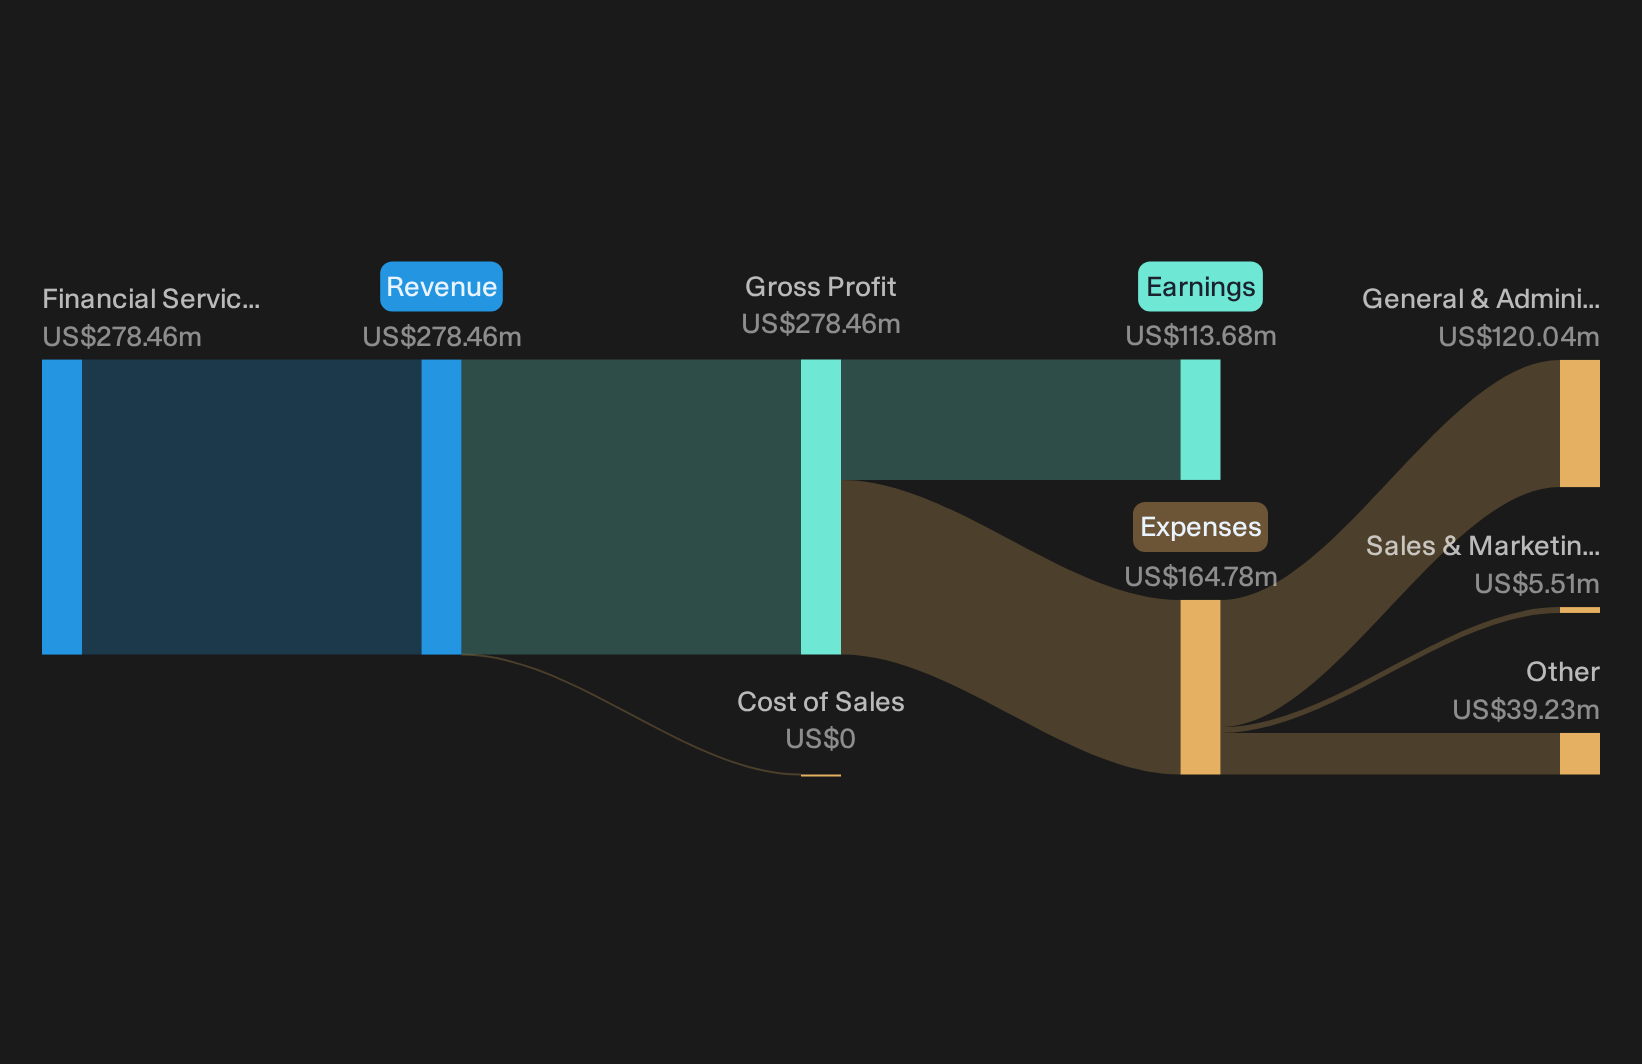
Lakeland Financial’s earnings momentum supports patient bulls
For investors leaning positive on Lakeland Financial, the latest quarter largely backs that stance. Revenue of US$73.0m and total revenue of US$71.80m both move in the same constructive direction as net income, which reached US$28.86m. Basic EPS of US$1.15, alongside diluted EPS of US$1.14 and a 4% dividend increase to US$0.52, points to management acting with confidence in the earnings engine. A firmer 3.58% net interest margin adds weight to the idea that this regional banking model is still generating healthy spread income.
Short term share softness leaves room for caution
Bears will point to a share price that slipped 0.75% on the day and remains down about 4.1% over 90 days. That muted reaction, despite record Q3 results and higher dividends, suggests some investors are still wary of regional bank risk or future credit costs. The modest 7 day and 30 day gains of 3.6% and 2.0% show sentiment improving only gradually. For now, the financial print does not erase sector concerns, but it also does not confirm a sharp deterioration in Lakeland Financial’s business model.
Reveal where the calm surface on Lakeland Financial’s current share price starts to crack by checking what the street is quietly penciling in for margins, credit costs, and dividends over the next few years. Access the full analyst estimates for Lakeland FinancialHunt For Quiet Price Disconnects
Lakeland Financial just reported steady results and a relatively muted share reaction that leaves investors weighing possible mispricing. The real opportunity could be assessing stocks that appear undervalued before sentiment and attention potentially adjust.
- Company 1 - 46% below our estimate - convert a record backlog of data center and modular construction projects into installation and service revenue.
- Company 2 - 15% below our estimate - ride a growing pipeline of hyperscale data center builds across communications, infrastructure solutions and commercial contracting operations.
- Company 3 - 42% below our estimate - win larger digital display and software projects as venues, advertisers and transport networks upgrade to real time visual communication.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com