
What Knorr Bremse Holders Saw Early
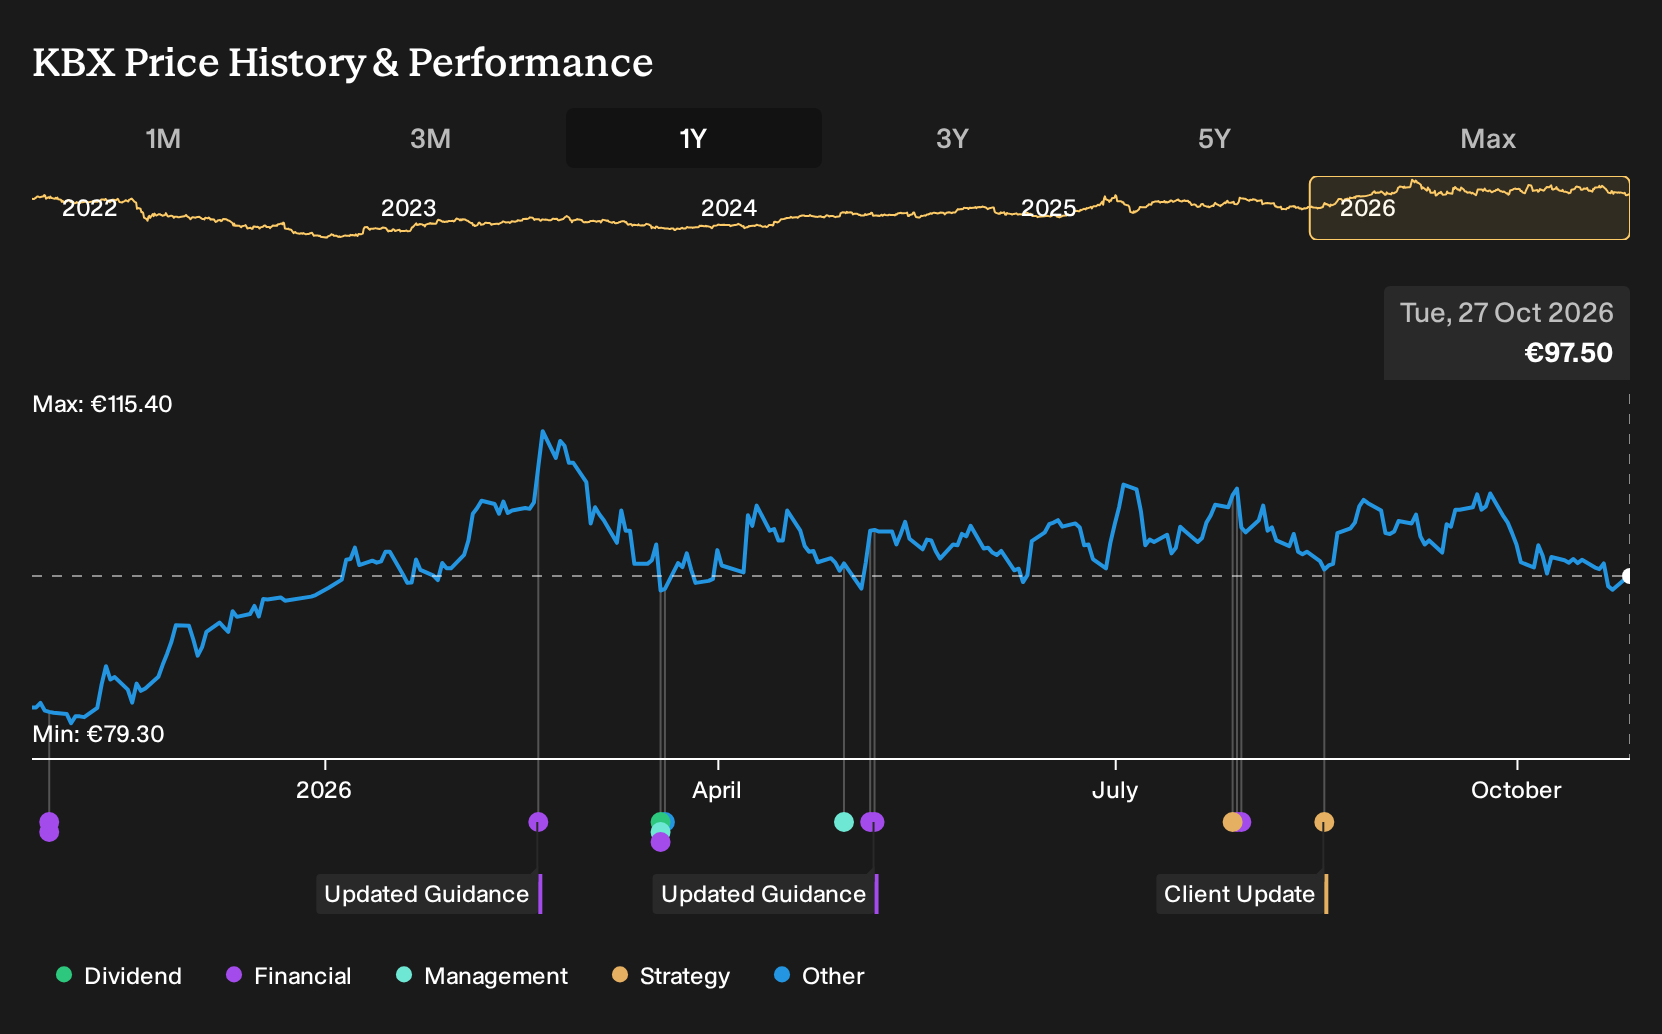
Knorr-Bremse had no shortage of headlines during the period, and one concrete marker was the decision to raise the 2025 dividend to €1.90 per share, paired with a refreshed Supervisory Board that added a digitalization specialist. For Knorr-Bremse shareholders, the return over the past year was 21.5%, including dividends. If you were weighing a purchase on 27 October 2025, what would you have needed to believe before any of that news was released?
This theme extends beyond Knorr-Bremse. See which of 42 power grid technology and infrastructure stocks may still merit a closer look.
The Argument Knorr-Bremse Investors Were Really Having
The shares cost €81.25 at the start of the period, and the debate around Knorr-Bremse turned on two very different views of what that price already assumed.
The bullish storyline pointed to a Fair Value of €104, a rough guide to what the price might reach if faster digital growth played out. This view was built on expectations of 6.8% annual revenue growth and profit margins rising from 5.3% to 11.0% by 2028.
The bearish view anchored on a Fair Value of €65, tied to a slower 3.8% revenue path and concern that rising R&D and supply chain costs could keep margins nearer 10.2%.
What The Knorr-Bremse Results Actually Tested
Knorr-Bremse’s Q2 2026 report gave the clearest signal. Revenue moved from €2,022m in Q2 2025 to €2,164m, while net income rose from €140m to €173m and net margin improved from 6.9% to 8.0%. That combination of higher sales and a thicker margin supported more of the bullish case for stronger profitability, even though one year of data did not settle the multi year argument.
The useful takeaway is simple. When a story hinges on margin expansion, you check the reported net margin trend and the gap versus the original assumption, quarter by quarter, before treating any Fair Value pitch as realistic.
What Knorr-Bremse’s Recent Run Now Asks You To Believe
Knorr-Bremse trades at €97.5 today, after gaining 21.5% over the past year. The selected Narrative sees Fair Value as higher than that current price, based on how profit mix and cash generation might evolve.
That argument hinges on Knorr-Bremse keeping EBIT margins high while rotating out lower return activities into signaling, electronics and energy technologies. The key question for a buyer now is whether those margin and portfolio moves can keep working at roughly their recent pace.
"The current valuation implies the share price does not fully reflect the company’s delivery on EBIT margin uplift, strong free cash flow generation, portfolio reshaping toward higher-margin activities, and formal 2030 targets for margins and returns on capital."
The price and this Narrative do not agree. → Uncover what this Narrative says Knorr-Bremse is actually worth
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - targets expanding device trade-in activity as policies and recycling incentives evolve.
- Company 2 - 40% below our estimate - layers agentic AI functions onto subscription tools to deepen and broaden customer engagement.
- Company 3 - 46% below our estimate - converts a large project backlog into cash while resolving complex, legacy contract disputes.
Three companies from the same screener. Open the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com