
3 Stocks to Watch After Anthropic IPO Put AI Liability in Focus
Anthropic’s IPO filing did more than add another AI pure-play to investors’ watchlists. It shoved AI risk, governance and legal liability into the spotlight, right as regulators and customers are paying closer attention to who is managing the messy side of powerful models. That shift creates a potential opening for stocks exposed to this news. This article walks through three such companies worth understanding now.
The stocks covered below are just a sample set, and the full screen surfaced 50 more listed businesses with similarly strong AI governance, compliance and liability narratives that are not discussed here. If you want to identify potential opportunities for your own watchlist, head straight to the AI Governance, Compliance, and Liability Services screener to filter and analyze this broader group of candidates.
NSFOCUS Technologies Group (SZSE:300369)
NSFOCUS Technologies Group is an internet and application security specialist. Its DDoS defense, threat monitoring and exposure management tools align closely with the screener’s focus on cybersecurity and AI-related governance risks. Almost all reported operating revenue, about CN¥2.55b, comes from its Information Security Industry segment, and the group is valued at roughly CN¥9.61b.
For investors focused on AI governance and legal risk, NSFOCUS Technologies Group offers pure-play exposure to DDoS protection, threat intelligence and security operations that directly address concerns raised in Anthropic’s risk-heavy IPO filing. The business combines this thematic link with improving loss metrics and a meaningful role in strengthening the infrastructure that AI depends on, depending on how one unseen pressure plays out.
That unseen pressure matters for your thesis, so scan the 3 key rewards and 1 important major warning sign to see whether NSFOCUS Technologies Group’s AI security upside outweighs its legal overhang.
Parsons (PSN)
Parsons Corporation builds and runs secure digital systems for governments and critical infrastructure, which naturally puts it in the AI governance and compliance conversation as those customers demand tight controls around data, monitoring and legal risk in new deployments.
Parsons generates about US$3.09b of annual revenue from Federal Solutions and roughly US$3.2b from Critical Infrastructure, and the stock is valued at around US$5.3b.
For investors watching how AI risk disclosures at firms like Anthropic ripple into real world contract work, Parsons offers a concrete test case in regulated, high stakes environments where compliance is not optional and software, engineering and advisory services are bought as a package rather than as isolated tools.
"Scaling of Parsons’ AI enabled product portfolio, with roughly $350 million of expected 2026 product revenue and a plan for 20% to 30% growth in 2027 at margins above the corporate average, gives the company room to shift mix toward higher margin, more repeatable revenue and potentially lift earnings quality beyond what contract services alone imply."
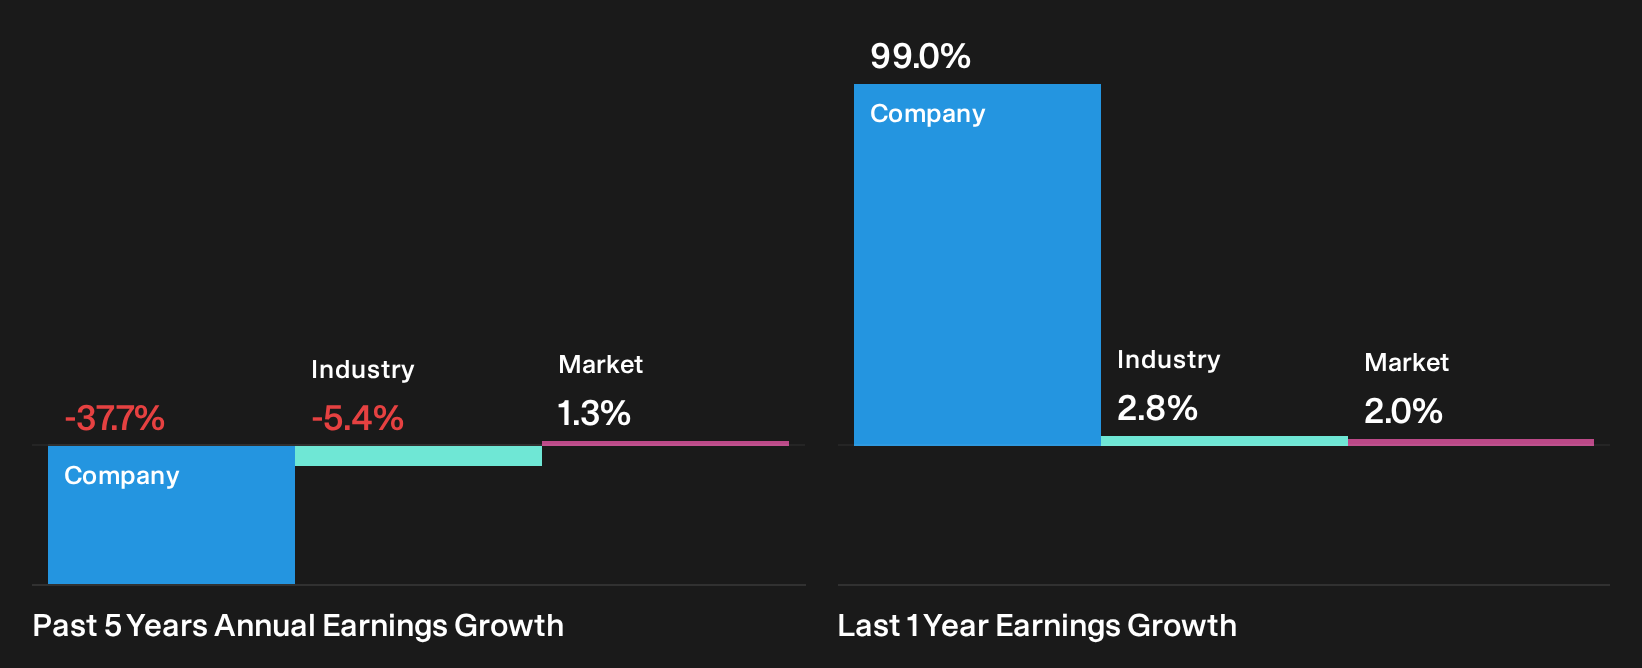
The real hinge for Parsons is how fast that shift toward higher margin, repeatable products can reshape earnings, before funding or contract timing pushes in the other direction.
Before contract timing pulls too hard in either direction, read the full narrative for Parsons to see how Parsons’ product shift could decouple earnings from funding cycles.

LegalZoom.com (LZ)
LegalZoom.com plugs straight into this AI governance screen because it already handles everyday legal and compliance chores for small businesses, which positions the platform to package AI related policies and liability terms as just another standardized legal workflow.
"Accelerating adoption of online legal and compliance services through partnerships with platforms such as USAA, AAA, PayPal, Adobe, LinkedIn, Chase, and GoDaddy, alongside integrations with AI assistants like ChatGPT, Claude, Copilot, and Perplexity, is expanding LegalZoom.com brand reach and can support future revenue growth."
What really matters now is how one emerging pressure on its mix of high margin subscriptions and human in the loop services reshapes long term earnings quality.
LegalZoom.com runs a digital hub for business formation and consumer legal work, earning about US$792 million from its online platform while selling subscriptions for compliance and ongoing advice, and the stock is valued at roughly US$1.2b.
That mix shift pressure is exactly what the full narrative for LegalZoom.com unpacks, highlighting where LegalZoom.com’s model could accelerate, stall, or quietly rebuild earnings power.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the cleanest breakout stories rarely stay under the radar for long. Scan these fresh stock ideas before the crowd catches up and consider your options.
- Spot strong cash generators early and track them with the 195 high quality undervalued stocks that surfaces financially robust businesses still priced as if momentum has not arrived yet.
- Ride structural demand in critical materials by checking the curated 16 top copper producer stocks packed with producers tied to long term electrification and grid build out themes.
- Zero in on resilient payers and use the 224 dividend fortresses to focus on companies combining meaningful yields with balance sheets built to sustain distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com