
Boise Cascade (BCC) Following Loop Capital Downgrade Looks Cheap Or Fairly Valued
Boise Cascade (BCC) came into focus after Loop Capital shifted its rating from Buy to Hold and reduced its projected valuation range, drawing new attention to how the stock trades relative to its fundamentals.
Recent trading shows that Boise Cascade has given back some momentum, with a 30-day share price return of 1.45% and a 90-day move down 2.14%. The 1-year total shareholder return of 6.28% and 5-year total shareholder return of 56.63% point to a mixed but still constructive longer-term record around the current US$76.02 level as investors digest the downgrade and reassess risk and growth expectations.
See how Boise Cascade compares to other construction linked plays that are under pressure from fresh analyst calls by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Boise Cascade now trades meaningfully below both analyst targets and one estimate of intrinsic value, yet the downgrade hints at real concern. Is the discount a bargain or a fair warning about risk?
Price-to-Earnings of 25.1x: Is it justified?
On a simple earnings lens, Boise Cascade carries a P/E of 25.1x. This sets a clear reference point for the current $76.02 share price against both peers and its own fundamentals.
The P/E ratio links what investors are paying today to the most recent earnings per share. For a materials distributor and wood products manufacturer like Boise Cascade, this matters because profits can be cyclical, so the multiple often reflects how investors weigh recent earnings against expectations for future profitability.
Analysts expect Boise Cascade's earnings to grow 29.4% per year, compared with the broader US market forecast of 17.1% per year. That forecasted earnings improvement can help explain why the market is willing to pay 25.1x earnings even though current net profit margins are 1.6%, below last year's 4%, and earnings have declined by 28.7% per year over the past 5 years.
Against the US Trade Distributors industry average P/E of 24.4x, Boise Cascade trades at a slightly richer multiple. It looks cheaper, however, compared with a much higher peer group average of 80.8x. The estimated fair P/E of 29.9x also sits above the current 25.1x, which suggests the market could move toward a higher earnings multiple if forecasts play out.
Explore the SWS fair ratio for Boise Cascade.
Result: Preferred multiple of 25.1x price-to-earnings
Still, a 3 year total shareholder return that declined 9.55% and net profit margins at 1.6% leave Boise Cascade exposed if construction demand softens or pricing pressure builds.
Find out about the key risks to this Boise Cascade narrative.
Another view on Boise Cascade’s value
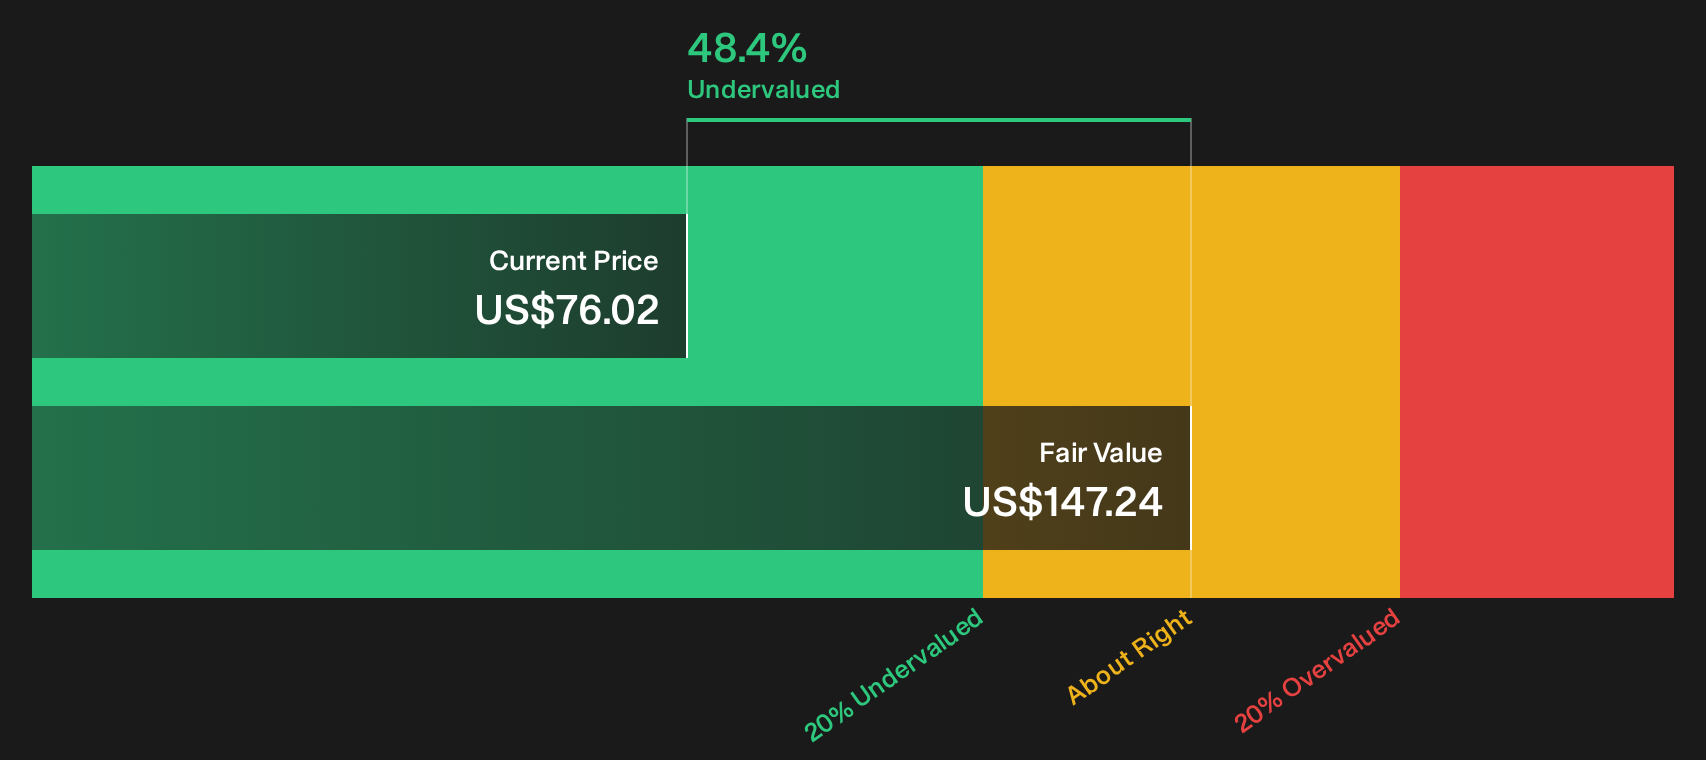
The earnings multiple hints at one story for Boise Cascade, yet the SWS DCF model tells a different one. At $76.02, the shares are described as trading 48.4% below an estimated future cash flow value of $147.24, which frames the current price as materially discounted.
That type of gap can reflect opportunity if the cash flows arrive as projected, or it can signal that the assumptions in the model are too optimistic. For an investor weighing Loop Capital's downgrade against this DCF output, the key question is which signal deserves more weight.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boise Cascade for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Boise Cascade can feel confusing, so consider the same data, weigh the concerns and potential upsides, and shape your own stance with our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Boise Cascade?
Do not stop with Boise Cascade. Use the same disciplined approach to scan wider markets, compare fundamentals fast, and pressure test where your next dollar should go.
- Target quality at a discount by reviewing the 29 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- Lock in potential income streams by assessing the 5 dividend fortresses that offer higher yields with a focus on stability.
- Dial back portfolio risk by scanning the 30 resilient stocks with low risk scores that pair resilient balance sheets with more measured volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com