
Coty (COTY) Sustainability Push Is Back In Focus As Fair Value Questions Linger
Why Coty’s latest sustainability update is back in focus
Coty (COTY) is in the spotlight after releasing its 2025 Sustainability Report, which centers on cutting virgin plastic use, reducing water consumption, and refreshing climate targets across its beauty portfolio.
Coty’s 24.15% 30 day share price return and 20.51% 90 day gain suggest improving momentum, even though the 1 year total shareholder return declined 18.16% and the 5 year total shareholder return fell 62.14%. Investors appear to be reacting to the fresh sustainability commitments alongside branded partnerships such as the multi year BOSS PARFUMS and HYROX collaboration, which together reshape how the business is perceived in terms of both growth potential and risk.
Scan beyond Coty and compare its recent swing in sentiment with other consumer brands on the 21 high quality undiscovered gems that combine established labels with underappreciated stories.
Coty has surged in the short term while still carrying heavy five year losses, and the share price now sits above the average analyst target. So where does a reasonable fair value range actually land for this stock?
Most Popular Narrative: 24% Overvalued
Coty last closed at $3.29, while the most followed narrative anchors fair value at $2.65. The recent price strength leans ahead of that framework and puts more weight on the sustainability story and brand activity than on the base case cash flow path.
The main thing that has to go right is that Coty turns its prestige and consumer beauty underperformance in sell out into at least category level growth, while cost savings programs, SKU reductions, and Gucci related restructuring protect margins and cash generation.
The current valuation and this narrative’s fairly valued, bullish stance together imply that the share price already reflects both the delivery of ongoing cost and deleveraging targets, and the risk that sales and margin pressure, legal actions, and the Gucci license exit could weigh on future results.
See why 9 investors see Coty as 24% overvalued.
Result: Fair Value of $2.65 (OVERVALUED)
Still, Coty is contending with falling like for like sales and a future Gucci Beauty profit hit that could pressure margins if cost savings fall short.
Find out about the key risks to this Coty narrative.
Another View: Coty’s valuation through the revenue lens
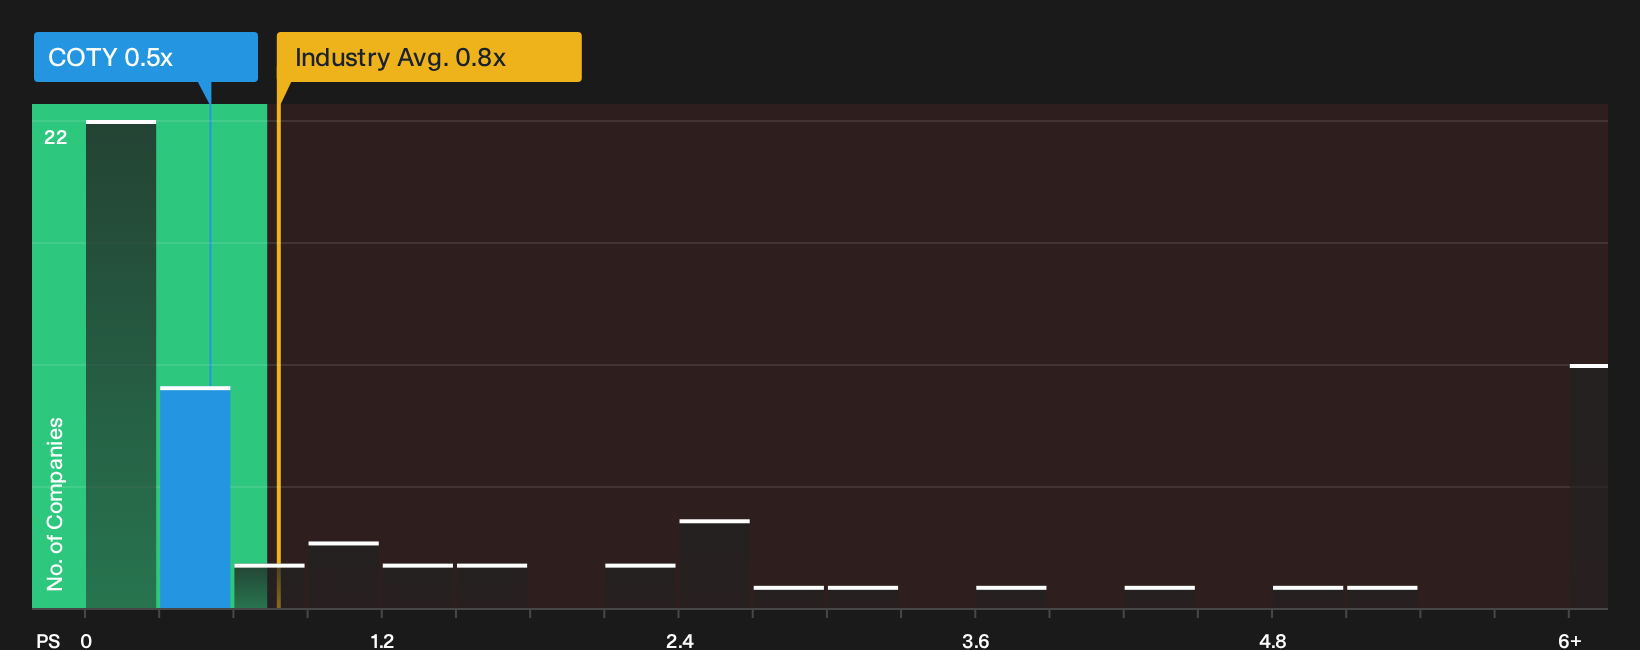
The analyst narrative pegs Coty’s fair value at $2.65, which implies the stock looks stretched at $3.29. On a simple revenue multiple, the picture shifts. Coty trades on a P/S of 0.5x, compared with 0.8x for the US Personal Products group and a fair ratio of 0.9x that the market could gravitate toward over time.
That gap suggests investors are pricing Coty’s recent losses, board turnover, and forecast revenue decline more harshly than peers, even though the business is still flagged as good relative value. The key question is whether the expected swing to profitability justifies that discount or signals extra valuation risk at today’s price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Coty is split between short term price strength and questions about how much good news is already in the valuation. Act quickly and test the assumptions against your own expectations by reviewing the 3 key rewards.
Looking for more investment ideas beyond Coty?
If Coty has sharpened your focus on valuation and momentum, do not stop here. The wider market still holds plenty of underappreciated opportunities waiting for a closer look.
- Target value opportunities that pair quality with a potential discount by scanning our 29 high quality undervalued stocks.
- Prioritise resilience and focus on capital preservation by concentrating on companies flagged in the 30 resilient stocks with low risk scores.
- Hunt for sturdier balance sheets that may be better positioned for tougher conditions by filtering through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com