
Will AI Spending Doubts Change Soitec's (ENXTPA:SOI) Share Price Narrative
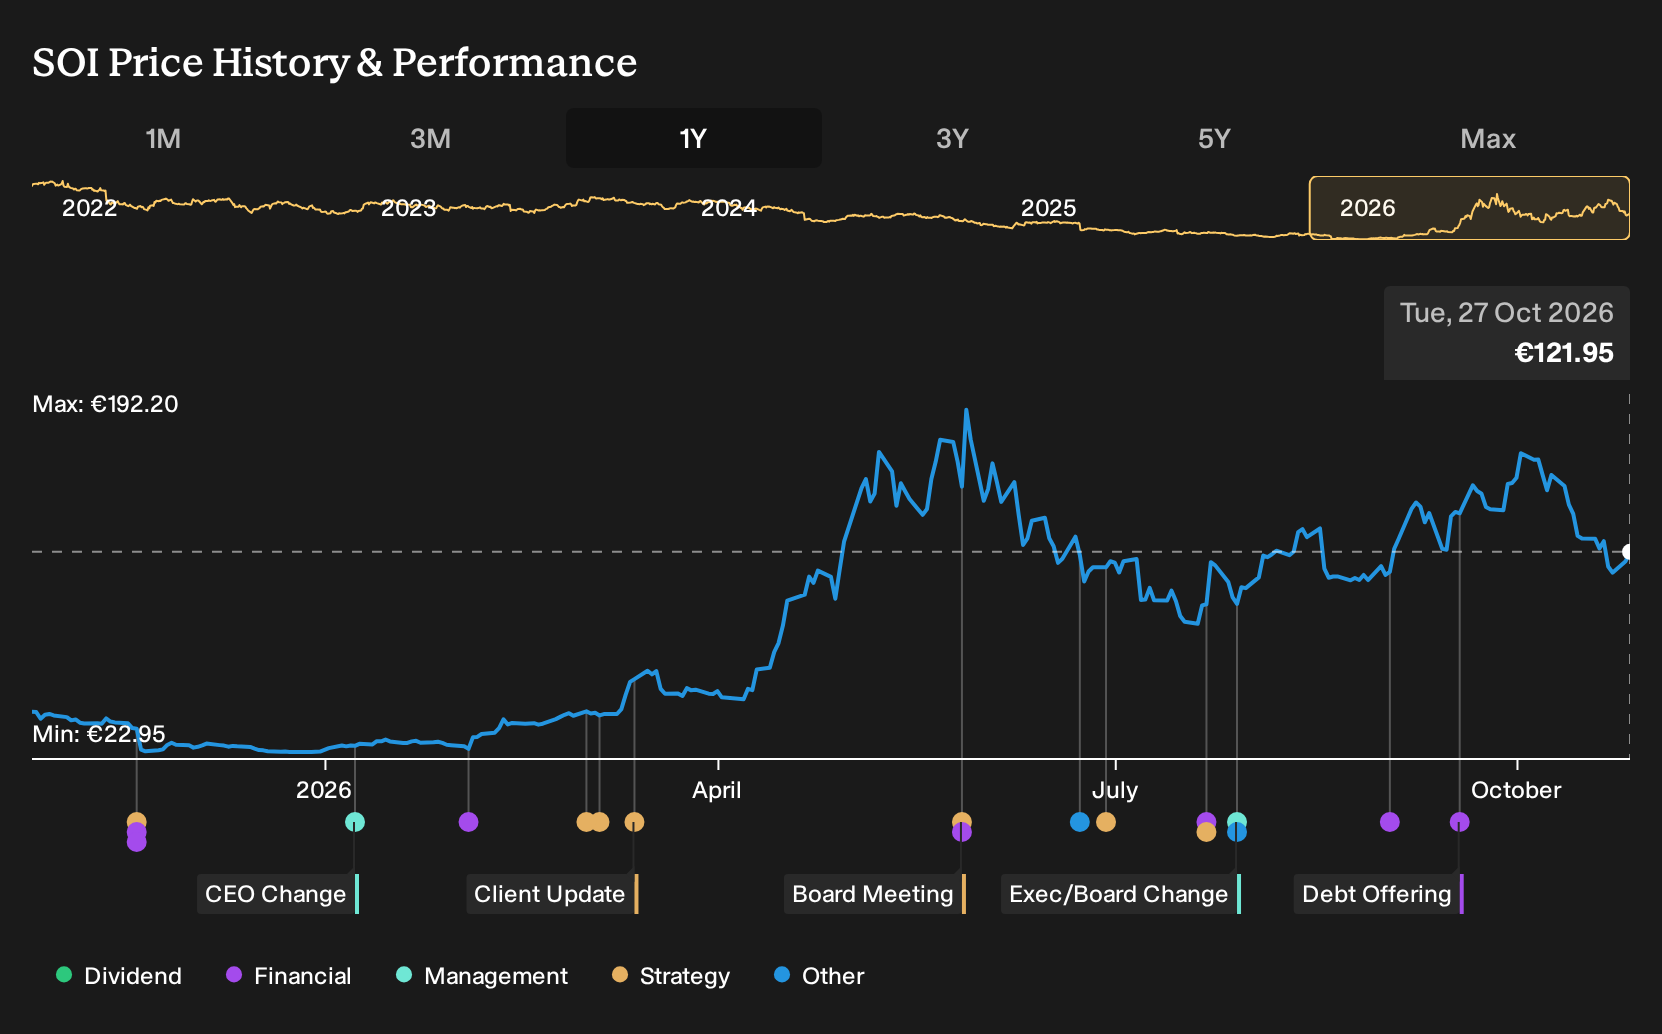
- Soitec has come under pressure as investors reassess whether its strong share performance is supported by current revenue levels, given concerns about how much AI infrastructure spending can sustain demand for its semiconductor substrates.
- The spotlight is on Soitec's premium P/S multiple versus wider semiconductor peers, raising questions about how much AI driven expectations are already embedded in the valuation.
- We will now examine how Soitec's investment narrative is affected by investor unease around AI infrastructure sustainability and its premium valuation.
Contrast Soitec's premium P/S story with a curated set of other AI infrastructure plays, screened on 55 AI infrastructure stocks, to see how its valuation pressure compares across the theme.
Soitec Investment Narrative Recap
To own Soitec, you need to believe its specialty substrates remain central to the build out of AI, data center and connected device hardware, even as demand patterns move around. The key short term swing factor is how quickly customers work through elevated inventories in RF-SOI and other lines, which still weighs on revenue visibility and factory loading.
The biggest risk right now is that AI infrastructure spending proves less durable than the share price implies, at a time when Soitec already trades on a premium P/S multiple of 7.3x versus peers. If AI orders slow or smartphone silicon content flattens further, that valuation could stay under pressure without a clear volume inflection.
There have been no fresh company announcements directly tied to this latest AI sustainability debate, so the most relevant reference point remains the existing setup investors already know. Soitec reported revenue of €592.3m and a loss of €222.1m, which means the premium P/S multiple rests more on future scaling rather than current profitability.
For you, the operational question is whether capacity, R&D in areas like SmartSiC and photonics, and customer diversification can translate into the forecast earnings recovery that consensus models. If that operational ramp takes longer because automotive, industrial or data center projects are pushed out, the share price could stay more volatile than the wider French market.
Soitec Forecast Setup Behind The Premium
Soitec's narrative projects €1.2b revenue and €225.5m earnings by 2029. This implies analysts are assuming 26.8% yearly revenue growth and an earnings swing of about €448m from a loss of €222.1m today.
Uncover how Soitec's fair value indicates a 35% potential upside to its current price before expectations close that valuation gap.
Exploring Other Perspectives
For a very different take on Soitec, the most optimistic analysts focus on Photonics-SOI as the real swing factor. They model revenue reaching about €1.7b and earnings of roughly €525.5m by 2029, far above the consensus €1.2b and €225.5m. These projections were set before this latest AI spending worry, so views may change as new information becomes available.
Explore 3 other Soitec fair value estimates, including one that suggests as much as 134% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Soitec research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Soitec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Soitec's overall financial health at a glance.
Looking for more investment ideas beyond Soitec?
If the Soitec story has sharpened your thinking about valuation, risk and growth expectations, it can help to set it alongside a broader watchlist built from different styles of opportunities.
- For investors who want potential upside without paying up for quality, scan a curated group of what Simply Wall St views as 610 high quality undiscovered gems that combine stronger fundamentals with lower market attention.
- If capital preservation matters more to you than big swings, focus on businesses that currently screen as having more resilient profiles using the 223 resilient stocks with low risk scores to see which tickers fit that brief.
- Income focused readers can hunt for payout candidates by filtering for stocks that currently match the yield and stability criteria behind the 224 dividend fortresses and then comparing them against Soitec on total return potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com