
3 UK Nuclear Stocks Investors Are Screening As Sizewell C Funding Questions Grow
Sizewell C has turned into a live-fire test of how the UK funds huge low carbon projects, with taxpayers on the hook for a share of up to £48b and private investors facing fresh questions over risk and reward. That mix of political scrutiny and long term energy goals is already reshaping expectations. Read on to see how three UK listed nuclear and power infrastructure stocks are exposed to this story.
The three stocks highlighted below are just a sample, and the full screen surfaced 10 more UK listed nuclear and low carbon power infrastructure developers with equally compelling narratives that are not covered here. To identify your own highest conviction ideas, head straight to the UK-listed nuclear and low-carbon power infrastructure developers screener.
Costain Group (LSE:COST)
Costain Group plugs directly into the UK’s push for nuclear and low carbon power, using its engineering and consulting capability across energy, water, defence and transport to win complex infrastructure work that can benefit from long term government backed investment plans.
Costain Group generates £595.2 million from Transportation and £468.2 million from Natural Resources, all from UK projects, giving it a broad role in critical infrastructure. The company’s market cap of about £696 million reflects investor attention on this exposure.
For investors tracking UK nuclear and low carbon power infrastructure, Costain Group provides a practical way to gain exposure to the engineering expertise that helps design, maintain and eventually decommission the assets behind that theme.
"The government's decadal commitment to decarbonization, net zero, and upgrading critical infrastructure is leading to unprecedented investment in low-carbon water, energy, and transport assets. This directly aligns with Costain's strategic expertise and is expected to materially lift both revenue and margin mix."
What really matters now is how one quiet shift in project funding terms and risk sharing ends up flowing through to those future margins.
To see how that funding shift could accelerate or cap Costain Group’s upside, read the full narrative for Costain Group for the full margin and risk story.

Severfield (LSE:SFR)
Severfield gives you a steel backed way into the UK nuclear and low carbon power build out. It supplies complex structural frames that sit under everything from reactors to energy hubs and data centres, as long cycle infrastructure spending shapes the order book.
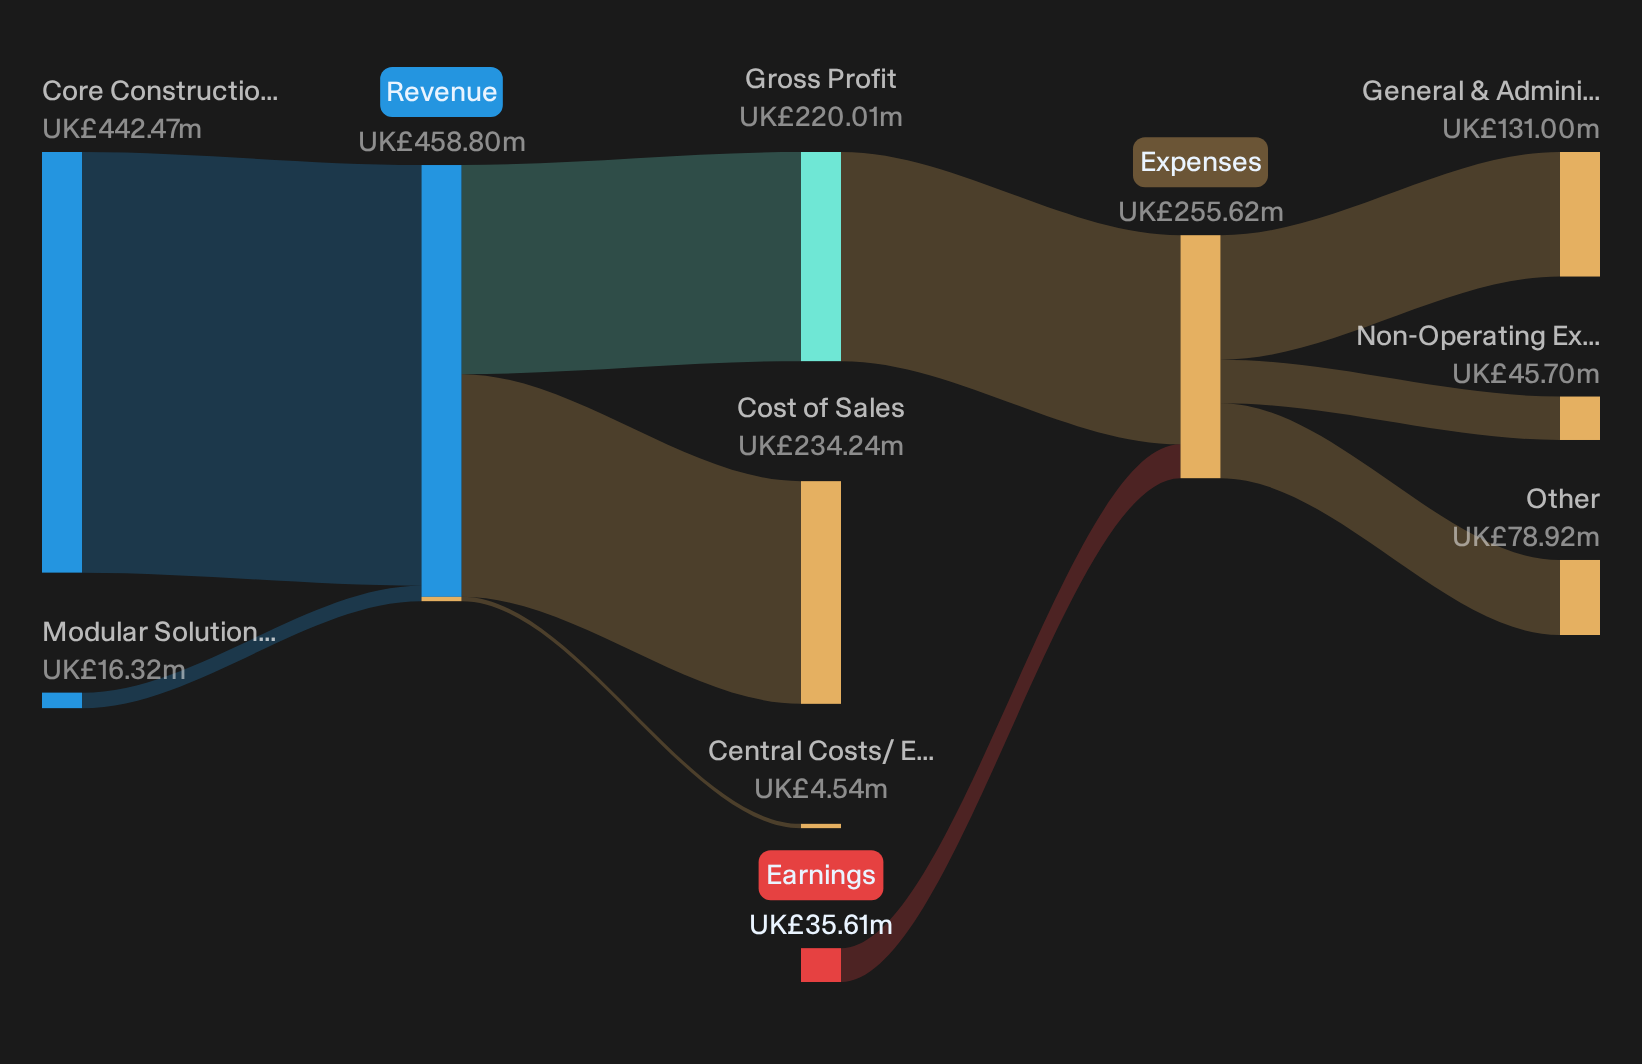
Severfield designs, fabricates and erects structural steelwork for large projects, with about £442 million from Core Construction and £16 million from Modular Solutions, and a market value near £111 million anchoring its role in UK focused power infrastructure.
"Greater focus on complex projects in sectors such as defense, nuclear, bridges and energy projects, supported by large reference schemes like Old Oak Common, Hinkley Point C and Project ONE, positions Severfield to target work where its engineering capability can support stronger project selection and potentially higher operating margins over time."
What really matters now is how one unresolved pressure inside that project mix ends up shifting where future margins actually settle.
That margin question is exactly what the full narrative for Severfield unpacks, separating temporary project pressure from longer term earnings power that could be quietly accelerating.
Keller Group (LSE:KLR)
Keller Group links into the nuclear and low carbon power theme through its foundation and ground engineering work that underpins large power and infrastructure sites. The group earns about £3.2b from specialist geotechnical services worldwide and carries a market value close to £2.2b.
Keller Group provides exposure to the nuts and bolts of major energy projects, where secure ground conditions decide whether complex schemes like Sizewell C and other baseload assets stay on time and on budget.
"Growing exposure to large infrastructure, energy related and data centre projects, including data centres rising from 3% of group revenue in 2025 to 9% in H1 2026 and over 15% of U.S. revenue excluding Suncoast, together with major jobs like I-40, points to a revenue mix that could support sustained top line growth and firm margins."
What matters for Keller Group now is how one quiet shift in which projects it prioritises ends up feeding through to future margin resilience.
To see how that project mix could quietly reshape Keller Group’s earnings profile, read the full narrative for Keller Group and identify where short term noise may be masking longer term strength.

Curious About Alternative Opportunities?
Fresh ideas move fast. Some of the most interesting stories gain momentum quietly, then break out before most investors even notice. Scan these under the radar ideas now and get in early.
- Target steadier cash flows and potential income resilience by reviewing a curated group of 5 dividend fortresses that could help anchor the higher risk corners of your portfolio.
- Hunt for overlooked growth by scanning 5 high quality undiscovered gems, which screens for quality fundamentals before wider attention catches up and pricing power starts flying.
- Position ahead of critical infrastructure build outs by assessing 42 power grid technology and infrastructure stocks, which may be relevant if grid reliability and electrification stay high on government agendas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com