
StorageVault Canada (TSX:SVI) Reported Revenue Growth And A Dividend Increase, Is It Above Fair Value?
StorageVault Canada earnings and dividend move draw investor focus
StorageVault Canada (TSX:SVI) is back on radars after third quarter 2026 results showed higher revenue alongside a swing to a net loss, paired with a small fourth quarter dividend increase.
Recent trading suggests that investors remain cautious. The share price return over the past three months is down 14.02%, year-to-date share price performance is lower by 10.32%, and the 1-year total shareholder return is down 15.70%, despite the dividend increase and revenue gains reported by StorageVault Canada.
Scan how StorageVault Canada compares with other income and real estate plays by reviewing our curated list of 3 dividend fortresses that have attracted investors looking for consistent payouts.
StorageVault Canada trades below the average analyst price target after a sharp share pullback and a move into loss making territory. Is the discount pointing to mispricing, or a fair response to fresh risk?
Price-to-Sales of 4.3x: Is it justified for StorageVault Canada?
On a simple sales based yardstick, StorageVault Canada trades on a P/S ratio of 4.3x at a last close of CA$4.17, which screens as expensive relative to several benchmarks.
The P/S multiple compares the company’s market value to its annual revenue. For an asset heavy real estate operator like StorageVault Canada, this ratio effectively tells you how much investors are currently willing to pay for each dollar of storage and related service income generated across its Canadian network.
That 4.3x P/S is described as rich both versus an estimated fair P/S level of 3.1x and against peers. The fair ratio points to a level the market could move towards if sentiment or expectations around future cash generation cool. At the same time, the P/S of 4.3x is also described as expensive compared to the Canadian Real Estate industry average of 2.7x and remains high even relative to the peer average, which is also 4.3x.
Explore the SWS fair ratio for StorageVault Canada.
Result: Price-to-sales of 4.3x (OVERVALUED)
Still, StorageVault Canada carries clear risks if the recent net loss persists or if revenue growth of 5.43% slows and compresses that premium P/S multiple.
Find out about the key risks to this StorageVault Canada narrative.
Another view on StorageVault Canada valuation
The P/S discussion paints StorageVault Canada as expensive, yet the SWS DCF model sketches an even tougher picture. At CA$4.17, the share price sits above an estimated future cash flow value of CA$1.56, which frames the stock as overvalued rather than merely fully priced. That gap raises a simple question for you as an investor: Which signal carries more weight, current revenue or modeled cash generation?
Look into how the SWS DCF model arrives at its fair value.
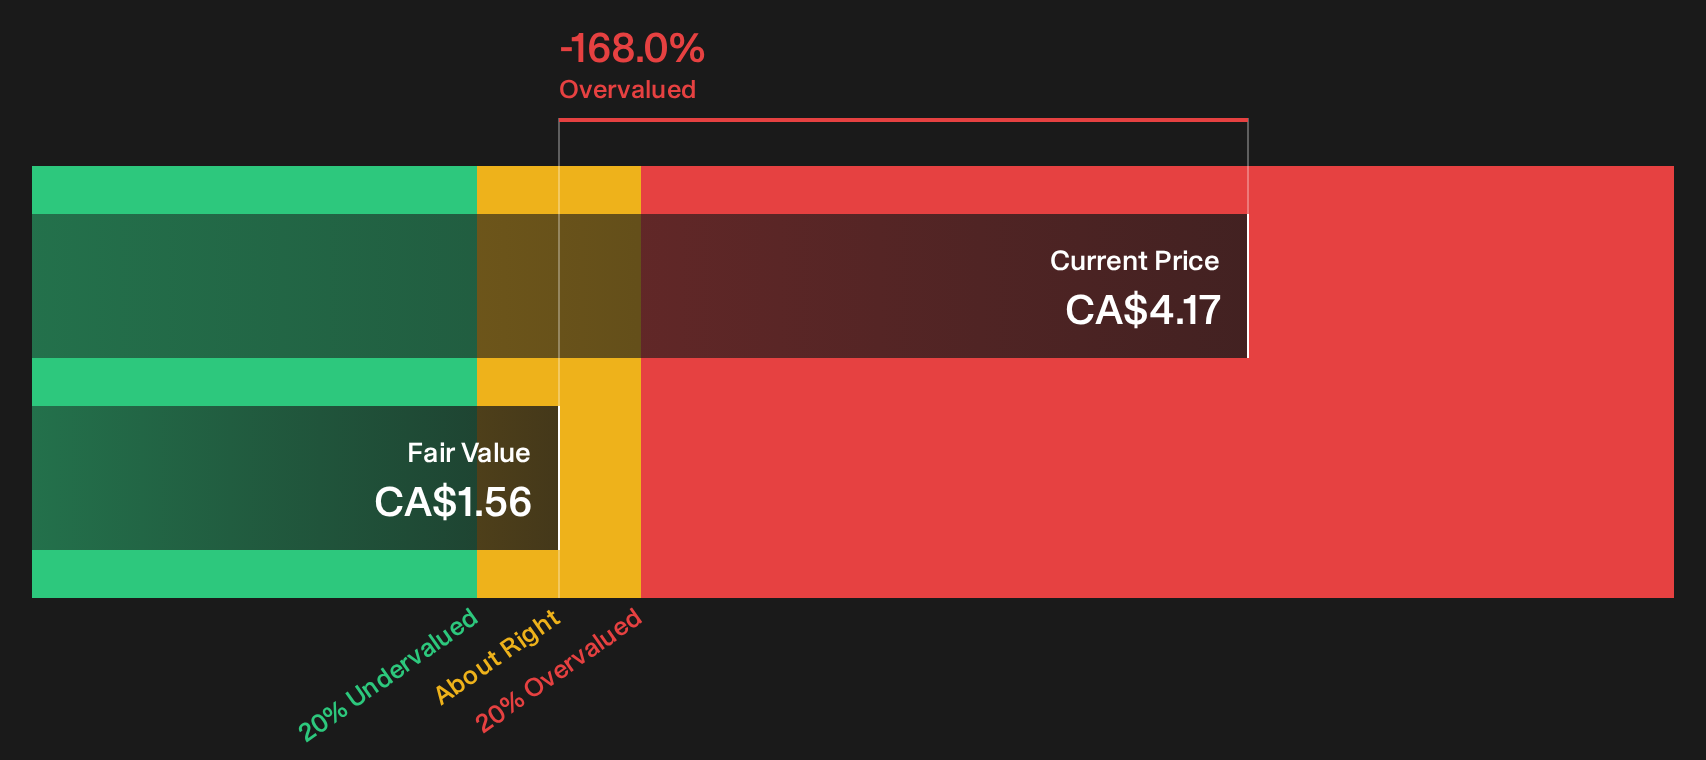
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out StorageVault Canada for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around valuation and earnings can be noisy, so consider acting promptly, review the underlying data for StorageVault Canada, and weigh the 2 key rewards
Looking for more StorageVault Canada style investment ideas?
Do not stop with StorageVault Canada. Broaden your watchlist now, because some of the most interesting opportunities only show up when you scan beyond your usual comfort zone.
- Target resilient balance sheets and steadier fundamentals by reviewing a curated list of solid balance sheet and fundamentals (7 results) that can help anchor your portfolio.
- Hunt for potential mispricing by working through a focused 3 high quality undervalued stocks that filter for quality alongside attractive valuations.
- Strengthen your income stream by scanning a hand picked 3 dividend fortresses that many investors use when they want consistency from payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com