
Is AI Trading Launch Altering The Investment Case For Interactive Brokers Stock (IBKR)?
- Interactive Brokers Group reported third quarter 2026 net income of US$314 million and nine month net income of US$893 million, while also unveiling IBKR Autonomous Trading and approving a higher quarterly dividend of US$0.15 per share payable in December 2026.
- The combination of AI driven autonomous order execution, earnings that show higher net income than a year earlier, and a larger cash dividend directly connects Interactive Brokers Group’s technology push with its current profitability and shareholder cash returns.
- We will look at how Interactive Brokers Group’s investment narrative is affected by IBKR Autonomous Trading’s automated execution capability and recent earnings.
Scan how Interactive Brokers Group’s AI push compares with other trading platforms by reviewing a curated group of 55 AI infrastructure stocks riding similar demand for scale, automation, and always-on execution.
Interactive Brokers Group Investment Narrative Recap
To own Interactive Brokers Group, you need to believe its low cost, high automation model can keep attracting active traders, advisors and partners even as rivals invest heavily in platforms of their own. The recent earnings, with higher net income and margins than a year earlier, support that high efficiency story in the short term.
The near term swing factor remains trading activity and monetisation of client cash, which are both sensitive to rate cuts and market volumes. The biggest risk is that competitors narrow the gap on pricing or tools, which could make IBKR’s current premium P/E harder to defend if growth or profitability slows.
The launch of IBKR Autonomous Trading is the announcement most tied to this news. It moves the broker from using AI mainly for research and instruction generation to actual order submission across more than 75,000 instruments, subject to eligibility rules and client defined instructions.
For catalysts, this shift matters because it aims to give heavy users more scale, speed and discipline, which can influence how much order flow IBKR captures across time zones. The trade off is higher execution and technology complexity, so the key operational watchpoints are reliability, safeguards in the AI Partition, and how quickly eligible clients adopt the feature.
Interactive Brokers Group's current projections suggest it could reach US$10.7b in revenue and US$1.8b in earnings by 2029, which would imply 16.0% yearly revenue growth and an earnings increase of about US$700m from US$1.1b today.
Uncover why Interactive Brokers Group's fair value indicates a 29% potential upside to its current price that could narrow quickly.
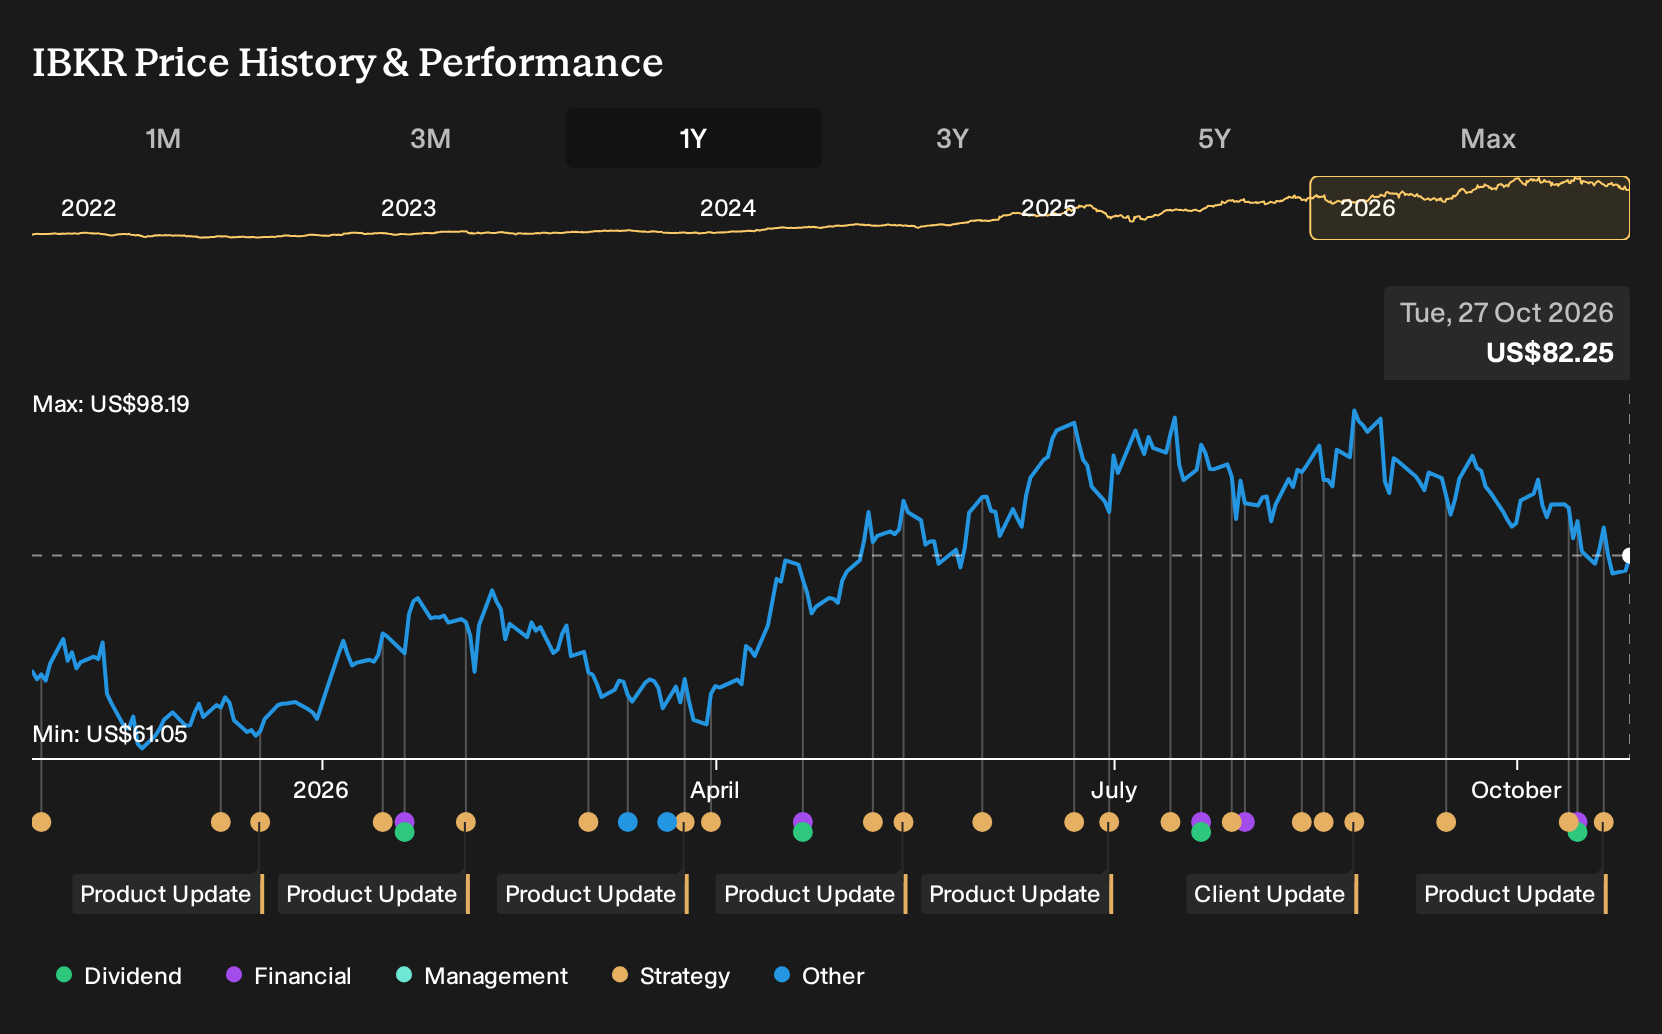
Exploring Other Perspectives
Some of the most optimistic analysts focus on Interactive Brokers Group’s excess capital as the key catalyst rather than AI automation. Before this news, the bullish camp was modeling revenue of about US$12.0b and earnings of roughly US$2.1b by 2029. Those forecasts were set without IBKR Autonomous Trading in the picture, so expectations could shift meaningfully from here.
Explore 8 other Interactive Brokers Group fair value estimates, including one that suggests as much as 46% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Interactive Brokers Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Interactive Brokers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interactive Brokers Group's overall financial health at a glance.
Looking for more investment ideas beyond Interactive Brokers Group?
If you want to pressure test your view on Interactive Brokers Group and widen your opportunity set, the Simply Wall St Screener can help you line up other candidates with clear fundamentals and different risk profiles.
- For readers who want income to be a meaningful part of total returns, scan a curated group of 5 dividend fortresses that may offer higher cash payouts than broad market averages.
- If capital preservation is your first priority, filter for stability by reviewing a 30 resilient stocks with low risk scores that scores well on balance sheet strength and business predictability.
- When you are hunting for under-followed opportunities with room for fresh coverage, cast a wider net across a 21 high quality undiscovered gems that pair quality metrics with relatively low attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com