
Could Earnings Rebound Shift Cactus (WHD) Stock Investment Narrative?
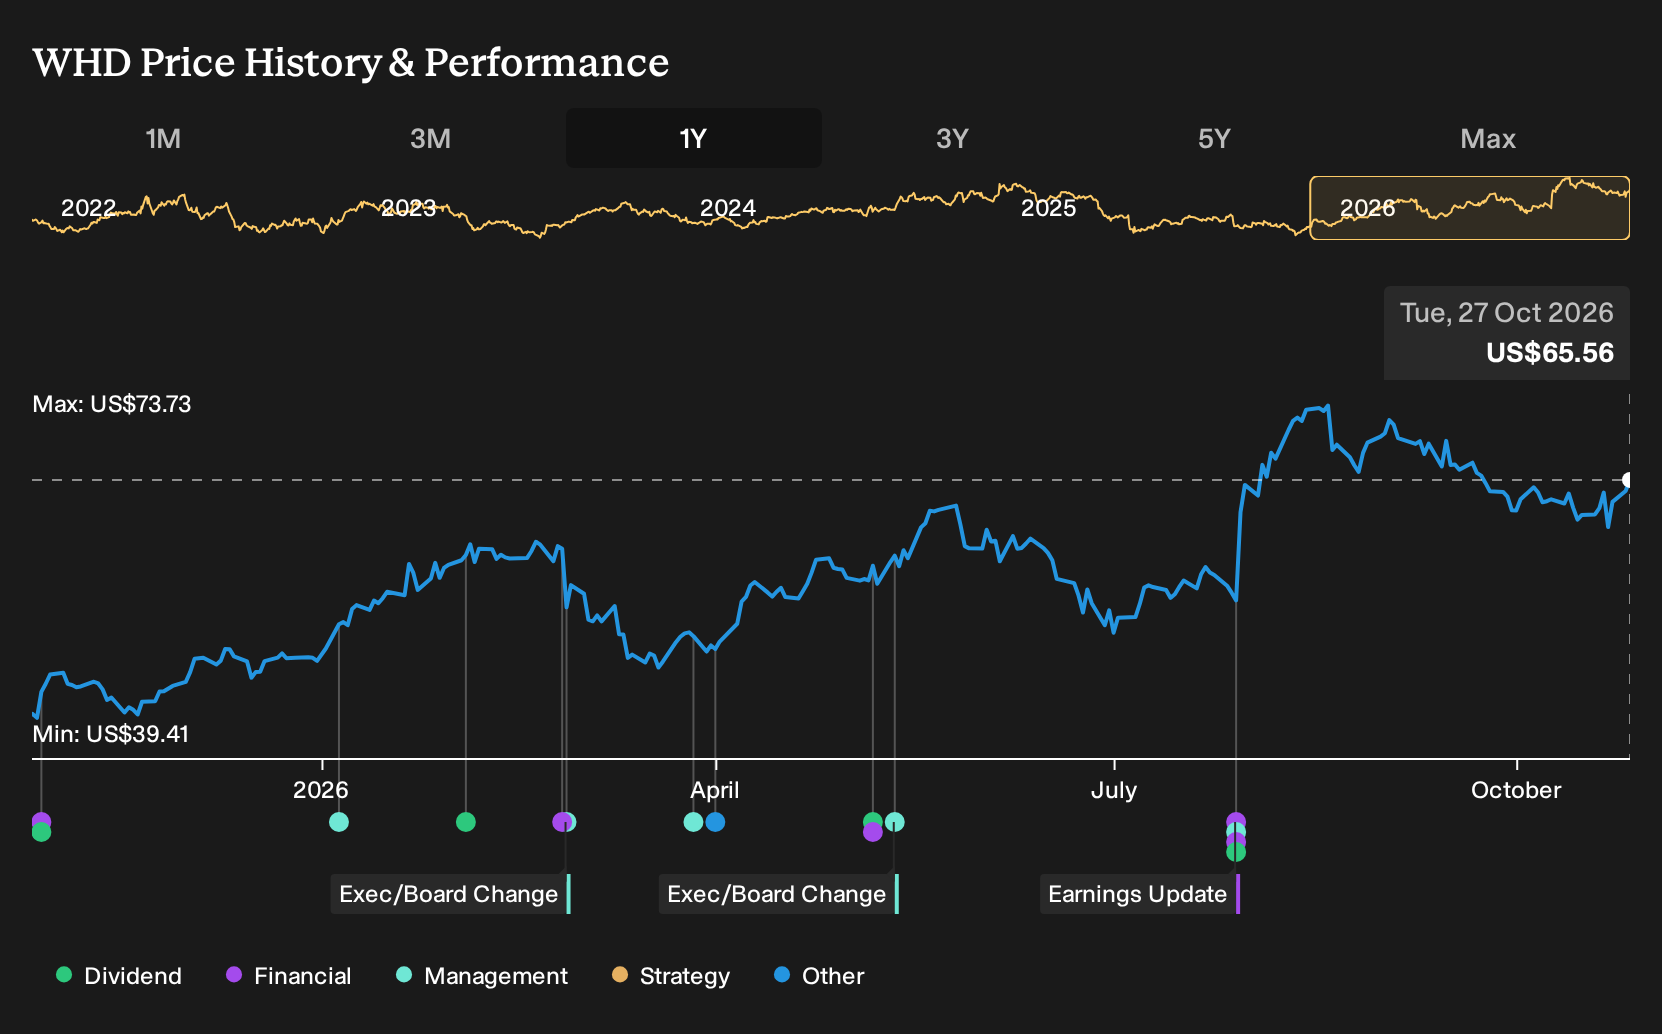
- Cactus is scheduled to report quarterly earnings after the bell on Wednesday. The market expects revenue to be 63.5% higher year on year, compared with a 10% decline in the same quarter a year earlier.
- The steady analyst estimates over the past month suggest expectations for Cactus’s operations and demand profile have remained anchored ahead of this earnings release.
- We will now examine how Cactus's investment narrative could be influenced by the market’s focus on this sharp expected revenue rebound.
Scan how Cactus’s expected rebound compares with other oilfield and energy names being monitored for their own breakout potential through the 21 high quality undiscovered gems.
Cactus Investment Narrative Recap
Owning Cactus means buying into a story where pressure control and spoolable pipe equipment can convert energy project activity into solid cash generation. The big short term swing factor is whether the expected 63.5% revenue rebound comes through with cleaner profitability after a year when margins moved down to 6% from 16.2%. The upcoming quarter will say a lot about that.
The largest operational risk right now sits with tariffs and integration. Cactus still carries heavy steel duties and is working through a major Surface Pressure Control acquisition. If sourcing shifts and supply chain savings do not materialise as planned, the headline revenue bounce would have limited effect on earnings quality.
With no fresh announcements filed alongside this earnings date, the earlier acquisition of Baker Hughes' Surface Pressure Control business remains the key reference point. That deal expanded Cactus International, tied the group more closely to Middle East and broader international projects, and created a larger base where supply chain execution really matters.
For you, the link to the upcoming report is straightforward. Any detail on order intake across the Middle East, Asia, Africa, and Latin America, combined with commentary on synergy targets and tariff optimisation, will help frame how quickly this acquired portfolio can contribute. The more clearly Cactus shows progress here, the easier it becomes to judge whether current risks around costs and integration are starting to ease.
Cactus' narrative projects US$2.0b revenue and US$461.1m earnings by 2029. This assumes 14.3% yearly revenue growth and an earnings increase of about US$379.2m from US$81.9m today.
Uncover how Cactus' fair value indicates a 9% potential upside to its current price before the gap closes.
Exploring Other Perspectives
One alternate view on Cactus leans heavily on earnings risk if Vietnam sourcing or international spoolable pipe orders slip. The most cautious analysts were penciling in about 12.6% annual revenue growth and around US$373.8m in 2029 earnings before this earnings release. That is a far more restrained path, and it shows how widely expectations can differ. Use this report as a chance to compare these pre news forecasts with your own assumptions and explore where you sit on that spectrum.
Explore 2 other Cactus fair value estimates, including one that suggests it could be worth just $71.56.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cactus research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cactus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cactus' overall financial health at a glance.
Looking for more investment ideas beyond Cactus?
Once you have a view on Cactus, it can help to set it in context by comparing it with other opportunities that fit your own risk, income, and quality preferences.
- If capital preservation is front of mind, start with a focus on stability and financial resilience through a 30 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and underlying fundamentals, filter for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- If your priority is income, zero in on companies offering meaningful yields that still aim to protect capital through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com