
Asian Penny Stocks Spotlight: Jilin Province Huinan Changlong Bio-pharmacy And 2 Others To Consider
The Asian markets have recently been navigating a landscape marked by volatility due to AI investment concerns and rising oil prices, which have affected global indices. Despite these challenges, investors can find opportunities in lesser-known areas of the market, such as penny stocks. Though often considered a holdover from earlier market days, penny stocks—typically representing smaller or newer companies—remain relevant for their potential affordability and growth prospects. In this article, we explore three such stocks that stand out for their financial strength and potential stability amidst current market conditions.
Here we highlight a subset of our preferred stocks from the screener.
Jilin Province Huinan Changlong Bio-pharmacy (SEHK:8049)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Jilin Province Huinan Changlong Bio-pharmacy Company Limited manufactures and distributes Chinese medicines and pharmaceutical products under the Changlong and Qing Tong brands in the People’s Republic of China, with a market cap of HK$1.51 billion.
Operations: The company generates its revenue primarily from the manufacture and distribution of Chinese medicines and pharmaceutical products, amounting to CN¥898.05 million.
Market Cap: HK$1.51B
Jilin Province Huinan Changlong Bio-pharmacy demonstrates solid financial health with CN¥1.3 billion in short-term assets covering both short and long-term liabilities, and earnings growth of 19.5% over the past year, surpassing its five-year average of 6.3%. Despite low return on equity at 12.1%, the company maintains high-quality earnings and a net profit margin improvement to 24.4%. However, recent board changes due to Mr. Gao's passing have led to non-compliance with Hong Kong's GEM Listing Rules, necessitating prompt director appointments within three months to restore compliance and stabilize governance structures.
- Get an in-depth perspective on Jilin Province Huinan Changlong Bio-pharmacy's performance by reading our balance sheet health report here.
- Understand Jilin Province Huinan Changlong Bio-pharmacy's track record by examining our performance history report.

Cortina Holdings (SGX:C41)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Cortina Holdings Limited is an investment holding company involved in the distribution and retailing of timepieces and accessories across Singapore, Malaysia, Thailand, Indonesia, Hong Kong, Taiwan, and internationally with a market cap of SGD678.87 million.
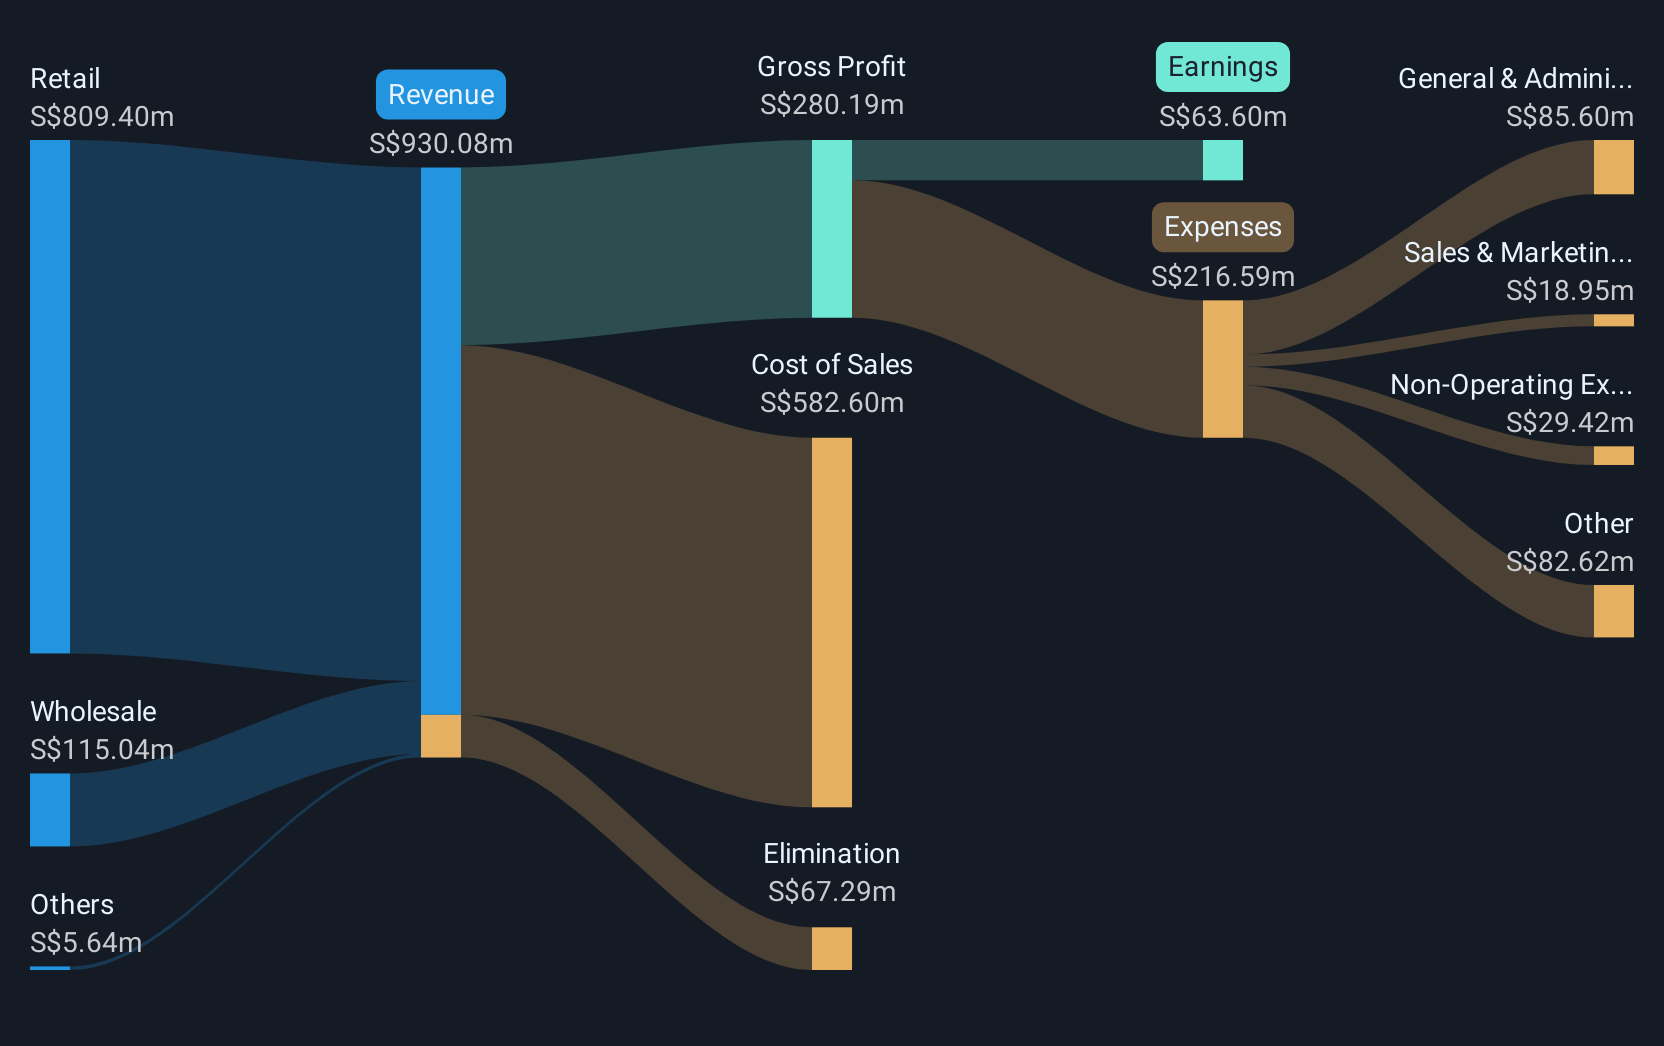
Operations: Cortina Holdings generates its revenue primarily from the retail segment, which accounts for SGD910.38 million, followed by the wholesale segment at SGD123.09 million.
Market Cap: SGD678.87M
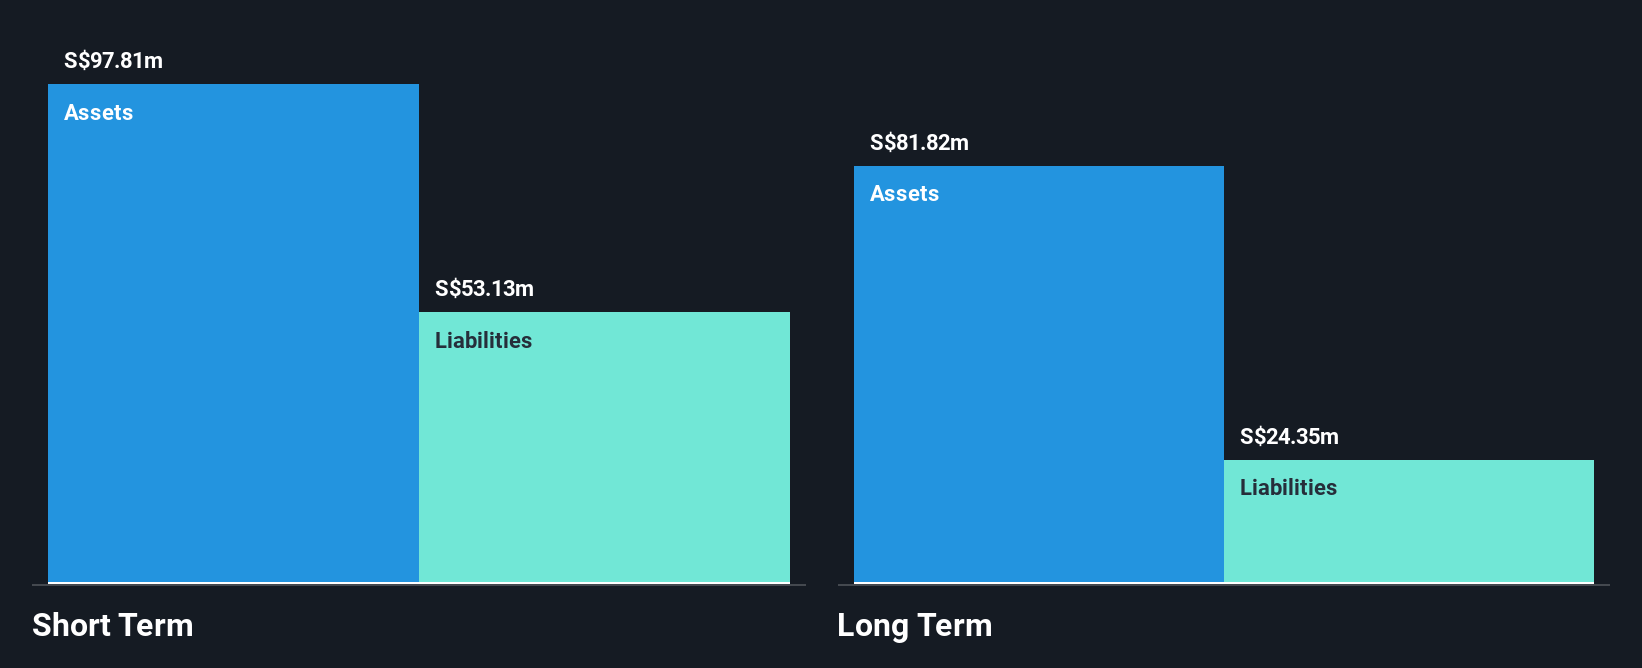
Cortina Holdings Limited, with a market cap of SGD678.87 million, recently announced a share buyback program and a special dividend of 14 cents per share. The company has strong financial health, with short-term assets significantly exceeding both short and long-term liabilities. Despite low return on equity at 14.5%, Cortina maintains high-quality earnings and pays a reliable dividend yield of 3.9%. However, its net profit margin declined to 6.6% from last year's 7.4%. While earnings have grown modestly by 2.4% annually over five years, recent growth lagged behind the Specialty Retail industry average.
- Dive into the specifics of Cortina Holdings here with our thorough balance sheet health report.
- Learn about Cortina Holdings' historical performance here.
Grand Banks Yachts (SGX:G50)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Grand Banks Yachts Limited, with a market cap of SGD155.80 million, manufactures and sells luxury recreational motor yachts across the United States, Australia, Europe, and Asia.
Operations: The company generates revenue primarily from its Manufacturing and Trading segment, which accounts for SGD140.53 million.
Market Cap: SGD155.8M
Grand Banks Yachts Limited, with a market cap of SGD155.80 million, has shown stable financial performance despite some challenges. The company's revenue from its Manufacturing and Trading segment reached SGD140.53 million, though net income decreased to SGD13.4 million from the previous year’s SGD18.22 million, reflecting a decline in profit margins to 7.7%. Debt management appears satisfactory with a net debt to equity ratio of 16.7%, and interest payments are well covered by EBIT at 14.5x coverage. Recent guidance suggests healthy sales momentum into the next fiscal period, potentially boosting financial outcomes in early 2027.
- Click here to discover the nuances of Grand Banks Yachts with our detailed analytical financial health report.
- Evaluate Grand Banks Yachts' historical performance by accessing our past performance report.
Next Steps
- Access the full spectrum of 1,081 Asian Penny Stocks by clicking on this link.
- Looking For Alternative Opportunities? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com