
Missed Glenmark's Rally? Here Is What Holders Saw
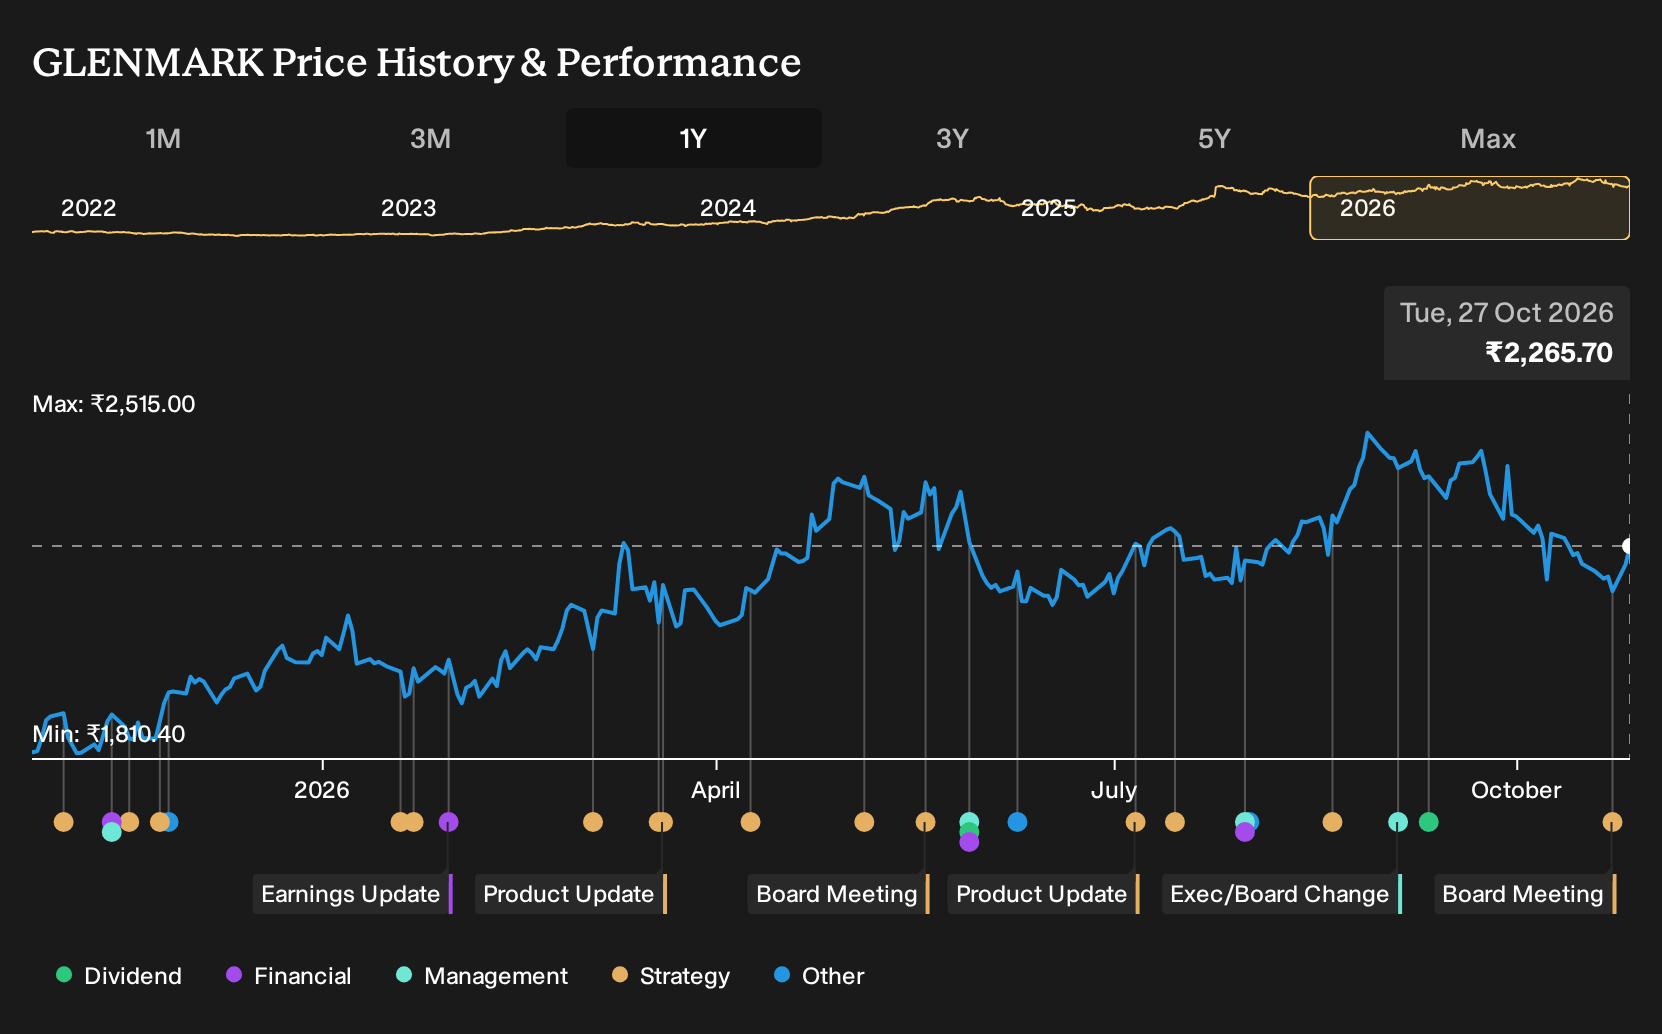
If you had pulled up Glenmark Pharmaceuticals on 27 October 2025, you would have seen analysts split between a bullish case built on branded launches and a bearish view focused on regulatory and debt overhangs. Holding Glenmark Pharmaceuticals over the past year would have returned 24.9%, including dividends. If you were weighing that decision back then, would the branded portfolio push into chronic therapies have outweighed concerns around US scrutiny and balance sheet strain?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Glenmark Pharmaceuticals harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Stories Investors Were Really Choosing Between
The shares cost ₹1,813 at the start of the period, and anyone looking at Glenmark Pharmaceuticals had to decide which story felt more plausible.
On the optimistic side, the bullish narrative put Fair Value at ₹2,246. This was built on the belief that expanding branded and specialty drugs like TEVIMBRA, BRUKINSA and LIRAFIT, along with a push into chronic therapies across cardiac, dermatology and respiratory, would support 12.2% revenue growth and a 16.3% profit margin assumption over three years.
The bearish view anchored Fair Value at ₹1,500. This view argued that rising global regulatory burdens on generics, unresolved US issues such as Monroe and antitrust litigation, and high leverage would keep compliance costs heavy and limit how much of that growth Glenmark Pharmaceuticals could realistically capture.
What The Results Changed For Glenmark Pharmaceuticals
The clearest fresh fact was Glenmark Pharmaceuticals reporting total revenue of ₹32,644.4m in Q1 2026 and ₹40,184.83m in Q1 2027. Net income moved from ₹468.71m to ₹4,829.24m, with net margin rising from 1.4% to 12.0%. That profitability shift supported the optimistic case, although one quarter of stronger margins did not fully settle the longer term debate.
The lesson is simple. When a thesis leans on margin expansion, track the reported net margin line each quarter and see whether it is moving toward the scenario investors paid up for.
What Glenmark’s Current Price Already Bakes In
Glenmark Pharmaceuticals now trades at ₹2,266 after a 24.9% gain over the past year. The selected Narrative places its Fair Value below that level and argues the stock already reflects a debt free balance sheet and management’s margin ambitions.
The core question shifts to staying power. Anyone buying today is effectively assuming Glenmark can keep scaling higher margin respiratory, dermatology and oncology products while holding R&D and IGI spending in line.
"Key Takeaways: Bearish analysts expect Glenmark Pharmaceuticals to remain heavily exposed to cost pressure and complex generics in key markets, which could limit the benefit from its growing portfolio of branded and specialty therapies. The main factor that has to go right is Glenmark Pharmaceuticals successfully scaling higher margin respiratory, dermatology and oncology products across India, Emerging Markets and North America while keeping R&D and IGI spending within the guided ranges."
The price and this Narrative do not agree. → Uncover what this Narrative says Glenmark Pharmaceuticals is actually worth
Looking One Step Beyond Glenmark
Glenmark Pharmaceuticals leans on chronic therapies, where patients often remain on treatment for years. That reliance on long term disease control raises a different question.
If chronic conditions become easier to manage, what sits behind that shift? One global player is focusing on medicines that address obesity and diabetes together.
Its drugs aim to reduce weight, improve blood sugar and ease related complications. This approach targets similar problems Glenmark encounters, from metabolic risk to cardiovascular strain.
The key angle is what happens if these therapies reshape how patients manage weight and diabetes. Could that reframe which treatments feel essential in a typical chronic portfolio?
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com