
Did Stronger Earnings Just Shift Nordnet's (OM:SAVE) Investment Narrative?
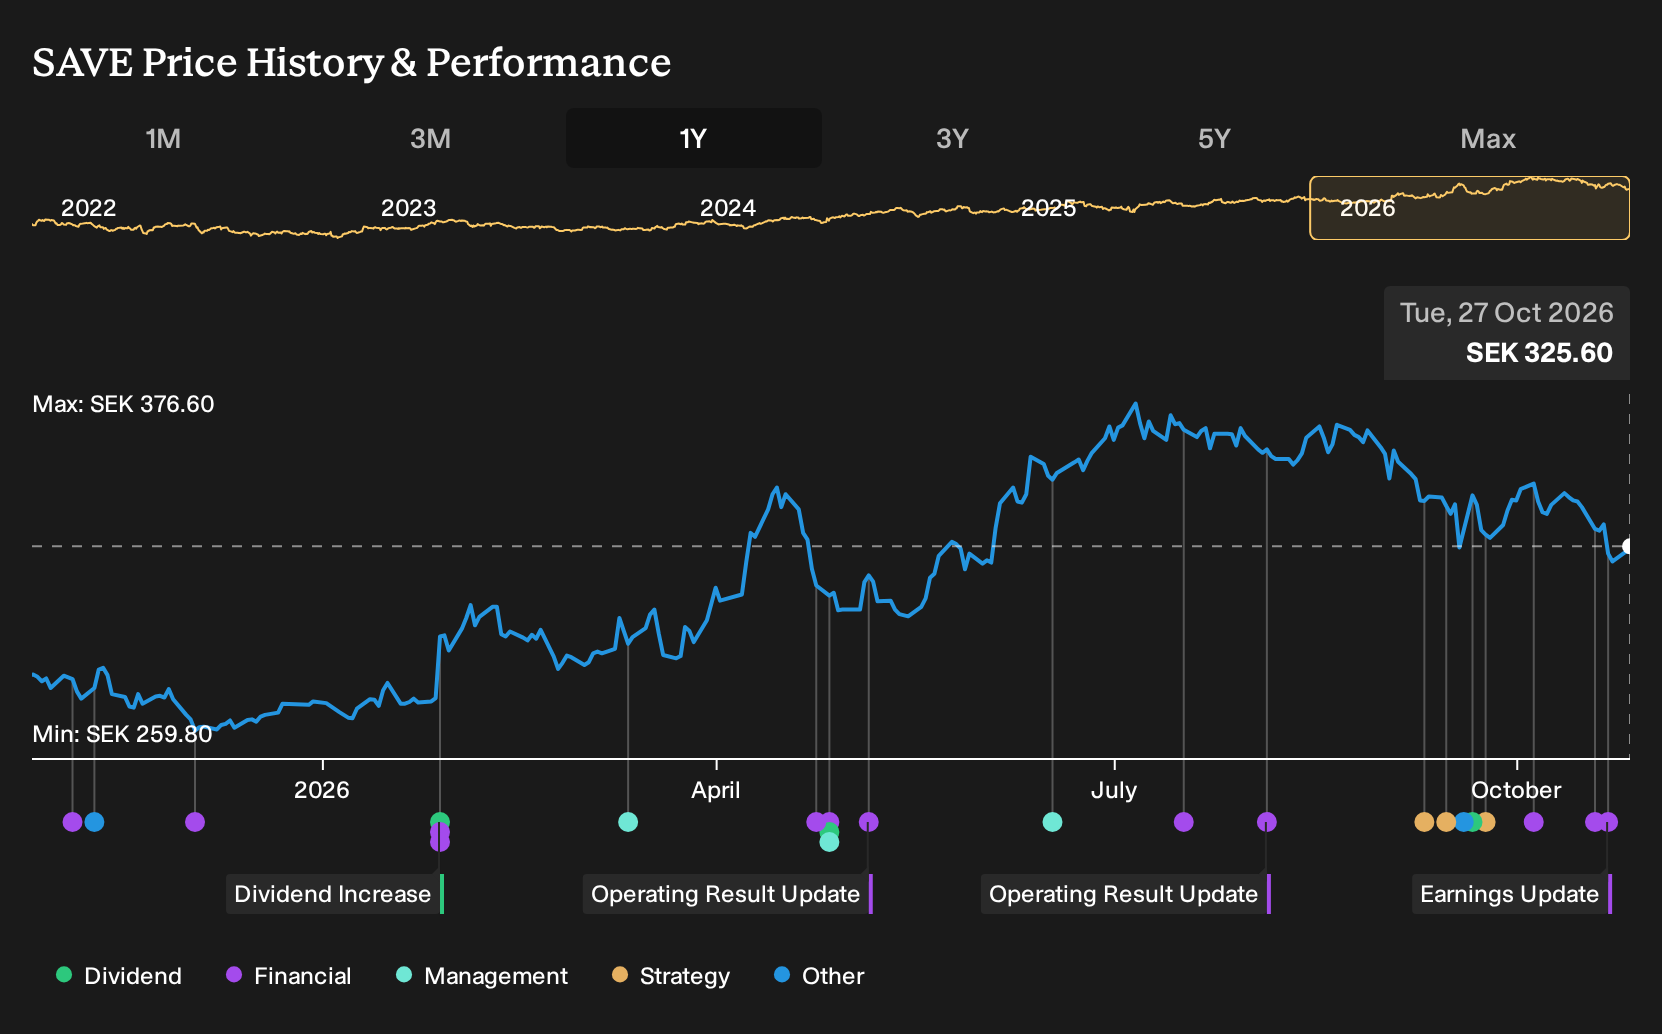
- Nordnet reported third quarter 2026 net income of SEK 885 million and basic EPS of SEK 3.5, alongside a completed 163,654 share buyback for SEK 54.76 million and a planned early redemption of SEK 600 million in additional tier 1 notes.
- The mix of higher reported earnings and active capital management, including both buybacks and planned AT1 redemption, highlights how Nordnet is adjusting its balance sheet and share count while running a digital savings platform across the Nordics.
- It remains to be seen how Nordnet's reported quarterly earnings might affect the existing investment narrative built around customer and asset metrics.
Nordnet Investment Narrative Recap
To own Nordnet, you need to believe its digital savings platform can keep attracting assets and customers across the Nordics while it adds new products like pension wrappers, own funds and future ETF offerings. The latest quarter shows earnings and net profit margins at healthy levels, so the near term story still centers on execution, not repair work.
The main near term catalyst remains whether Nordnet can convert its larger customer base and savings capital into more recurring fee and interest income while holding the efficiency ratio near current levels. The biggest risk is that higher operating costs, including the German build out, rise faster than income and squeeze profitability.
The early redemption of SEK 600m in additional tier 1 notes announced for November 2026 is the most relevant update here. That move simplifies the capital structure and removes a relatively expensive layer of funding, which matters for a platform that does not use low cost customer deposits and instead relies more on external borrowing.
For you as a shareholder, that debt action intersects directly with the key catalyst and risk. It may influence future interest expense and regulatory capital flexibility while leaving Nordnet to prove it can keep funding growth, including Germany and private banking, without letting funding and operating costs outpace the earnings power of its growing asset base.
Nordnet's current analyst story points to revenues of SEK 8.3 billion and earnings of SEK 4.9 billion by 2029, built on assumed annual revenue growth of 8.0%. That profit figure compares with earnings today of SEK 3.4 billion, which implies an earnings increase of SEK 1.5 billion over the period.
Uncover how Nordnet's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For the more optimistic analysts, the real catalyst is Nordnet’s customer and product momentum. Before this buyback and AT1 redemption news, the most bullish forecasts already pointed to revenue of about SEK 8.5b and earnings of SEK 5.2b by 2029. You can read that as a far brighter narrative that might shift again once the latest moves are fully reflected.
Explore 2 other Nordnet fair value estimates, including one that suggests as much as 16% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordnet research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nordnet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordnet's overall financial health at a glance.
Looking for more investment ideas beyond Nordnet?
If Nordnet is only one piece of your watchlist, it can help to scan other listed businesses with different risk and income profiles using the Simply Wall St Screener.
- If you want income potential with some built in resilience, check out 224 dividend fortresses that meet a 5%+ yield hurdle while aiming for staying power.
- For investors who care most about balance sheet strength and fundamentals, scan the list of solid balance sheet and fundamentals (207 results) as a starting universe for further research.
- If you prefer a margin of safety angle, filter for 195 high quality undervalued stocks that pair solid financials with prices below estimated fair value.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com