
Altria Group (MO) Looks 5% Overvalued On Earnings Optimism
Altria Group (MO) is back in focus after fresh Zacks data highlighted an Earnings ESP of +0.26% and a Zacks Rank #2 ahead of its upcoming quarterly report.
Recent trading has been choppy for Altria Group, with the share price easing over the past week but still showing a 30-day share price return of 6.79% and a year to date share price return of 28.23%. Longer term total shareholder returns of 23.99% over one year and well over 100% across three and five years suggest momentum has been building rather than fading as investors weigh the upcoming earnings update against that track record.
Scan how Altria Group compares with other income-focused plays by reviewing the hand picked 5 dividend fortresses in the market right now.
Altria Group now trades close to recent highs while sitting above the average analyst target and well below some intrinsic value estimates. Where does fair value genuinely line up within that range of views?
Most Popular Narrative: 5% Overvalued
Against the last close at $73.49, the most followed narrative pegs Altria Group’s fair value at $70.00. The current quote therefore leans slightly ahead of that estimate while still reflecting a relatively tight gap.
Capital allocation was framed broadly as a support for stable earnings and flexibility. The updated view highlights about US$3.6b in dividends, US$335m in buybacks and a 1.9x debt to EBITDA ratio as more central to per share earnings and the overall equity case.
See why 261 investors see Altria Group as 5% overvalued.
Result: Fair Value of $70.00 (OVERVALUED)
Still, the narrative can fray if on! PLUS spending continues to weigh on oral tobacco profitability or if discount cigarettes continue to chip away at Marlboro’s share and margins.
Find out about the key risks to this Altria Group narrative.
Another View On Altria Group’s Valuation
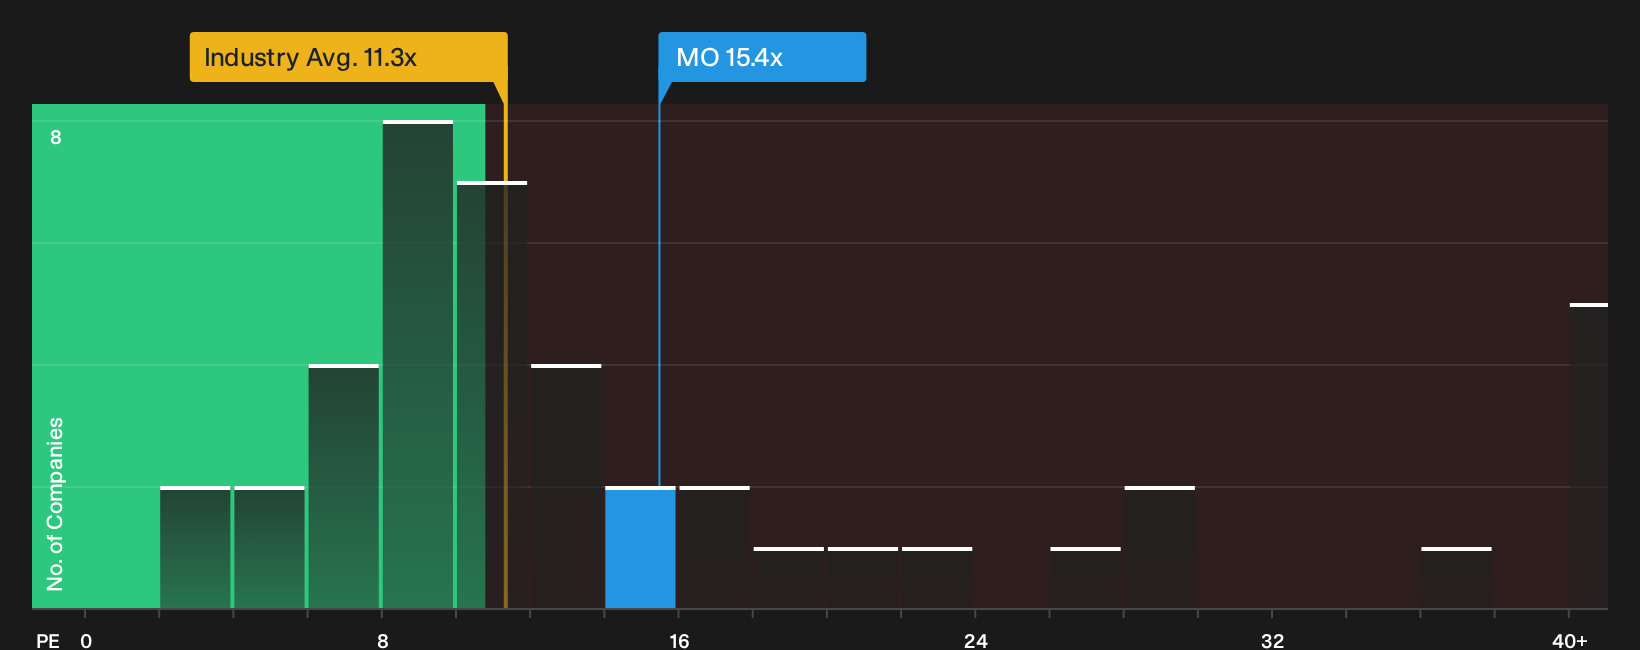
That 5% overvalued narrative looks tight, yet a different lens tells a very different story. On a P/E of 15.4x, Altria Group trades at roughly half of the estimated fair ratio of 21.2x and also below peers at 30.9x. Is the market overcompensating for risk, or is the discount earned?
To pressure test that relative pricing angle against the underlying numbers, take a closer look at how the earnings multiple compares in context, and what the fair ratio suggests about where the market could trade over time, through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Altria Group’s value story so far. If you want to move before the next sentiment swing, weigh the upside against the downside by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Altria Group?
You do not need to stop at Altria Group. Use the screeners below to spot other opportunities before they move out of reach.
- Target dependable cash generators by reviewing the list of solid balance sheet and fundamentals (24 results) that combine resilient finances with steady business models.
- Hunt for potential mispricing by scanning the 29 high quality undervalued stocks that pair stronger fundamentals with share prices that still look discounted.
- Lock in income-focused ideas by checking the 7 elite penny stocks with strong financials that match higher yield potential with specific financial filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com