
What Bears Saw Before Cencosud Slid
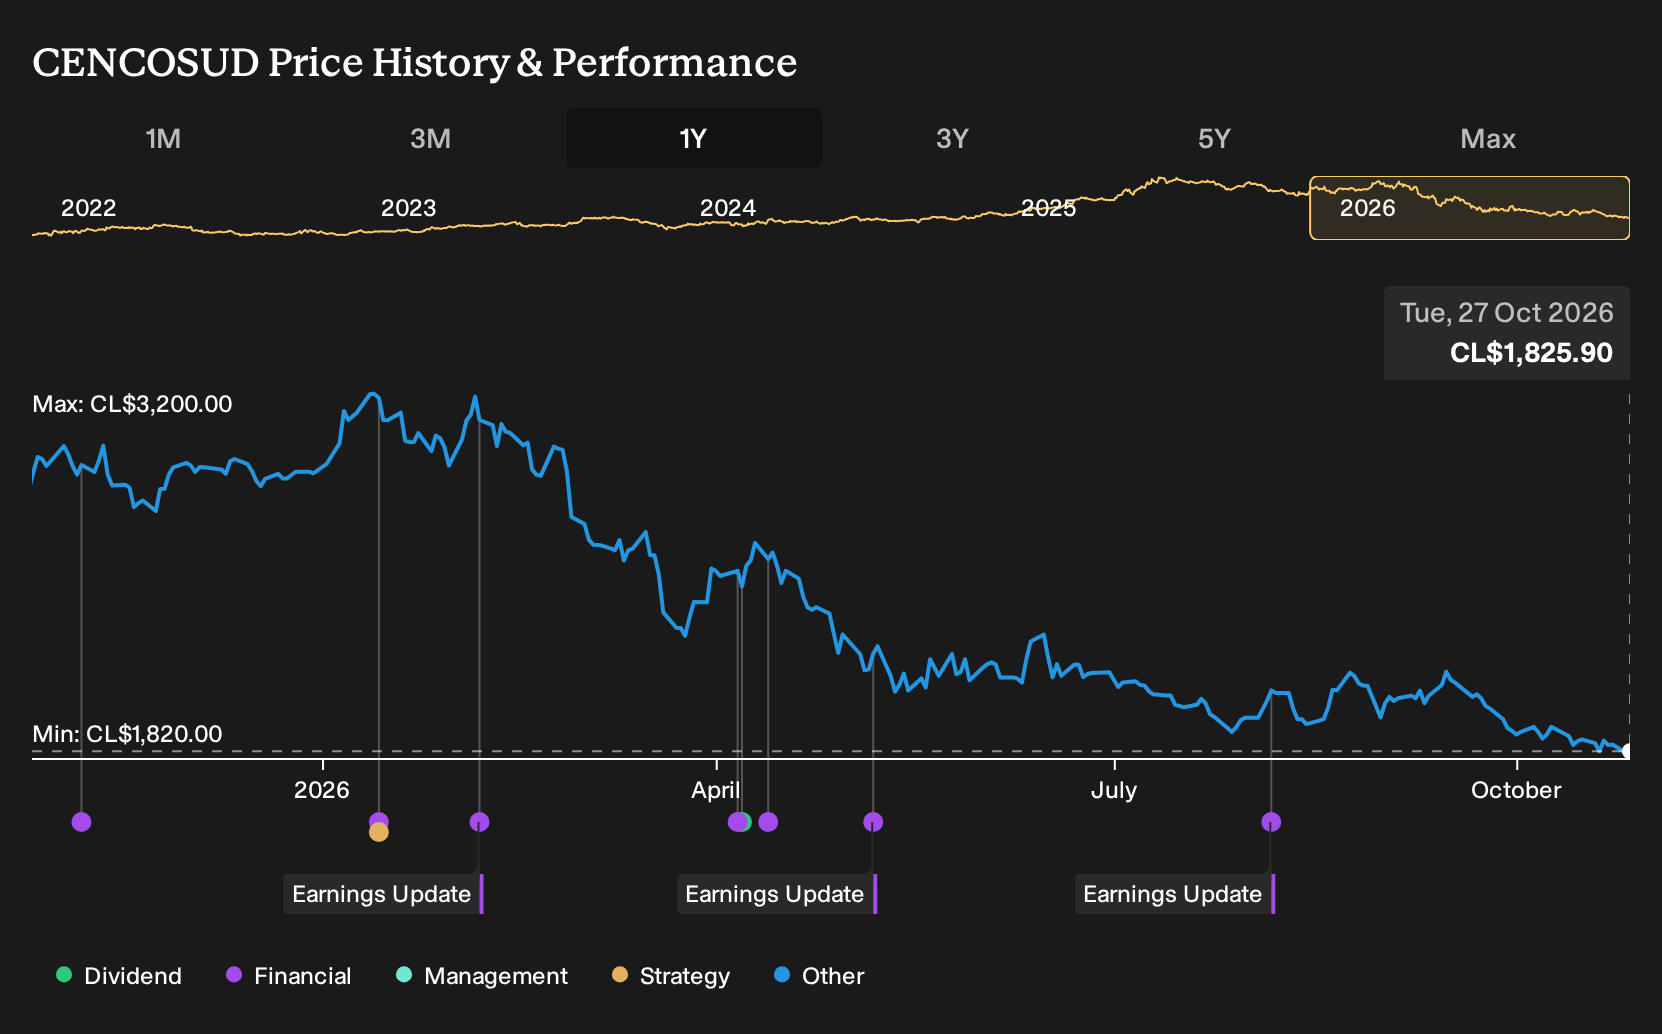
Cencosud’s latest quarterly filing on 7 August 2026 showed revenue slipping and a swing from profit to loss, with net margin moving from 2.1% in Q2 2025 to a loss margin of 0.9% in Q2 2026. Investors who held Cencosud over the past year are down 37.6%, including dividends. If you had bought a year ago on the upbeat or cautious narratives available then, how should this gap between expectation and outcome reshape what you look for next?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Cencosud harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Cencosud Stories Investors Had To Weigh
The shares cost CLP2,899 at the start of the period, and Cencosud sat between two sharply different but credible stories about its future.
The bullish narrative argued for a Fair Value of CLP3,800, built on revenue growing 8.2% a year and profit margin reaching 4.4% within three years.
The bearish view pointed to a Fair Value of CLP2,027, assuming a slower 2.5% annual revenue increase and highlighting digital disruption as a key threat to physical stores.
What The Results Put To The Test For Cencosud
The clearest fact was Cencosud’s swing from profit to loss. Net income moved from CLP86,491.017m in Q2 2025 to a loss of CLP36,455.164m in Q2 2026, and net margin shifted from 2.1% to a loss margin of 0.9%. That outcome challenged both the bullish push toward 4.4% profitability and the cautious scenario that still assumed higher future margins.
The key assumption here was margin repair. When you assess another retailer, track whether net income and margin are moving toward the narrative’s future level, and how many reporting periods that path has actually held.
What Cencosud’s Lower Price Asks You To Believe
Cencosud trades at CLP1,826 today, and the selected Narrative’s Fair Value sits above that level based on its own assumptions rather than any settled fact.
The argument leans on tighter margins and slower expansion, not breakneck growth. You would need to judge whether disciplined profitability on a more measured footprint can offset recent setbacks.
"Strategic increase in private label penetration (18% consolidated, up 12% year-over-year) and improved supply chain initiatives are raising brand differentiation and margin profile, as more profitable private label sales gain share and cost control measures take hold, supporting higher gross margins and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Cencosud’s Story Connects Sideways
Cencosud’s recent setback might have you questioning big-box retail altogether.
Instead of stopping there, you could look at a neighbor in the same arena that is pushing beyond classic shelves and trolleys.
This other retailer is leaning into areas like entertainment, specialty food and digital services to keep shoppers engaged across more occasions.
Each new service gives customers another reason to stay in its orbit, even when core retail feels tougher.
The open question is how far that kind of extension can go before it meaningfully reshapes what a large retailer is for.
That argument has a Narrative and a number behind it. → See the company one Narrative values 30% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com