
Kuwait Defence Contract Might Change The Case For Investing In EOS Stock
- Electro Optic Systems Holdings reported an order book above $1.4b, a conditional Kuwait contract for a nationwide counterdrone defence system worth about £370 million, and a letter of intent from the Netherlands Ministry of Defence for Apollo High Energy Laser Weapon technology.
- The recent Memorandum of Understanding between EOS Defence Systems and VOP CZ points to deeper integration of Electro Optic Systems Holdings’ remote weapon systems into European armoured vehicle projects. This could influence production mix, execution risk, and long-term support workloads.
- We will look at how Electro Optic Systems Holdings’ investment narrative is affected by the sizeable Kuwait counterdrone defence system contract.
Scan defence contractors with similar order momentum and complex program exposure by running the 6 resilient stocks with low risk scores alongside Electro Optic Systems Holdings in your research.
Electro Optic Systems Holdings Investment Narrative Recap
To back Electro Optic Systems Holdings as a shareholder, you need to buy into a thesis built on growing demand for remote weapon systems, counterdrone solutions and space control technology, supported by an order book of more than A$1.4 billion. The key near term catalyst is execution on that backlog and conditional awards, including Kuwait, in a way that converts contracted work into cash without further stressing working capital.
The biggest current risk sits in program complexity and timing. Large, multi year defence projects can slip, be re scoped or face testing and integration challenges. The new VOP CZ MoU adds another layer of integration work in Europe, which could either deepen Electro Optic Systems Holdings’ production pipeline or create more scheduling and cost pressure if milestones move.
For this MoU, the most relevant adjacent update is the conditional Kuwait nationwide counterdrone defence contract of about £370 million. Both developments suggest that Electro Optic Systems Holdings is leaning hard into complex, system level deployments that tie its sensor, weapon station and command technologies together, rather than simple one off hardware sales.
That is where the potential upside and execution risk meet. Kuwait and potential VOP CZ programmes could reinforce revenue visibility and support the case for earnings to move toward profitability. However, delays, customer testing issues or cost overruns would quickly feed into margin pressure and cash needs. Your view on these programmes, and on management’s ability to deliver them cleanly, is central to the near term catalyst set.
Electro Optic Systems Holdings is being modelled by analysts to reach A$526.8 million in revenue and A$84.2 million in earnings by 2029. That profile implies yearly revenue growth of 60.1% and an earnings swing of about A$156.6 million from an earnings loss of A$72.4 million today.
Uncover why Electro Optic Systems Holdings' fair value indicates a 56% potential upside to its current price that could narrow quickly.
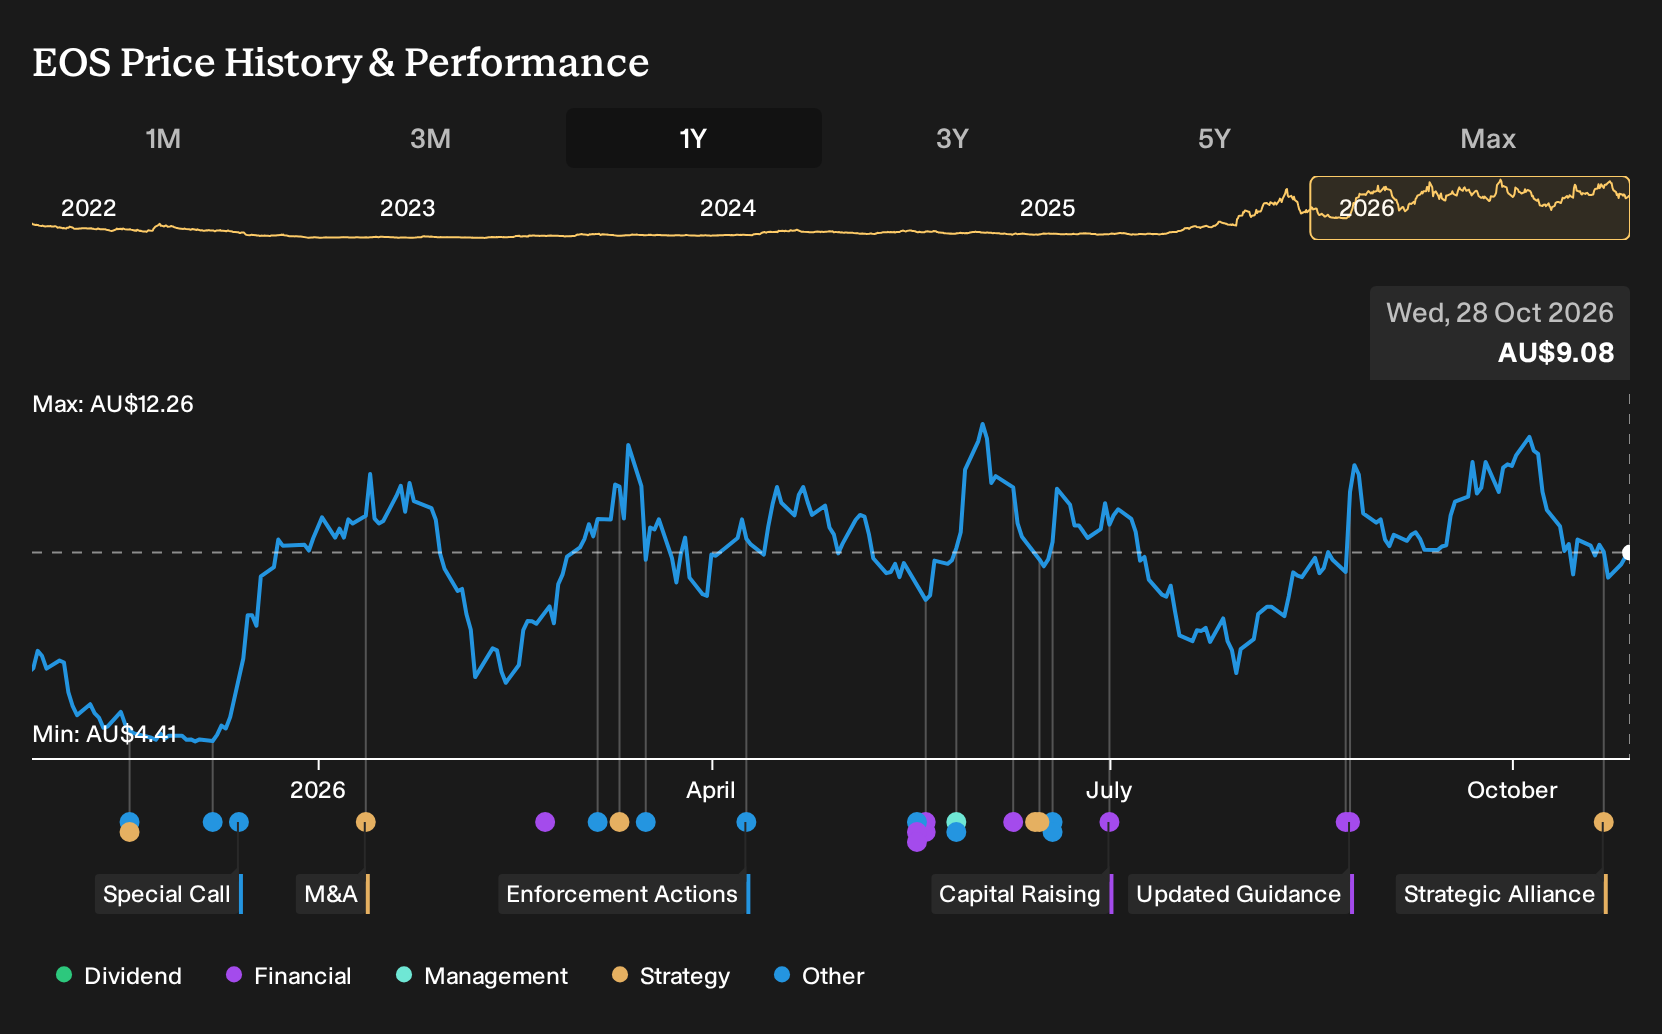
Exploring Other Perspectives
You might read this Kuwait and VOP CZ news as a major contract durability win for Electro Optic Systems Holdings, yet the lowest analysts were more focused on contract lumpiness. Before this update, they were only pencilling in revenue of about A$517.0 million and earnings of A$46.9 million by 2029, so their narrative could shift sharply from here.
Explore 4 other Electro Optic Systems Holdings fair value estimates, including one that suggests it could be worth just A$12.50!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgement.
- A great starting point for your Electro Optic Systems Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Electro Optic Systems Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Electro Optic Systems Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Electro Optic Systems Holdings?
Once you have formed a view on Electro Optic Systems Holdings, it can help to compare that thesis with other opportunities that have different balance sheet profiles, income characteristics and risk levels. The Simply Wall St Screener lets you scan for stocks that match the kind of traits you want in your portfolio, rather than relying on headlines or hype.
- For investors who prefer steadier finances and less fragile capital structures, filter for companies with stronger financial footing through the list of solid balance sheet and fundamentals (12 results).
- If you are hunting for resilient income plays, use the screener to surface potential high yield candidates that match your risk tolerance via the 4 dividend fortresses.
- Those looking for mispriced opportunities can focus on quality businesses trading below certain valuation checks by scanning the 2 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com