
Is Nokia Oyj (HLSE:NOKIA) Still Below Fair Value On Its New India R And D Deal?
Nokia Oyj (HLSE:NOKIA) has attracted fresh attention after a five year engineering and R&D agreement with L&T Technology Services in India, aligning its telecom portfolio with next generation compute, AI and 5G projects.
Investors have been weighing this new R&D pact alongside a busy October that included fresh Q4 guidance, a €0.03 dividend decision and a series of AI-RAN collaborations with NVIDIA, Super Micro Computer and Elisa. Despite a 30 day share price return that is down 11.92%, Nokia Oyj still carries a 45.55% year to date share price gain and a 3 year total shareholder return of about 1.8x.
Scan beyond Nokia Oyj and evaluate other telecom and AI infrastructure players that our team has filtered into a focused list of 55 AI infrastructure stocks for this theme.
Nokia Oyj has already delivered a strong year, yet the recent pullback and fresh AI and R&D agreements leave an obvious tension. Has the real upside now been priced in, or is the rerating only partly finished?
Most Popular Narrative: 47% Undervalued
Based on the most followed narrative, Nokia Oyj's fair value of €15.16 sits well above the recent €8.04 close, which puts this AI and telecom story firmly in value territory according to that framework.
Nokia delivered a strong second quarter, reporting revenue of €4.815 billion and earnings per share of €0.07, supported by growing demand for AI and cloud-related solutions. The company is also expanding its presence in the defense sector through AI-powered tools for 5G networks, creating additional opportunities to diversify revenue and strengthen long-term growth prospects.
See why 11 investors see Nokia Oyj as 47% undervalued.
According to TheTurntTomato, that €15.16 fair value is built using a discount rate of 7.678875%. This prices Nokia Oyj on the assumption that investors require a moderate return to compensate for risk in a large, established telecom and cloud infrastructure player. With the share price at €8.04 and the narrative implying a 47% discount to that estimate, the gap is wide enough that any future updates around AI, cloud demand or defense contracts could shift sentiment quickly.
For readers, the key takeaway is that this widely followed view leans heavily on Nokia Oyj's AI related partnerships, Q2 execution and balance sheet strength to justify a higher value than the current market price suggests.
Result: Fair Value of €15.16 (UNDERVALUED)
Still, Nokia Oyj's AI and defense narrative could be knocked off course if telecom spending slows, or if new partnerships fail to convert into meaningful contracts.
Find out about the key risks to this Nokia Oyj narrative.
Another View: What Nokia Oyj's P/E Is Telling You
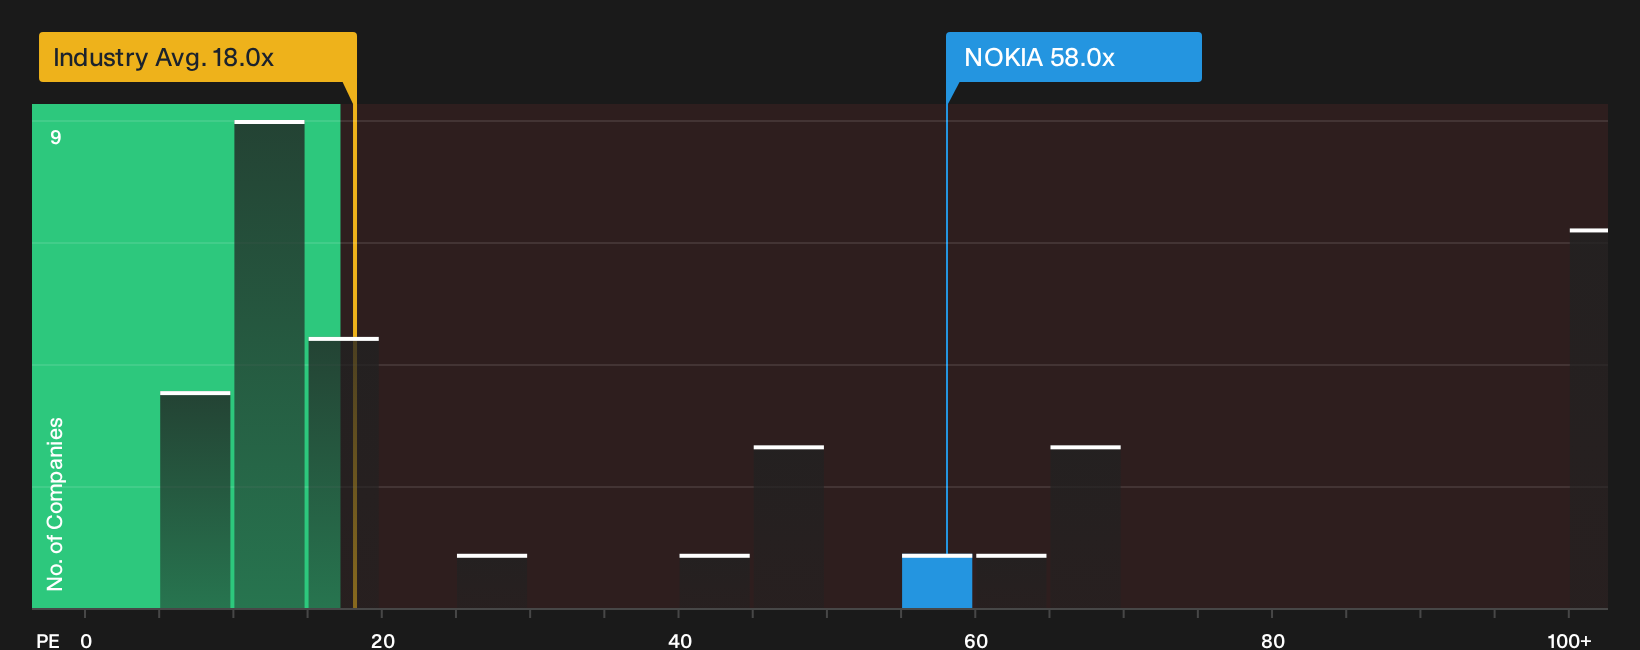
Looking at Nokia Oyj through its P/E makes the picture appear more cautious. The stock trades at 58x earnings versus 33.4x for peers and 18x for the wider European communications group, while the fair ratio sits at 57.7x. That kind of premium raises a simple question: is this pricing leaving much room for error?
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Nokia Oyj so far. If you want to move fast and cut through the noise, start by weighing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Nokia Oyj?
If you want to keep your momentum and not miss potential opportunities, the Simply Wall Street Screener can quickly surface ideas that match how you like to invest.
- Target income potential by scanning companies on our 224 dividend fortresses, which pairs higher yields with detailed balance sheet and payout data.
- Hunt for mispriced opportunities using the 195 high quality undervalued stocks, which filters for strong fundamentals at prices the market may not be fully recognising yet.
- Spot future contenders early with the 610 high quality undiscovered gems, which highlights quality businesses that many investors might still be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com