
What Granite Construction Shares Award Means For Shareholders
- Granite Construction reported being awarded the SR 202 Widening and Trestle Replacement Project Phase B in Woodinville, Washington, a roughly $16 million contract that will run from late 2026 to late 2027 and use its own asphalt and aggregate facilities.
- The combination of the Woodinville road expansion and the recent USACE Homestead BAK-12/14 arresting system contract indicates Granite Construction is converting its vertically integrated materials footprint into concrete project wins across transportation and federal work.
- We will examine how Granite Construction's investment narrative relates to the SR 202 contract win and the expanded Washington backlog.
Scan how Granite Construction’s contract momentum compares to other infrastructure focused contractors by reviewing the 42 power grid technology and infrastructure stocks now shaping major transport and grid upgrade projects.
Granite Construction Investment Narrative Recap
For Granite Construction, the core belief is that its vertically integrated materials and construction platform can turn a large public infrastructure pipeline into steadier earnings and cash flow. The Woodinville SR 202 project fits that story by using in house asphalt and aggregate capacity, but at roughly $16 million it does not materially shift the overall outlook or near term trajectory on its own.
The near term swing factor remains execution on margins in both Construction and Materials while managing weather, cost inflation and project mix. The key risk is that materials margin pressure or higher quarry and plant costs recur and investors treat them as structural, which could limit how much credit the market gives Granite Construction for any backlog wins.
The SR 202 widening and bridge replacement award looks most relevant because it links directly to Granite Construction’s materials footprint and public transportation backlog. It shows the business booking work that taps its Smith Island asphalt plant and Granite Falls aggregate facility, which can support utilization but also keeps the focus on whether materials profitability proves resilient.
Investors watching catalysts may see this project as one more data point in Granite Construction’s push toward best value contracts tied to ongoing federal and local infrastructure funding. The project timing, running from late 2026 to late 2027, adds visibility into future workload, yet it does not change the underlying risk that any slowdown in public construction spending or persistent materials cost pressure would matter more than a single contract win.
Granite Construction Forecasts Behind The SR 202 Win
Granite Construction's narrative projects US$6.5b revenue and US$687.3m earnings by 2029. According to analyst estimates, this path involves 9.6% yearly revenue growth and an earnings change of roughly US$852m, from a loss of US$164.9m today to the 2029 consensus figure.
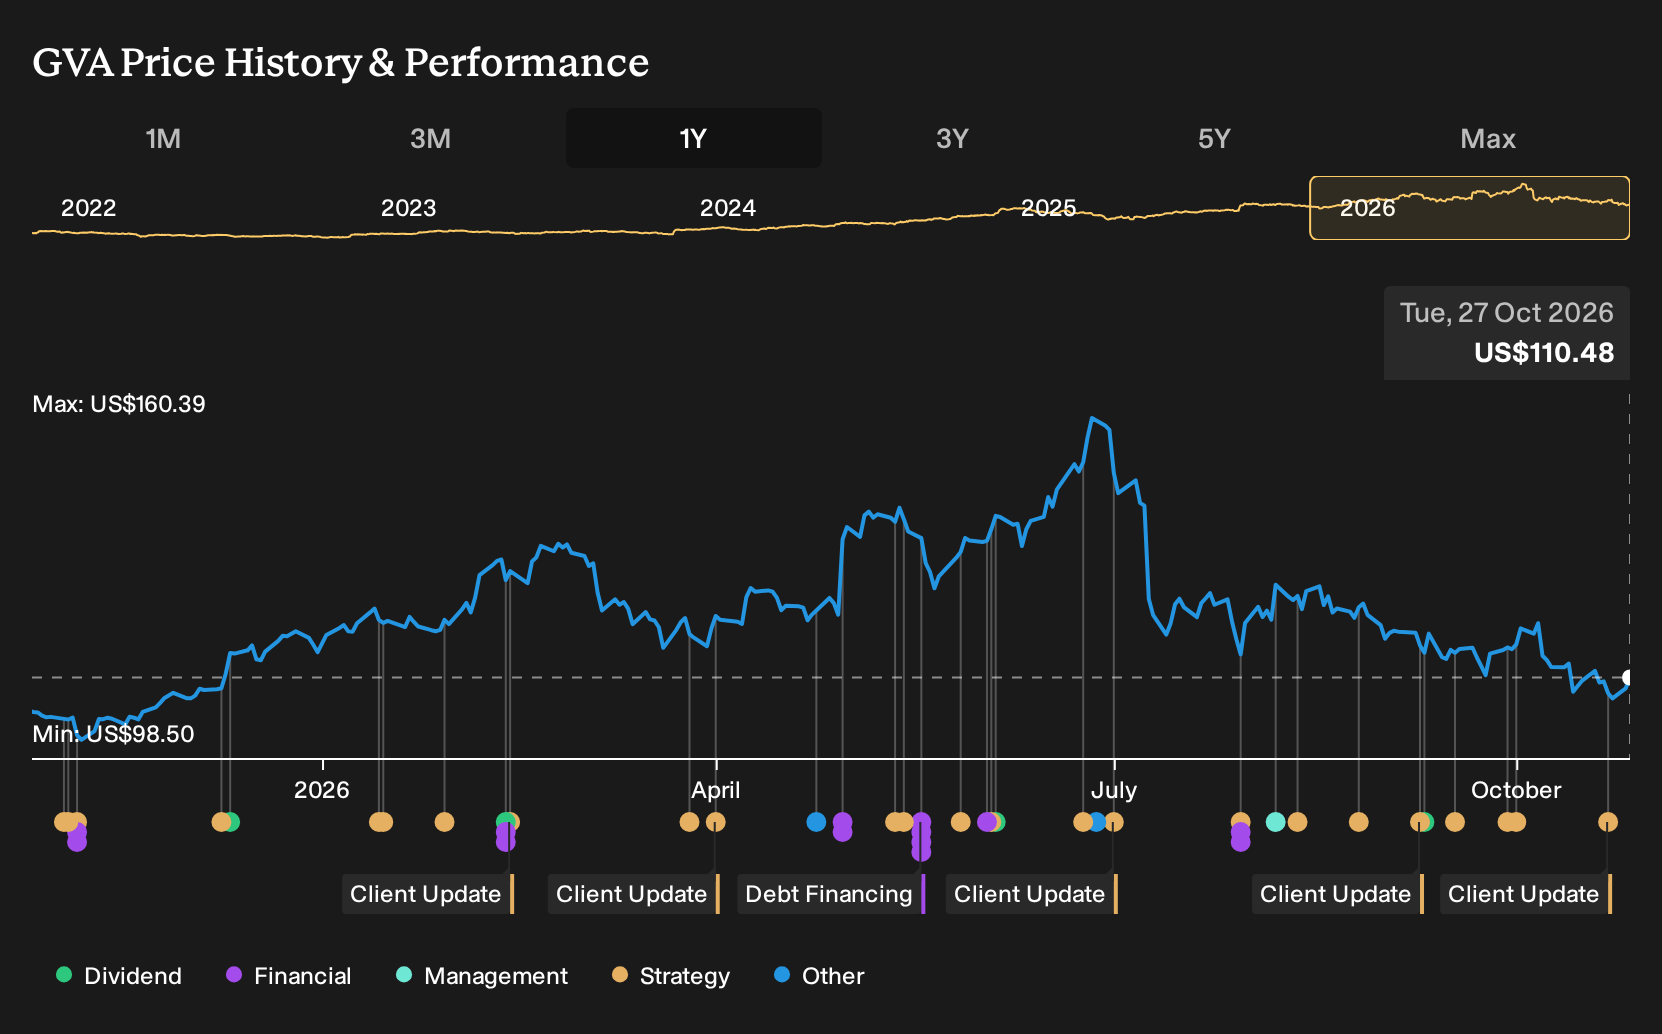
Uncover why Granite Construction's fair value signals a 55% potential upside to its current price, which could materialize sooner than many investors anticipate.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real swing factor for Granite Construction as federal and data center work. Before this SR 202 news, that group was already modeling about US$6.5b of revenue and roughly US$594.4m of earnings by 2029. You can treat this new contract as a fresh test of those stronger views, which may evolve from here.
Explore 3 other Granite Construction fair value estimates, including one that suggests as much as 81% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Granite Construction research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Granite Construction. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Granite Construction's overall financial health at a glance.
Looking For More Ideas Beyond Granite Construction?
If this Granite Construction update has sharpened your thinking about infrastructure exposure, use that momentum to scan a wider set of listed businesses. A focused screener can help you quickly line up balance sheet strength, income potential, or valuation appeal with the kind of profile you want in your portfolio.
- If capital preservation sits high on your list, filter for companies that prioritise resilience using a 30 resilient stocks with low risk scores that keep risk scores in check while still offering equity upside.
- For investors who care most about financial quality and pricing power, sort the market by valuation and balance sheet strength with a 29 high quality undervalued stocks that pair healthier cash flows with what may look like discounted share prices.
- If you want to broaden your watchlist with fresher opportunities, surface less-followed businesses that still clear solid fundamental hurdles through a 21 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com