
How Investors May Respond To Solaris Energy Infrastructure Stock As Capital Spending Builds
- Solaris Energy Infrastructure increased spending on turbines and power equipment in recent quarters, aiming to build contracted power capacity and broaden its earnings base from long term agreements.
- The heavier capital program means Solaris Energy Infrastructure is tying more of its future results to executing large power projects and converting contracts into higher margin services.
- We will now look at how Solaris Energy Infrastructure's capital heavy build out could reshape its investment narrative around earnings quality.
Scan other capital intensive utilities priced for heavy build programs by reviewing the curated 42 power grid technology and infrastructure stocks that share Solaris Energy Infrastructure's focus on grid scale infrastructure investment.
Solaris Energy Infrastructure Investment Narrative Recap
Solaris Energy Infrastructure asks you to believe that its heavy turbine build out and data center focused contracts can translate into steadier, higher quality earnings over time. The current story leans on turning a large backlog and services potential into cash flow that better covers debt, rather than just headline growth.
The fresh earnings momentum and history of topping forecasts highlight execution as the key short term catalyst, because solid quarterly delivery can keep confidence in that capital plan. The main risk is still project and financing heavy. If new sites or ancillary work slow while interest costs stay elevated, that growth narrative becomes harder to support.
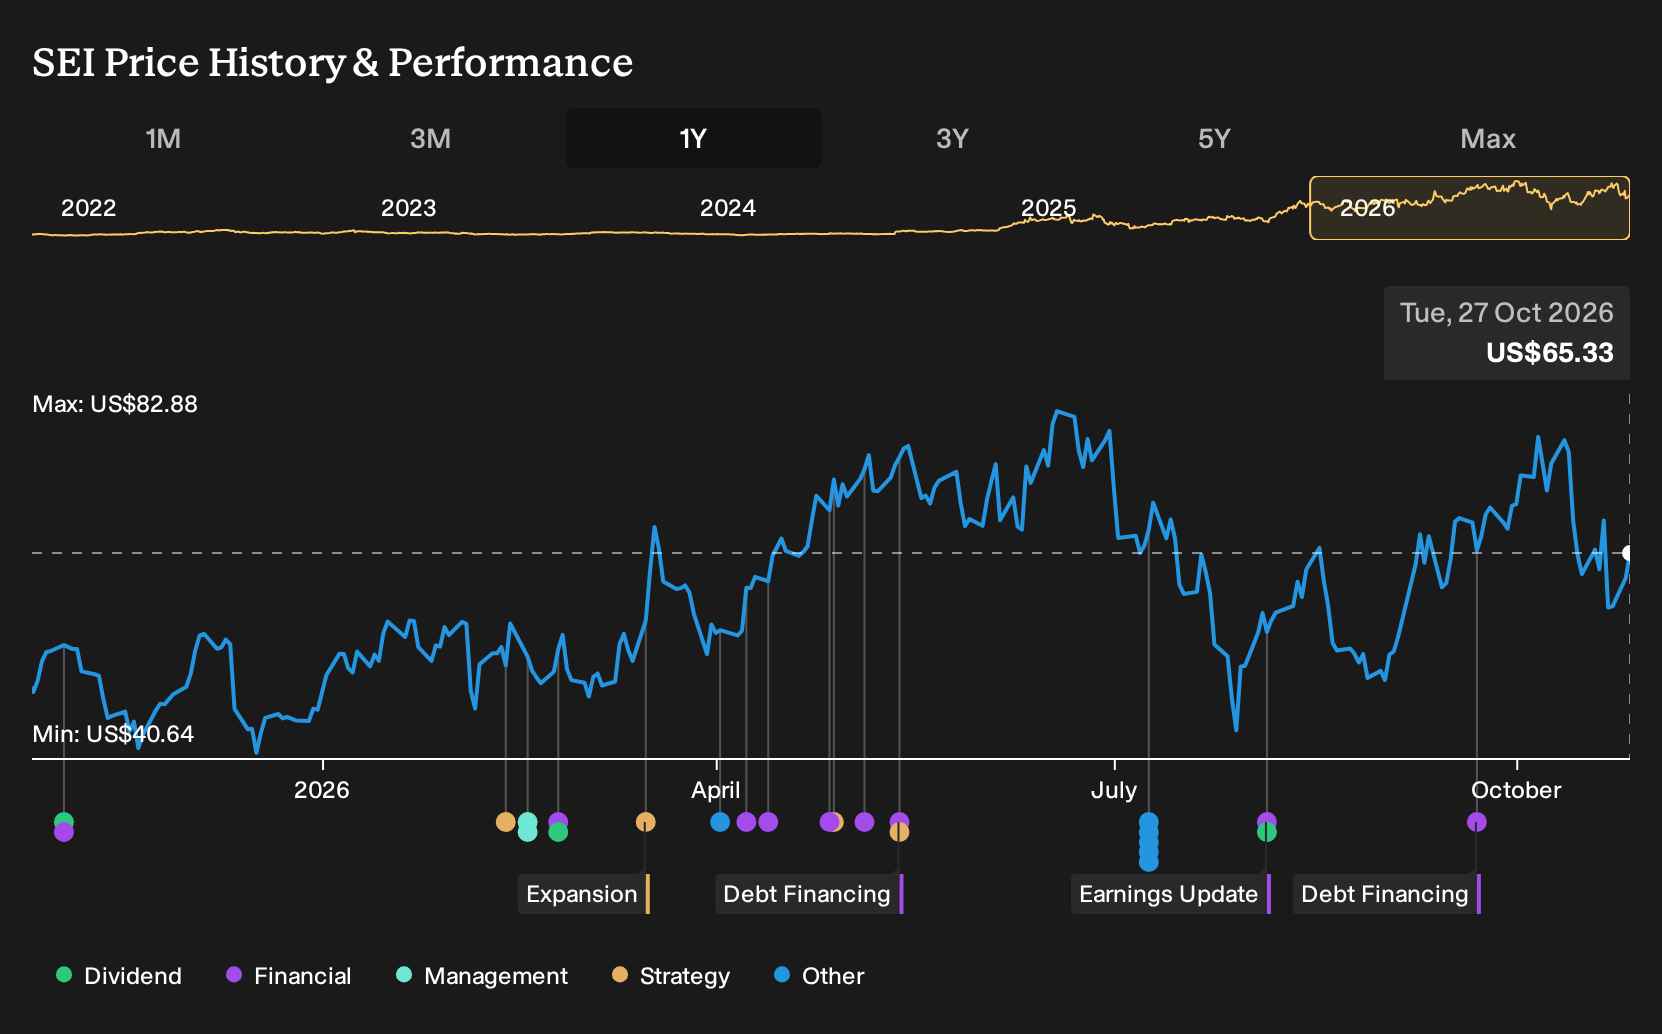
The recent pullback after a multi year rise puts the focus on how that capital program behaves against expectations. You have management committing to turbines, power equipment and grid scale projects, while the stock still trades on a high P/E. That combination makes each earnings print and project update more important to how investors judge execution risk.
Earnings outperformance in the last two quarters ties directly into that. When Solaris Energy Infrastructure converts contracted megawatts and acquisitions into reported profit, it helps validate the heavy spending and high valuation multiples. If future quarters show weaker cash conversion or slower contract replenishment, the reliance on leverage and non cash earnings could start to matter more than the recent beats.
Solaris Energy Infrastructure's narrative projects US$2.5b in revenue and US$559.7 million in earnings by 2029. That outlook implies 49.2% yearly revenue growth and would increase projected earnings by roughly US$507 million from the current US$53.0 million base.
Uncover why Solaris Energy Infrastructure's fair value indicates a 55% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Solaris Energy Infrastructure, the alternate story leans on customer concentration risk. The most cautious analysts worry that a setback at a few large data center clients could bite harder than consensus implies. They were only penciling in about US$2.2b of 2029 revenue and US$274.9 million of earnings before this news. That is far below the baseline forecasts, so treat this update as a chance to compare both narratives and decide which assumptions feel closer to your own view.
Explore 4 other Solaris Energy Infrastructure fair value estimates, including one that suggests it could be worth just $82.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Solaris Energy Infrastructure research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Solaris Energy Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Solaris Energy Infrastructure's overall financial health at a glance.
Looking for more Solaris Energy Infrastructure style ideas?
If the Solaris Energy Infrastructure story has you thinking about where else contracted cash flows, balance sheet strength, or future growth potential might show up, the Simply Wall St Screener can help you line up other stocks with similar traits and pressure test your thesis across more than one ticker.
- For investors who care most about quality and price working together, scan a curated set of businesses through 29 high quality undervalued stocks that pair solid fundamentals with valuations that may leave room for upside.
- If capital preservation and steadier profiles are higher on your checklist, focus on companies screened for durability using the 30 resilient stocks with low risk scores as a starting universe.
- When you want to go beyond well-known tickers and search for less crowded ideas, cast a wider net with the 21 high quality undiscovered gems that highlights companies with stronger fundamentals than their visibility might suggest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com