
Should Low P E Focus Require Action From Aperam (ENXTAM:APAM) Investors?
- Aperam has drawn fresh attention after a period of sharp share price swings, as investors reassess whether its current valuation reflects its earnings profile and business shift toward Recycling & Renewables and Alloys & Specialties.
- The renewed focus on Aperam’s comparatively low P/E versus peers, combined with tax credits and self help measures, is pushing investors to re-evaluate how much weight to place on its non traditional stainless activities within the overall earnings mix.
- This article examines how Aperam's investment narrative is being reframed as investors focus on its low P/E and recycling pivot.
Scan beyond Aperam and pressure test this earnings and valuation story against a curated set of 195 high quality undervalued stocks that also pair low P/E ratios with meaningful business shifts.
Aperam Investment Narrative Recap
Aperam suits investors who buy into a story where European stainless benefits from tighter trade rules and carbon regulation, while Recycling & Renewables and Alloys & Specialties gradually take a bigger share of earnings. The short term swing factor is whether the recent uplift of about €75 per tonne in European spot net margins holds up as imports and demand ebb and flow.
The main operational risk right now is that weak European stainless demand or fresh pricing pressure caps how much of that margin uplift actually reaches group profit, especially with net margins sitting around 2.1% and below last year. That would keep the gap between Aperam’s current earnings, its tax credits and self help potential firmly in focus.
With no fresh company announcements filed since this latest bout of share price volatility, the most relevant reference point is still management’s Leadership Journey Phase 6 program. It has reportedly delivered €38m of gains toward a €150m target for 2026 to 2028, which keeps cost reduction firmly embedded in the investment debate.
If Aperam keeps executing on those efficiency actions while growing Recycling & Renewables and Alloys & Specialties from their current combined €2,712m of revenue, that could reinforce the thesis that earnings quality is improving even if European stainless conditions stay mixed. Any stumble in delivering the remaining self help gains or in running these newer segments efficiently would raise questions about how much weight to give the current P/E discount story.
Aperam's current analyst narrative points to revenues of €8.5b and earnings of €496.2m by 2029, based on assumed yearly revenue expansion of 11.9% and an earnings increase of about €369m from the €127.0m recorded today.
Uncover how Aperam's fair value indicates a 45% potential upside to its current price before that valuation gap closes.
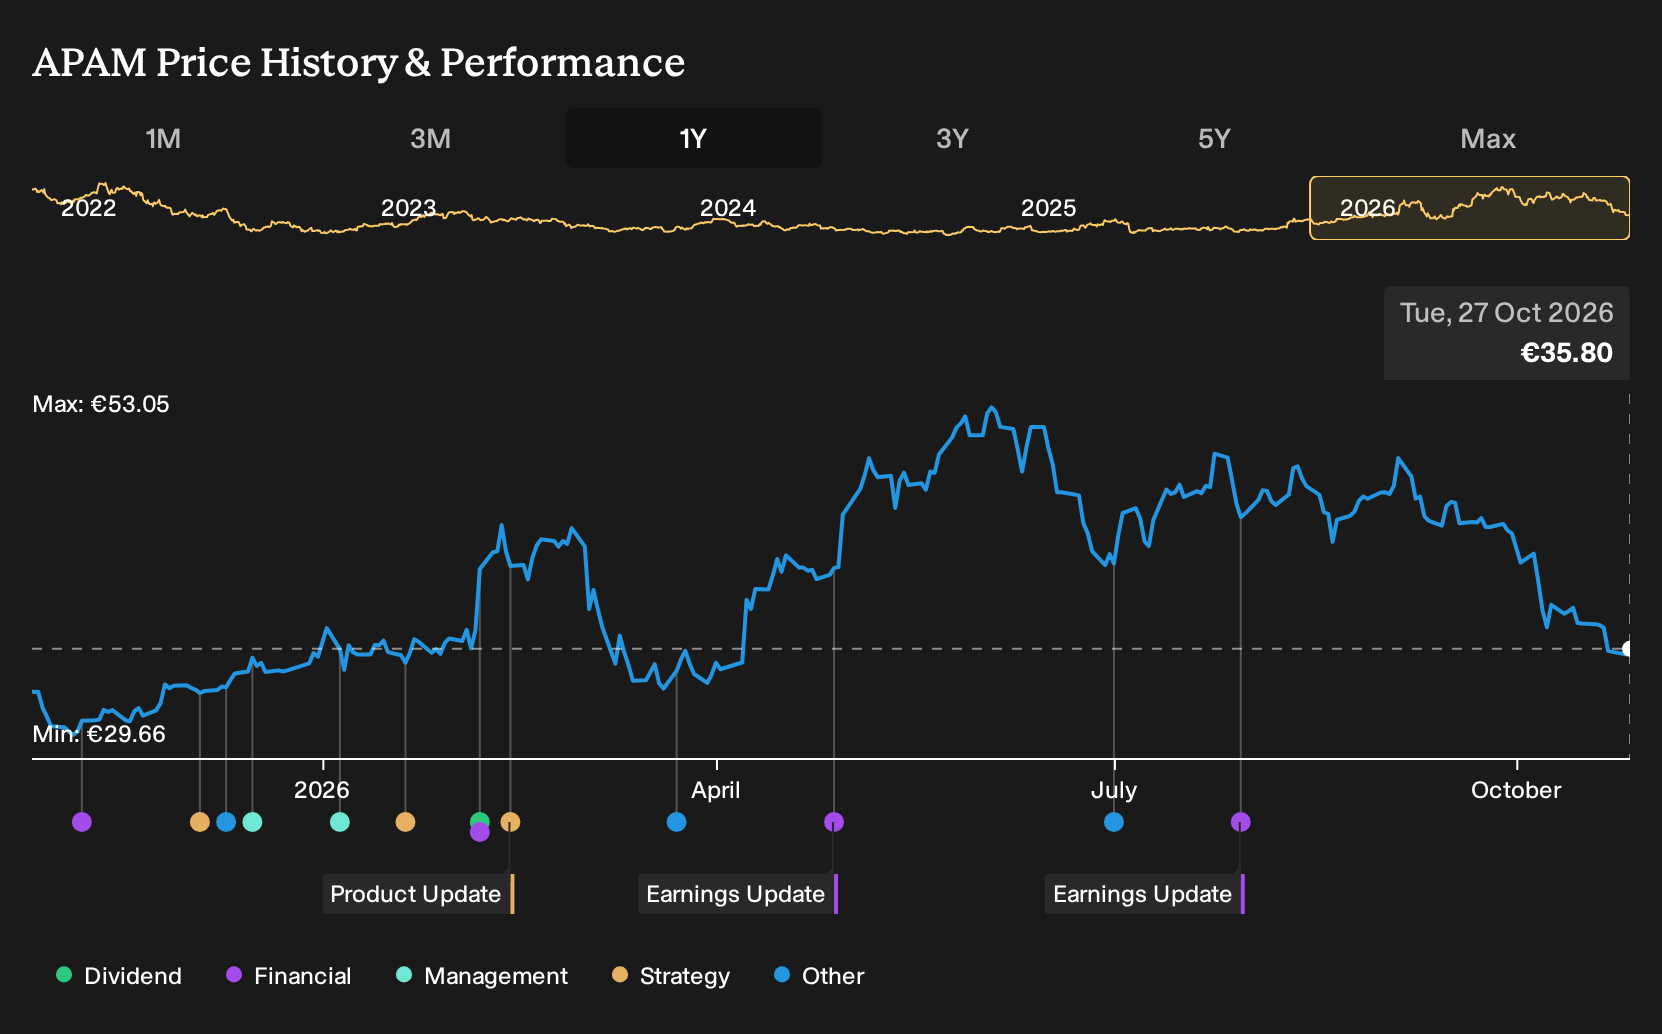
Exploring Other Perspectives
For Aperam, the key swing factor in the alternate narrative is how resilient European stainless demand really is. The lowest analysts were already cautious before this latest volatility, pencilling in about €7.5b of revenue and €434.6m of earnings by 2029. That view bakes in weaker growth and suggests expectations could shift again as this news settles.
Explore 3 other Aperam fair value estimates, including one that suggests it could be worth just €51.89!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Aperam research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aperam. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aperam's overall financial health at a glance.
Looking For More Ideas Beyond Aperam?
If the Aperam story has sharpened your view on valuation, earnings quality and business transitions, you can use that same lens across the wider market with the Simply Wall St Screener.
- Put value first and focus on companies that pair stronger fundamentals with a clear pricing gap by reviewing our 195 high quality undervalued stocks.
- If resilience matters most to you, stress test your downside protection by filtering for 223 resilient stocks with low risk scores that score well on overall risk profiles.
- If you prefer balance sheet strength as your starting point, begin your search with a list of solid balance sheet and fundamentals (207 results) to see which businesses keep leverage and liquidity in tighter control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com