
Earnings Estimate Raise Change The Bull Case For Trane Stock (TT)?
- Trane Technologies is heading into its upcoming earnings release with Wall Street projecting quarterly EPS of $4.74 and revenue of $6.44b, both higher than the figures reported for the same period a year earlier.
- The recent upward shift in consensus EPS estimates over the past month highlights growing attention on how effectively Trane Technologies converts its order book and capacity investments into earnings quality.
- We will look at how Trane Technologies' investment narrative lines up with the higher quarterly earnings estimate that analysts now expect.
Scan how Trane Technologies' earnings setup compares with a hand-picked 29 high quality undervalued stocks that pairs solid fundamentals with potentially more attractive entry points.
Trane Technologies Investment Narrative Recap
To own Trane Technologies, you generally need to believe the HVAC and refrigeration business can keep converting its record order book into durable earnings, helped by services and energy efficiency demand. The higher earnings and revenue expectations for this quarter speak directly to that question. If Trane executes cleanly, the story around backlog quality and pricing discipline stays intact.
The near term swing factor is still how effectively Trane prices against inflation while working through its US$12.1b backlog, especially in Americas commercial HVAC and data center related projects. The biggest risk remains any slowdown or deferral in non residential projects or continued regional softness, particularly where Middle East weakness and mix already pressure margins.
There have been no fresh corporate announcements tied to this specific earnings setup, so the most relevant reference point for you is still Trane Technologies' existing backlog and capacity expansion around commercial HVAC and data center cooling. Those earlier investments in applied systems capacity and modular solutions are exactly what current quarterly expectations are testing.
As this earnings release approaches, the key thing to watch is how management updates on backlog conversion, pricing versus cost inflation and regional trends rather than any single headline. If Trane confirms that data center and commercial HVAC orders are flowing through without heavier margin drag from Middle East weakness or input costs, that would speak directly to the catalysts and the main risk investors are weighing today.
Trane Technologies' current analyst narrative points to revenues of US$29.5b and earnings of US$4.7b by 2029, based on an assumed 10.0% yearly revenue growth rate and an earnings increase of about US$1.7b from US$3.0b today.
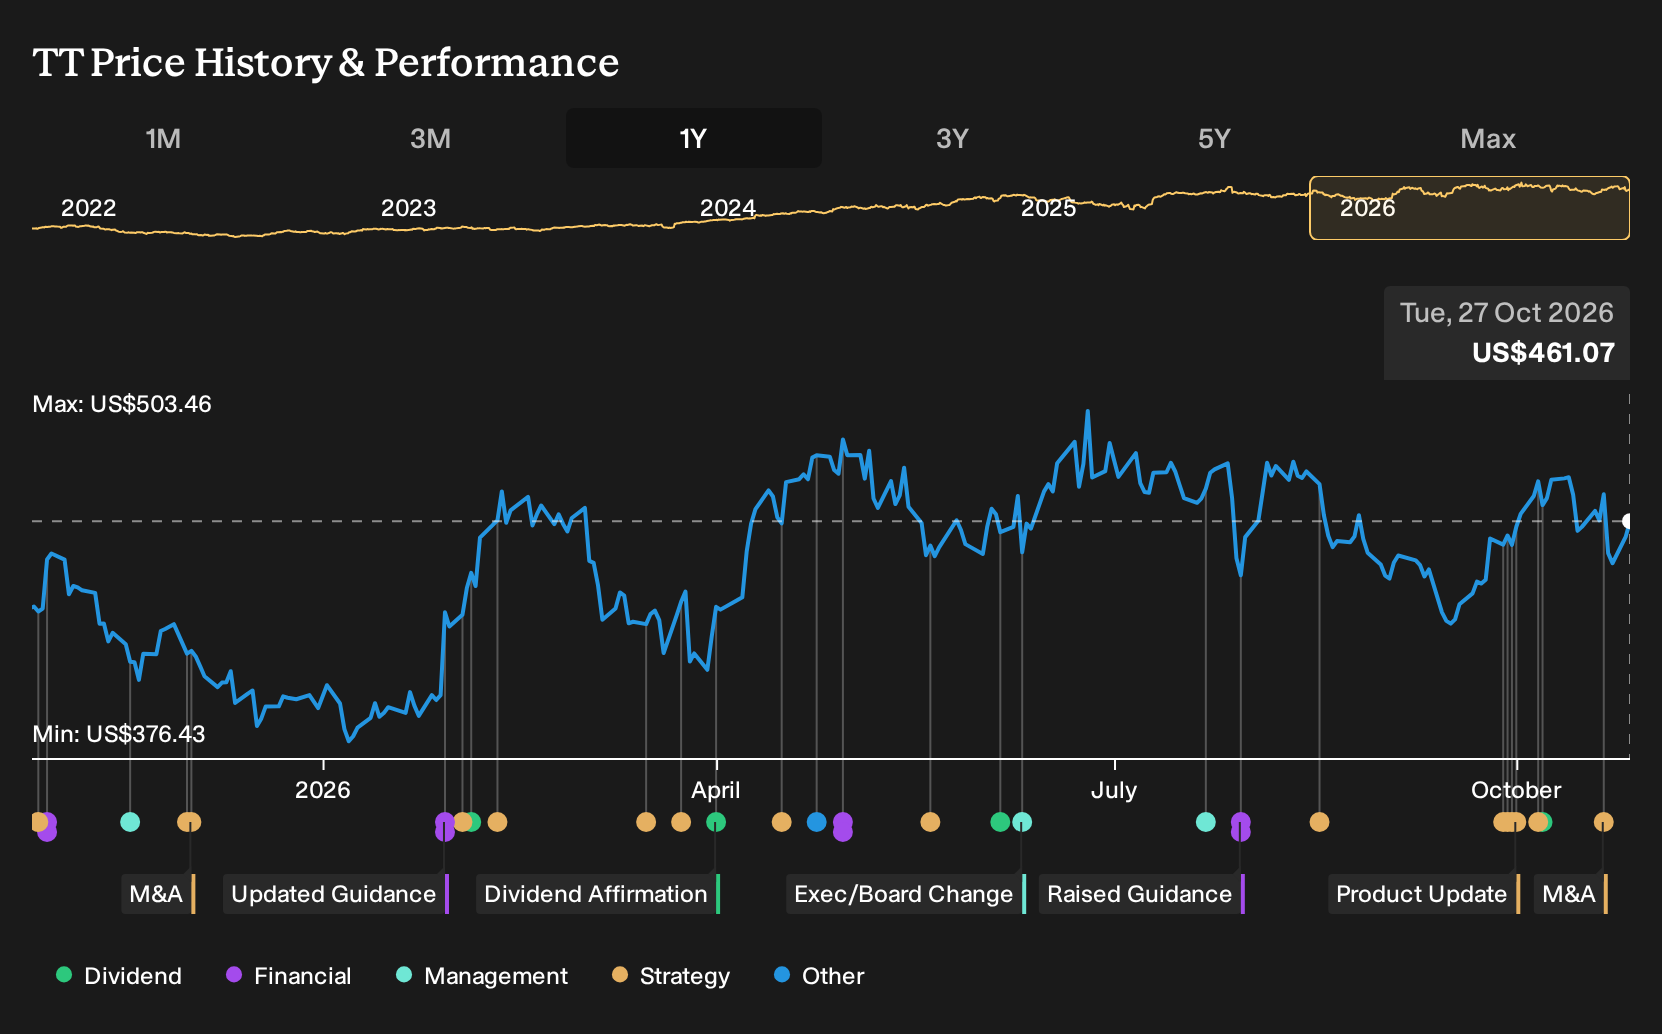
Uncover why Trane Technologies' fair value indicates a 14% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate angle focuses on Trane Technologies’ data center and AI cooling push as the real swing factor. The most optimistic analysts were penciling in revenues of about US$31.7b and earnings near US$5.1b by 2029 before this earnings news. That is far above the consensus path, so views may change as fresh information lands.
Explore 4 other Trane Technologies fair value estimates, including one that indicates up to 15% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Trane Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trane Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trane Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Trane Technologies?
Once you have a view on Trane Technologies, it can help to broaden your watchlist with companies that offer different risk and return profiles, all filtered through clear fundamental data.
- If capital preservation sits near the top of your priorities, start with a curated set of resilient businesses in the 30 resilient stocks with low risk scores that focus on lower risk scores and steadier profiles.
- For investors who want financial strength front and center, filter for balance sheets and core metrics that look robust using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for potential mispricings, scan companies that pair business quality with more appealing entry points through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com