
How Strong Earnings At Beijer Ref Stock Has Changed Its Investment Story
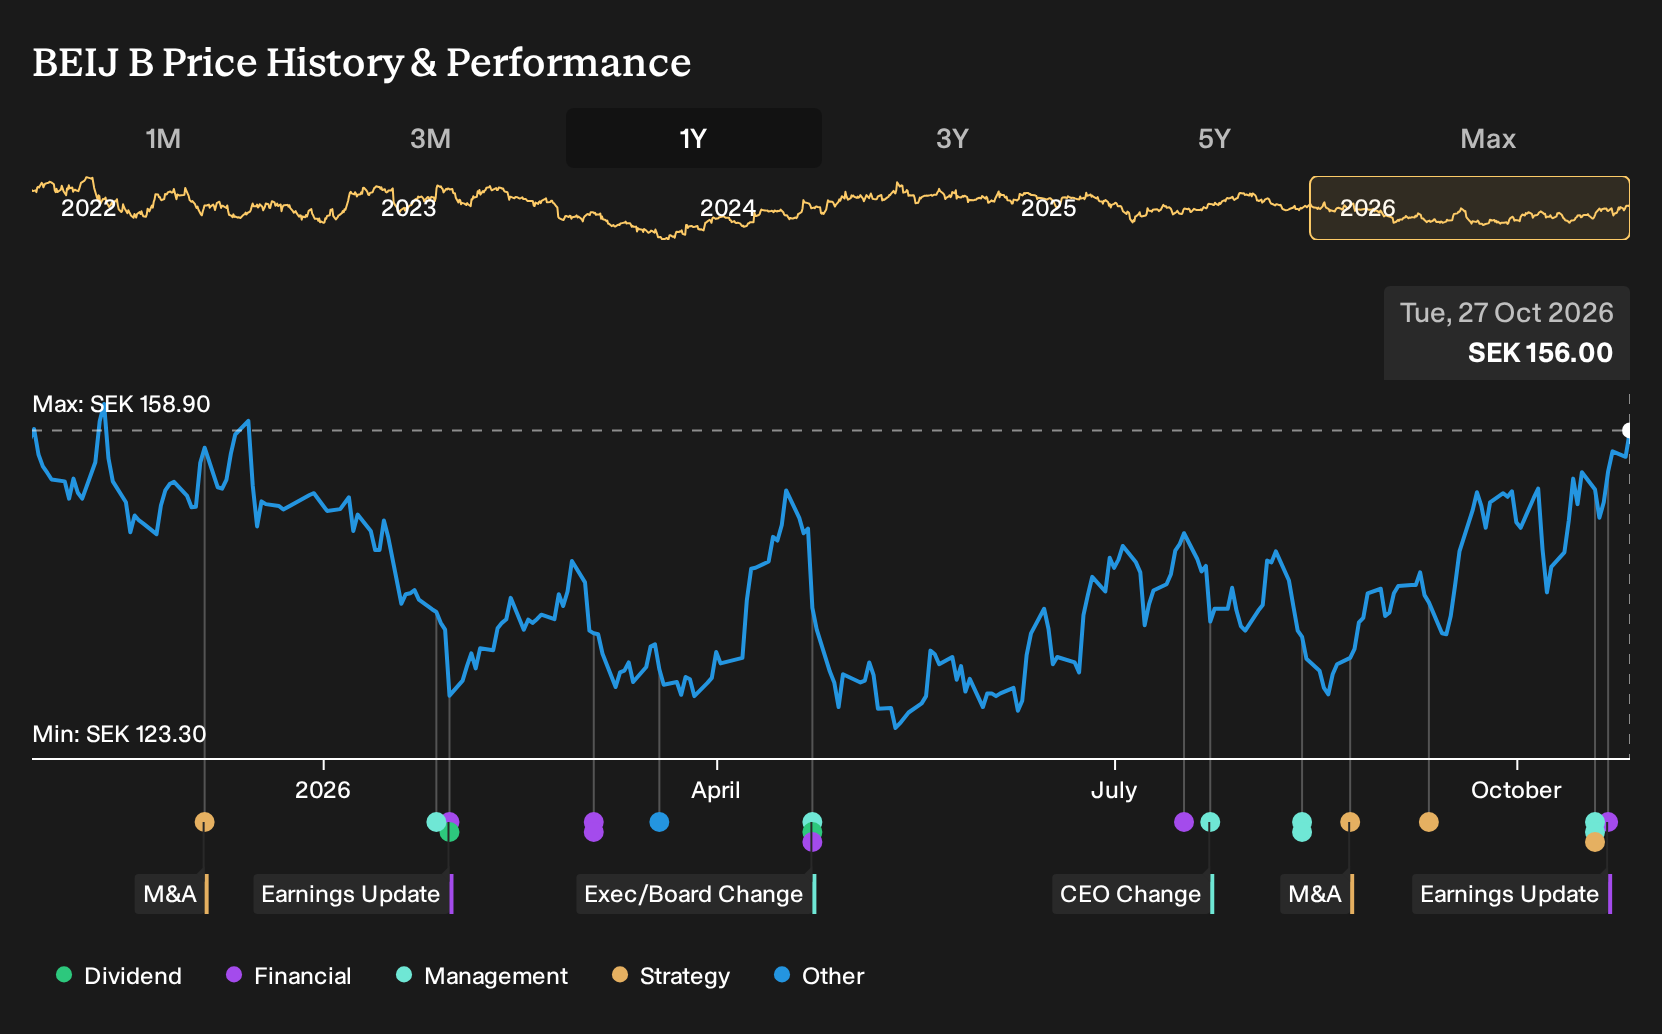
- Beijer Ref reported third quarter 2026 sales of SEK 11,641 million and net income of SEK 869 million, alongside higher basic and diluted earnings per share from continuing operations compared with the prior year period.
- The board also confirmed long serving executive Jonas Steen as incoming CEO and President, pairing earnings progress with leadership continuity and keeping an experienced insider close to day to day operations.
- We will now look at how Beijer Ref's latest earnings step and incoming CEO could shape the broader investment narrative.
Scan how Beijer Ref’s earnings momentum and leadership change compare with other potential opportunities by reviewing a curated 610 high quality undiscovered gems list that screens for strong fundamentals and under-the-radar potential.
What Is Beijer Ref's Investment Narrative?
To own Beijer Ref, you need to be comfortable with a fairly execution heavy refrigeration and HVAC distributor that already carries a premium P/E of 31.6x versus an estimated fair multiple of 28.9x and a sector average of 16.5x. The latest quarter shows SEK 11,641 million in sales and SEK 869 million in profit, with nine month earnings still supported by SEK 30,976 million in revenue and SEK 2,175 million in net income, which points to demand that is holding up across EMEA, APAC and North America.
In the short term, the real swing factors are how consistently Beijer Ref can convert that broad footprint into cash generative growth while running a capital intensive logistics network and managing borrowing based funding. The appointment of long serving insider Jonas Steen as CEO slots into that story as an operational continuity play rather than a reset, with an experienced board and management team already in place, although forecast earnings growth of 17.4% and revenue growth of 12.7% still need to justify a valuation that screens as expensive versus DCF.
Yet the picture changes once you start to weigh that premium price tag against one specific pressure point that keeps building quietly in the background...
There's only one way to know the right time to buy, sell or hold Beijer Ref. Head to Simply Wall St's company report for the latest analysis of Beijer Ref's Fair Value.
Exploring Other Perspectives
One alternate view focuses on execution risk in Beijer Ref’s green OEM projects. The most pessimistic analysts were only baking in about 4.7% annual revenue growth and earnings of roughly SEK 3.1 billion by 2029, well below the most optimistic SEK 4.0 billion path. These forecasts predate the latest CEO news and earnings, so opinions may still shift.
Explore 3 other Beijer Ref fair value estimates, including one that suggests as much as 24% downside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Beijer Ref research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Beijer Ref. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beijer Ref's overall financial health at a glance.
Looking For More Investment Ideas Beyond Beijer Ref?
Once you have a view on Beijer Ref, it helps to compare that thesis with other companies that have very different risk and return profiles so you can see where it really earns a spot in your portfolio.
- For investors who want potential upside without paying up for every krona of earnings, take a look at a curated set of 195 high quality undervalued stocks that pair quality metrics with compressed P/E ratios.
- If capital preservation matters just as much as growth, anchor your watchlist around a 223 resilient stocks with low risk scores that filters for resilient balance sheets and more stable business profiles.
- To round things out with strong financial footing, build a comparison basket using a list of solid balance sheet and fundamentals (207 results) so Beijer Ref sits alongside peers with similar fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com