
Mycronic (OM:MYCR) Could Be 6% Undervalued Following Raised 2026 Guidance
Mycronic (OM:MYCR) has raised its 2026 net sales guidance to SEK 9.75b from SEK 9.25b, alongside third quarter figures that show higher sales and profitability than the prior year.
Mycronic’s higher guidance and strong third quarter figures arrive after a mixed price pattern, with the share price down 9.28% over the past month but still showing a 39.89% year to date share price return and a 5 year total shareholder return of 223.09%. This suggests momentum has been strong over the longer run even as investors reassess shorter term expectations around the SEK303.0 level.
Scan how Mycronic’s upgraded outlook stacks up against other high quality companies by running through our curated 195 high quality undervalued stocks.
Mycronic now trades at a discount to both its own estimated value and to analyst targets after a strong quarter and higher 2026 sales guidance. Is that gap a sign of justified caution, or has pricing drifted too far?
Most Popular Narrative: 6% Undervalued
Mycronic’s most followed valuation story pegs fair value around SEK321.67, slightly above the latest close at SEK303. This frames today’s gap as modest rather than extreme and puts the focus on how future orders and margins evolve.
Growing equipment demand linked to AI and data center buildout, reflected in record SEK 2.9b group order intake in Q2 2026 with strong contributions from Global Technologies, High Volume and Pattern Generators, points to a broadening order pipeline that can support future revenue and operating profit.
See why 10 investors see Mycronic as 6% undervalued.
Result: Fair Value of SEK321.67 (UNDERVALUED)
Still, the Mycronic narrative can be knocked off course if PCB Assembly Solutions misses its SEK100m profit uplift or if lower margin Pattern Generators products dilute group returns.
Find out about the key risks to this Mycronic narrative.
Another View: What Mycronic’s P/E Is Signalling
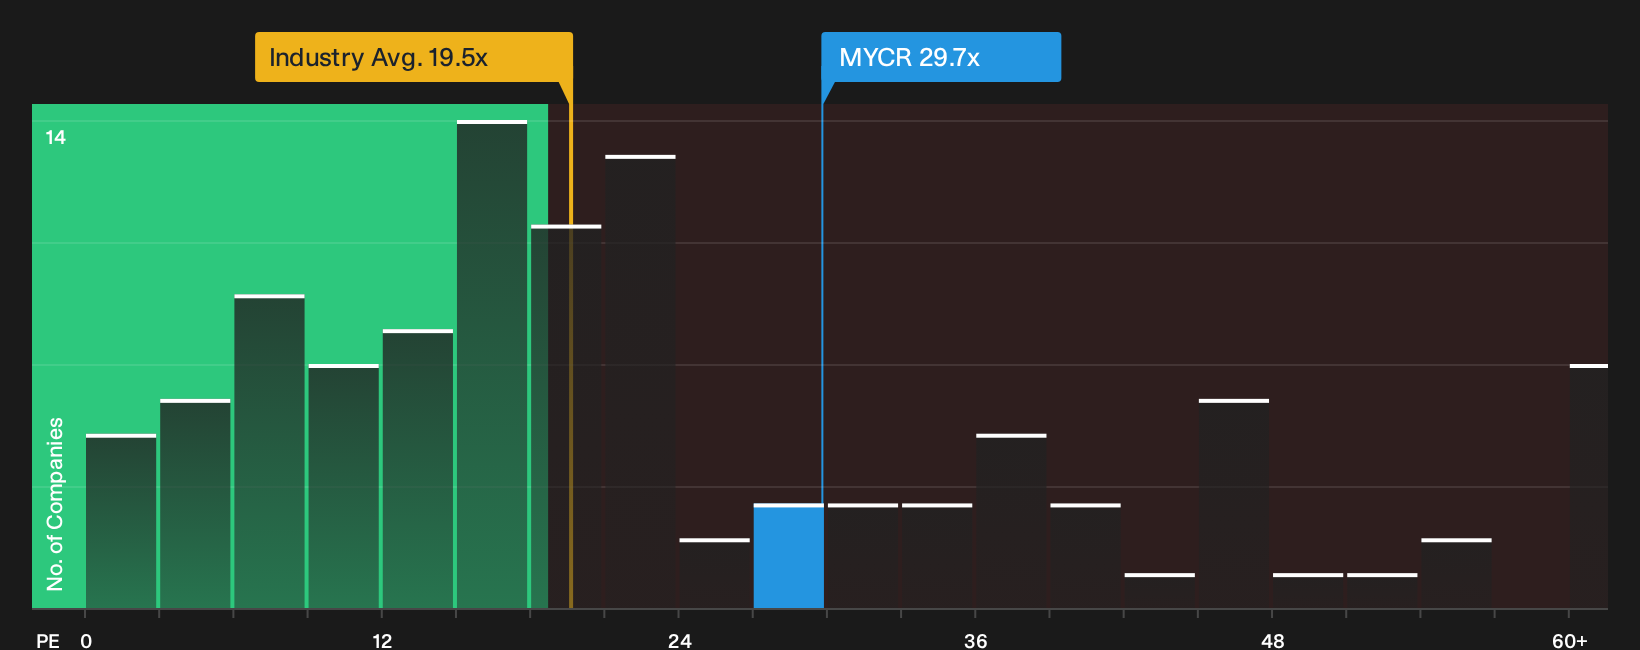
There is a twist. While Mycronic looks undervalued against an estimated future cash flow value of SEK377.23 per share, the market is still paying a rich 29.7x P/E. That compares with 22.3x for peers, an industry average of 19.2x, and a fair ratio of 25.9x.
The gap suggests investors are accepting extra valuation risk in return for its growth and quality profile. The question is whether that premium feels comfortable once sentiment cools or earnings progress slows a little.
See what the numbers say about this price in our valuation breakdown, then weigh that premium against your own expectations for future returns See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how Mycronic’s valuation lines up against the wider sector, review the latest comparison of its earnings multiple with peers
Next Steps
If the mixed signals around Mycronic leave you torn between caution and optimism, consider acting promptly and test the story against the hard numbers yourself by reviewing its 3 key rewards
Looking for more Mycronic-sized ideas?
Do not stop with Mycronic. Broaden your watchlist with a few focused searches that surface different types of opportunities before the crowd pays attention.
- Target resilient compounding potential by scanning companies that combine dependable balance sheets with fundamental strength through our list of solid balance sheet and fundamentals (207 results).
- Hunt for mispriced quality by focusing on businesses that screen as both financially strong and attractively valued via the 610 high quality undiscovered gems.
- Prioritise capital protection by concentrating on businesses that clear strict risk filters using the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com